Peanut
June 22, 2026
💼 Checking the Value Trap Behind the S&P 'A-' Rating - 2026.06.22
Hello. I'm Peanut, finding the intersection of fundamentals and valuation.
Today (22nd), Hanwha Aerospace closed flat (0.00%) at 1,122,000 KRW. Trading volume was 132,899 shares, with foreign net selling of 880 million KRW and institutional net buying of 5.39 billion KRW.
💼 S&P 'A-' Rating Acquisition, A Victory for Fundamentals?
It became the first Korean defense company to receive an 'A-' credit rating from the global credit rating agency S&P [1]. The rating outlook is 'Stable'. It is evaluated on the same level as global defense big players like Lockheed Martin and BAE Systems [1]. S&P viewed the order backlog of about 37 trillion KRW as of the end of 2025 and the global export expansion of main weapon systems like the K9 self-propelled howitzer and Chunmoo positively [1]. CFO Kim Chul-hong mentioned that this rating acquisition will be a core element in securing trust with overseas governments and investors [1]. In addition, it is diversifying its financing channels by signing an agreement with Hana Bank for defense export local currency foreign currency payment guarantees and facility/operation fund support [8].
But let me pause and ask a question here. Is that really the case? Can it be verified that the 37 trillion KRW order backlog will directly translate into profits? Considering the lead time until orders are booked as revenue and cost control capabilities, blind cheering requires caution.
📉 Unmanned Systems and Export Diversification, The Flip Side of Rosy Prospects
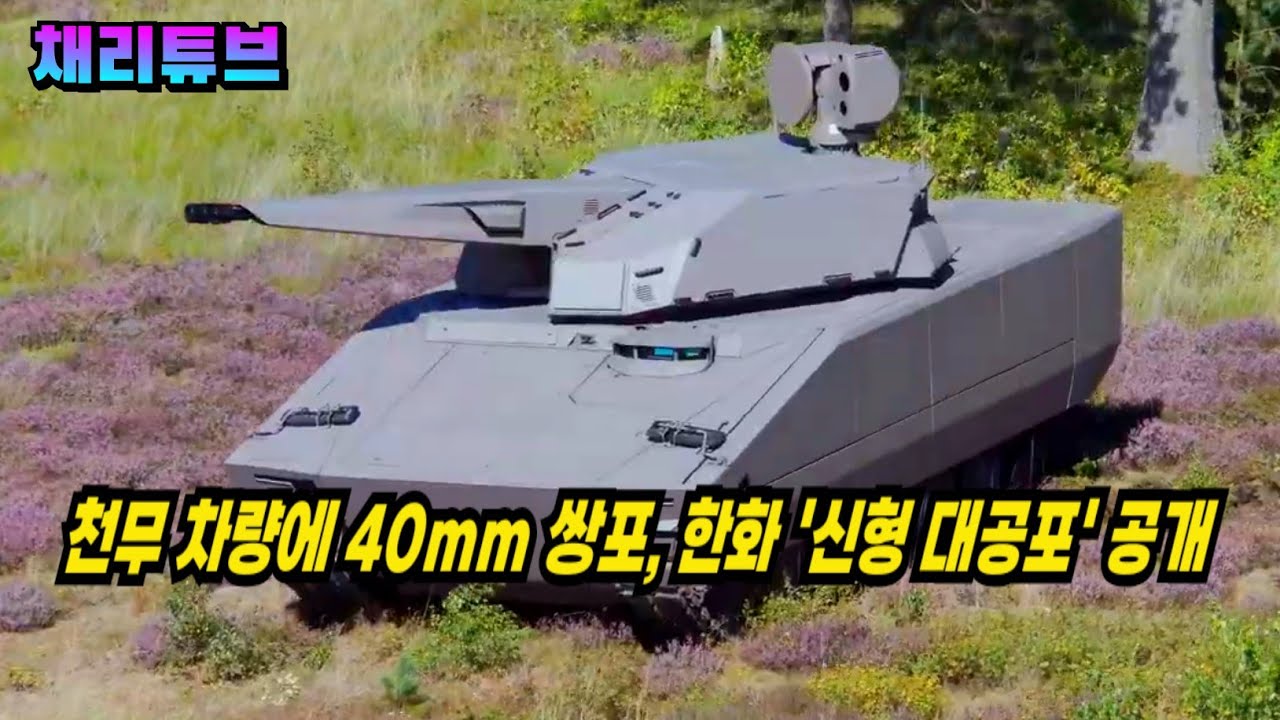
Recent technological moves are also notable. It has delivered a statement of requirement to mount Poongsan's multi-purpose combat drone 'MCD-7S' on the next-generation Korean Infantry Fighting Vehicle (K-NIFV) [3]. It is speeding up the establishment of a Manned-Unmanned Teaming (MUM-T) system with the goal of actual deployment in 2030 [3]. Also, at the Daejeon Defense Exhibition, a mock-up of an unmanned wheeled air defense system integrating the Navy's 40mm twin gun onto a Chunmoo vehicle was unveiled [9]. It is scheduled to be developed by mid-2027 as a Defense Acquisition Program Administration rapid demonstration acquisition project [9]. On the export front, it is expanding its territory into the Middle East by promoting the local production and sales of K9 self-propelled howitzers in the UAE [5], and it signed an MOU with France's Thales for the integration of multiple rocket launcher weapon systems [4].
⚠️ Checking Hidden Risks Amidst the Bullish Trend
Short to medium-term swing. Presenting a bearish scenario at least once even in a bullish atmosphere is my principle. Even amidst the bright spotlight of export momentum and the acquisition of a global credit rating, we must coldly assess the risks. On June 1st, a tragic explosion occurred at the Daejeon plant, killing 5 workers [2]. This is already the third explosion accident, and criticism of the corporate culture is growing regarding the recurring safety issues at the production site and the owner family's response [2]. From an ESG perspective, such severe accident risks can be fatal. Factory operation disruptions and increased safety management costs are at risk of leading to damage in operating profit margins. We must always leave open the possibility of a value trap hidden behind the halo of the global 'A-' credit rating.
🛑 How to Avoid the Valuation Trap
The will to expand into future new businesses is clear, such as proposing the establishment of a joint venture with Krafton for physical AI joint development [6] and promoting the development of an off-road robotics platform with robot technology company GINT [7]. However, we need to weigh whether these future values are already pre-reflected at the current stock price level. Although there are expectations that the earnings momentum will re-strengthen in the second half [10], we must remain cautious until we confirm how the Daejeon plant accident recovery costs and delivery delay risks will be reflected in the financial statements.
Peanut sees that the safety cost risk hidden behind the current flashy order rally and credit rating upgrade will be a key variable in gauging candidates for profit-taking trimming.
Numbers don't lie, but sometimes they hide unseen costs. I will return next week with a cool-headed perspective.
📰 Reference News (8)
Hanwha Aerospace Earns S&P 'A-' Rating... CFO Kim Chul-hong: "Strengthening Global Competitiveness in Defense, Space, and Aviation" - Financial News
파이낸셜뉴스 · 2026.06.22
📰 View original
[ABC News Focus] Third Explosion Disaster at Hanwha Aerospace
네이버뉴스 · 2026.06.22
📰 View original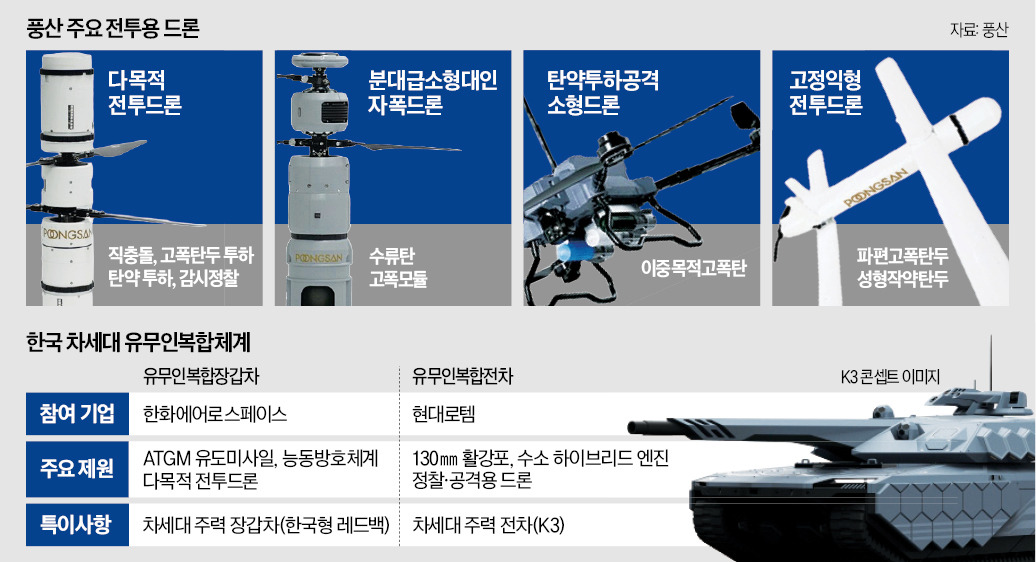
[Exclusive] Poongsan for Next-Generation K-Tank
네이버뉴스 · 2026.06.22
📰 View original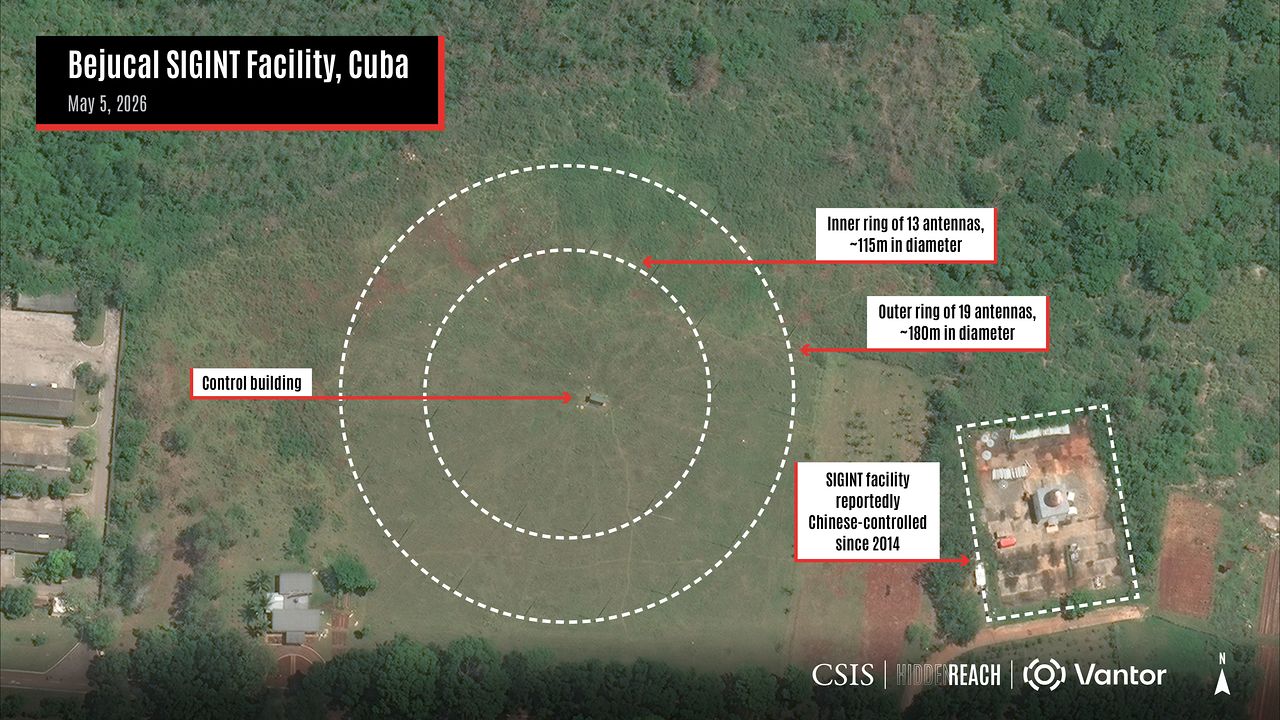
'Trump's Next Target' Cuba Operates Spy Base Targeting the US... Is China Behind It? [Military Briefing]
네이버뉴스 · 2026.06.22
📰 View original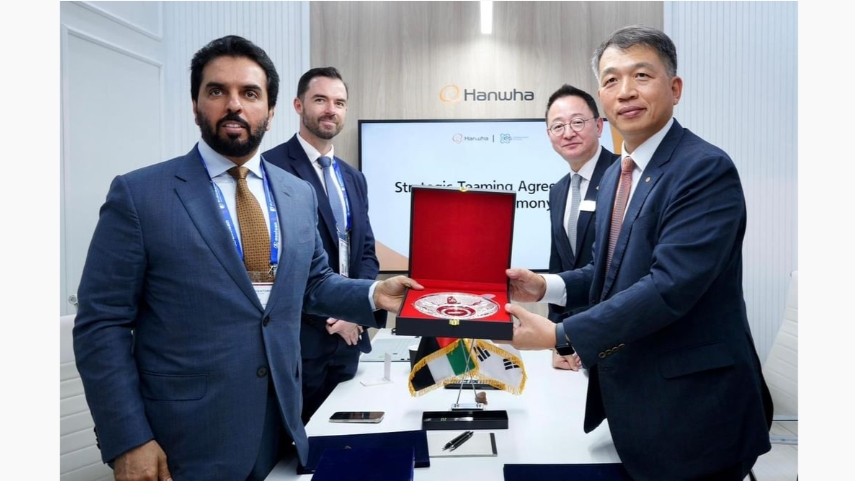
Hanwha Aerospace Pushes to Produce and Sell K9 Howitzers in UAE... Expanding Export Footprint in the Middle East - The Guru
더구루 · 2026.06.21
📰 View original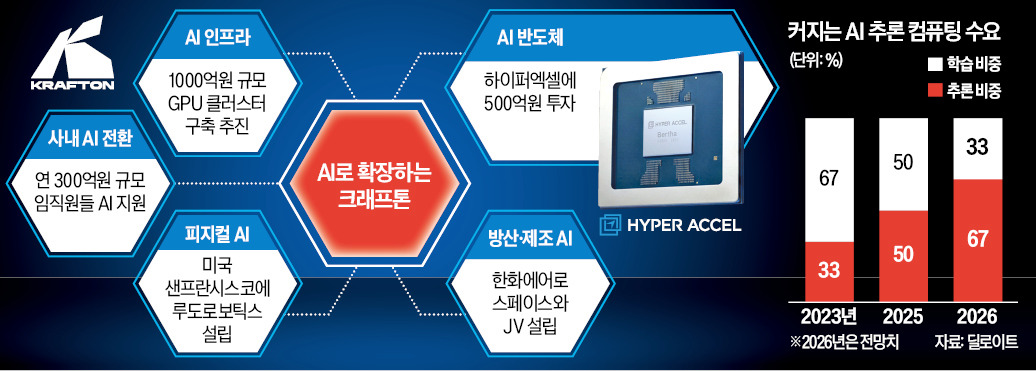
[Exclusive] From a Gaming Company to an AI Enterprise
네이버뉴스 · 2026.06.22
📰 View original
GINT Participates in Indonesia's Smart Factory Adoption Support Project
네이버뉴스 · 2026.06.22
📰 View original
Banks Compete in Defense and Aerospace Financing... Successive Trillion-Won Support for KAI
네이버뉴스 · 2026.06.22
📰 View original📺 Reference Videos (2)

Comments 0
to comment Login