Peanut
June 10, 2026
💼 [Hyundai Mobis] Physical AI Premium and Lamp Sale Noise: Beware the Value Trap - 2026.06.10
Hello, this is Peanut from Bultagi.com.
Amid today's (10th) highly volatile market where the KOSPI plunged 4.52%, Hyundai Mobis also closed at 566,000 KRW, down 4.87% from the previous day. Institutions fueled the downward pressure by net selling 50.52 billion KRW. As the broader market shakes, we need to coldly dissect the reality of the narratives surrounding Mobis.
💼 Does the Physical AI Momentum Truly Justify the Fundamentals?
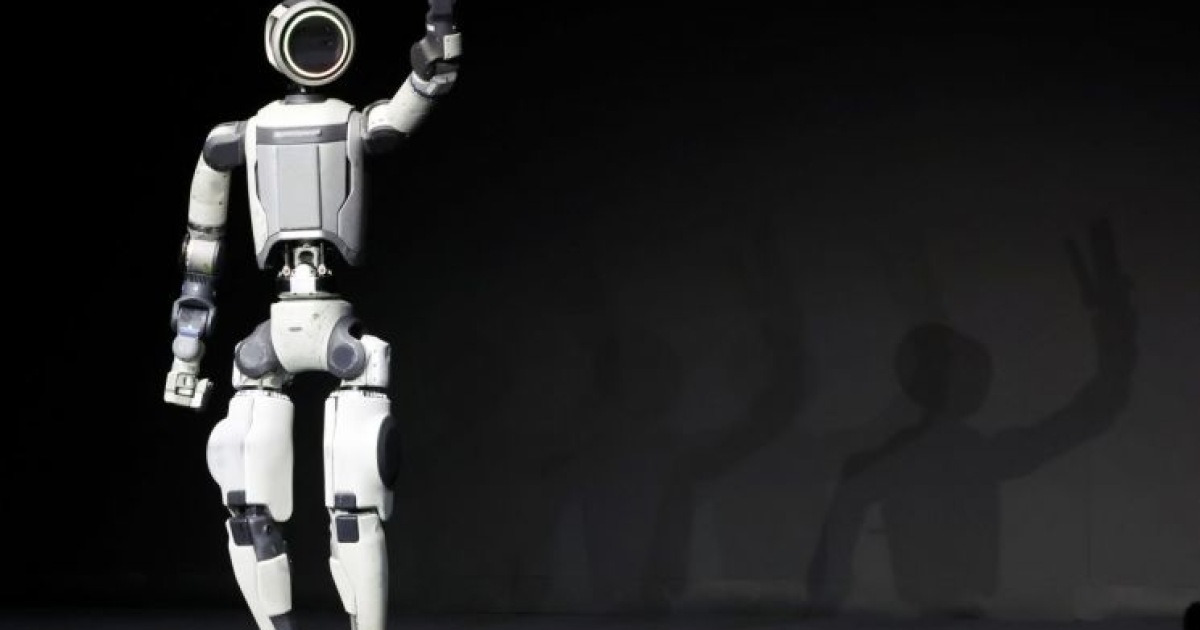
The current talk of the market is undoubtedly 'Physical AI' and robotics. KB Securities raised its target price by a massive 60% to 1.2 million KRW, reflecting expectations for the supply of actuators for the humanoid robot 'Atlas' [1]. They presented an aggressive scenario where actuator-related sales could reach 186 trillion KRW if Atlas captures a 60% share of the industrial humanoid market by 2035. But is this figure truly verifiable at this current juncture?
Of course, positive passive capital inflows are observed on the supply and demand side. Mirae Asset's 'TIGER Hyundai Motor Group Plus ETF' net assets have grown 8 times since the beginning of the year to record 935.9 billion KRW, with Mobis weighting around 16.3% [2]. Additionally, Mobis was included with a high weight of 26.74% in Samsung Asset Management's 'KODEX Hyundai Motor Robotics Value Chain TOP3 Plus' listed yesterday (9th) [3]. Furthermore, they are injecting real capital to strengthen future mobility capabilities by investing 1.0988 trillion KRW in the HMG Future Complex, a new R&D hub in Wirye [4].
⚠️ Lamp Sale Difficulties and Supply Chain Noise: Value Trap Caution is Needed
However, even in a bullish atmosphere, we must always examine the underlying bearish scenario. The sale of the Lamp Business Unit (BU), which is being pushed for structural improvement of the core business, is stuck in a fog due to labor-management communication difficulties [5]. As internal noise, such as issues accompanying the relocation of R&D personnel, prolongs, there is a risk that the timeline for rebuilding the portfolio centered on electrification will be delayed.
On top of this, the issue of procuring alternative parts due to the fire at the Chennai plant in India late last month is a variable that could burden short-term earnings and supply chain stability [6]. Although overshadowed by the glamorous future vision of robotics, noise in the core business that generates immediate cash flow can act as a limiting factor for valuation expansion.
Approaching from a short-to-mid term swing perspective, until the current robotics premium is proven by actual profit fundamentals, exposure to extreme volatility is inevitable. Peanut sees this as a profit-taking trim candidate that requires a conservative approach while observing the resolution of core business noise, rather than blindly jumping on the bandwagon of expectations in the current phase.
📰 Reference News (6)
Hyundai Mobis, Core Supplier for 'Atlas' Parts... Target Price Hits 1.2M Won [Stock to Watch] - v.daum.net
v.daum.net · 2026.06.09
📰 View original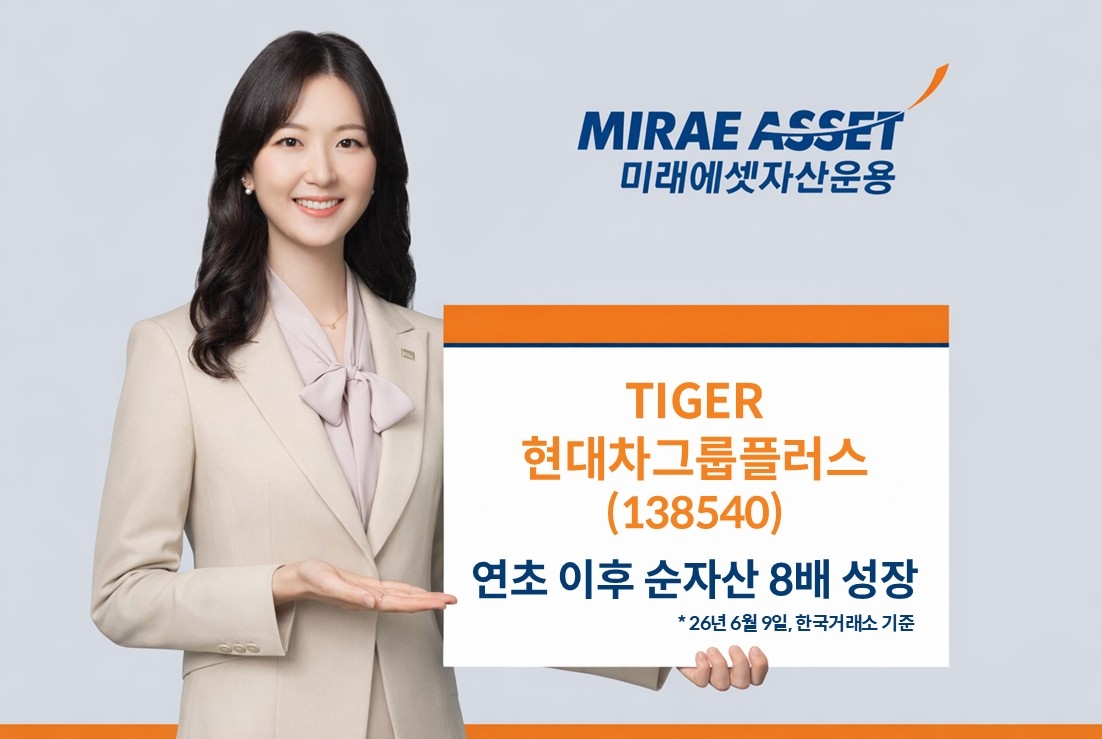
Mirae Asset's 'TIGER Hyundai Motor Group Plus ETF' Net Assets Grow 8x YTD
네이버뉴스 · 2026.06.10
📰 View original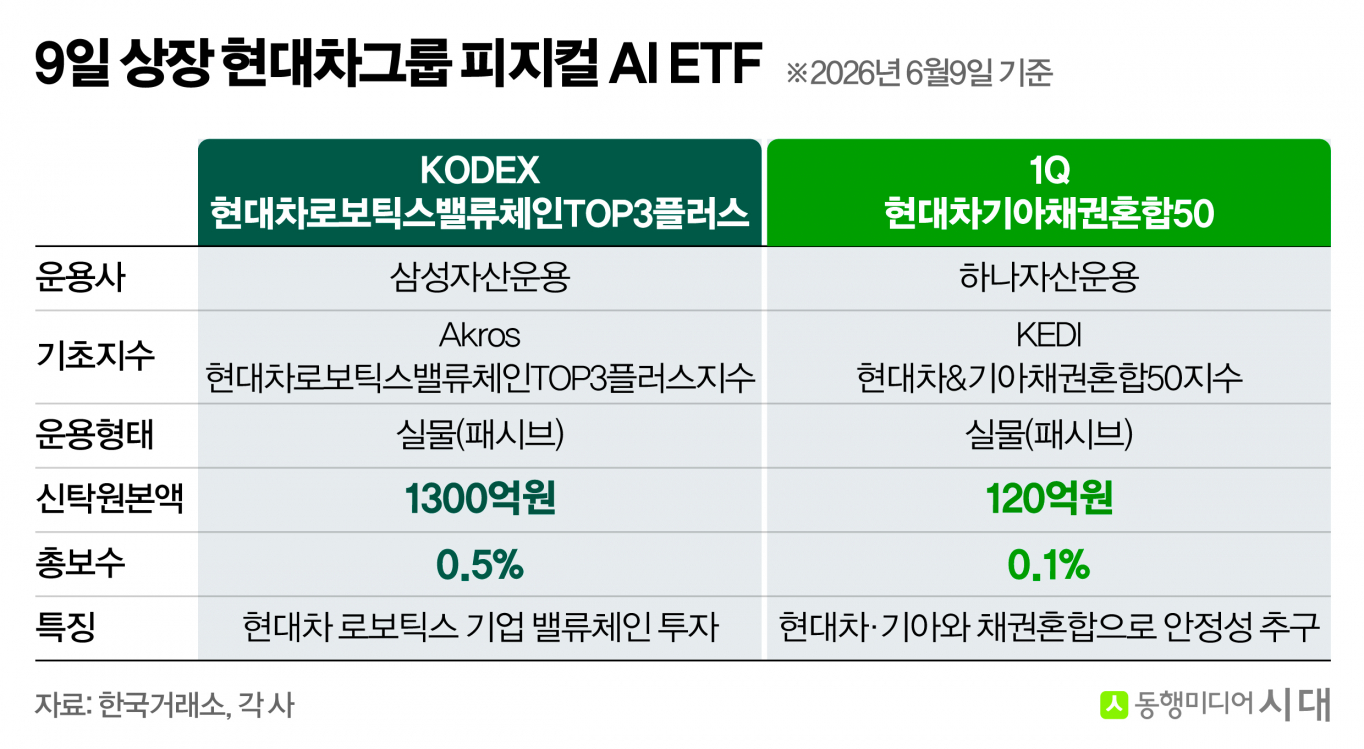
[Check! ETF] Physical AI
네이버뉴스 · 2026.06.09
📰 View original
Hyundai Motor Invests 2.6T Won in New Wirye R&D Hub
네이버뉴스 · 2026.06.10
📰 View original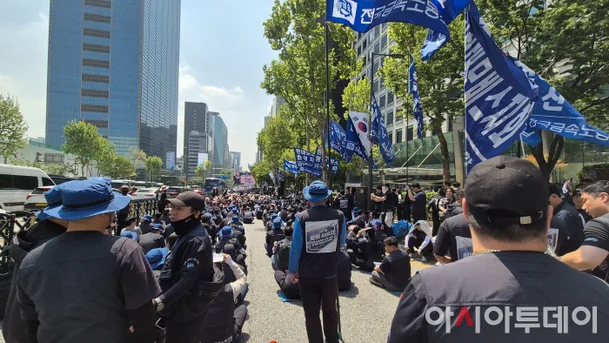
Hyundai Mobis Lamp BU Sale 'Uncertain'... Labor-Management Talks 'Stalled' - Nate
네이트 · 2026.06.10
📰 View original
Major Manufacturing Outlook for 2nd Week of June - Participation & Innovation
네이버뉴스 · 2026.06.09
📰 View original
Comments 0
to comment Login