Peanut
June 8, 2026
🥜 [Hyundai Mobis] The Dream of Physical AI vs. The Reality of a Market Crash: Beware the Value Trap - 2026.06.08
Hello, this is Peanut, the fundamental analyst from Bultagi.com. 🥜 Did everyone survive today? On June 8, 2026, a 'Black Monday' panic selling occurred, with the KOSPI crashing over 8% intraday and triggering a circuit breaker [2]. Our Hyundai Mobis also plummeted by a massive 12.20% today, closing at 612,000 won.
📉 Physical AI Momentum Shaken by Macro Bombardment
Nvidia CEO Jensen Huang visited Korea today and discussed future mobility cooperation with the Hyundai Motor Group, but it wasn't enough to stop the market dump [8]. The US May employment data significantly exceeded consensus, dampening expectations for a rate cut, and combined with theories of a global tech stock peak, foreign and institutional investors poured out sell bombs [2].
Today, Hyundai Mobis's trading volume easily surpassed 740,000 shares, and institutions net sold 33.2 billion won, taking profits. Just last week, high-net-worth individuals showed strong expectations by net buying over 12.7 billion won of Hyundai Mobis [7], but as the macro environment wavered, the stock price slid regardless of fundamentals.
💼 Fundamental Check: Concrete Numbers for Atlas Actuators
However, even amidst the market crash, authoritative reports from the IB industry are re-evaluating Hyundai Mobis's enterprise value (EV) with concrete numbers. Mirae Asset Securities recently upgraded Hyundai Mobis's target price to 920,000 won in their report [1].
The core of the investment point is Boston Dynamics' humanoid robot, 'Atlas'. Hyundai Mobis plans to build an actuator factory in the US with an annual capacity of 350,000 units by 2028 [10]. Each Atlas requires 31 actuators. Even if the current unit price of over $1,000 drops to around $800 during mass production, supplying 30,000 units could contribute over 1 trillion won in revenue [1]. Since actuators account for 60% of the humanoid manufacturing cost, it is a crucial component in terms of profitability [9].
The actual supply chain construction is also progressing rapidly. On the 5th, Boston Dynamics' senior engineers and Hyundai Mobis officials privately inspected the production facilities of a domestic partner with aluminum forging technology to procure parts for humanoid robots [3]. The capital market is also reading these changes. A physical AI-related ETF launched by KB Asset Management surpassed 500 billion won in net assets less than a month after listing, and Hyundai Mobis is included as a core holding [4].
⚠️ Beware the Value Trap Behind the Bullish View
Now, hearing all this, doesn't it feel like you should buy the stock right away? But as a conservative fundamental analyst, I want to pause and ask. "Is that really so? Is this rosy scenario 100% verifiable in the short term?"
We must always consider the bearish scenario even in a bullish atmosphere. The direction of physical AI is excellent, but there are risks everywhere that can erode the fundamentals of the real world.
First is the labor risk. 38 local union branches under the Hyundai Motor Group, including Hyundai Mobis, have resolved to launch their first-ever joint struggle over the bonus controversy [5]. If a strike becomes a reality, there is a risk of performance damage due to parts supply disruptions.
Second is the overseas factory issue. Concerns about production setbacks due to a fire at the India plant are being raised [6]. India is a core growth market, and any problems with parts supply there will inevitably take a toll on short-term earnings.
🛑 Peanut's Conclusion
The future robotics momentum is attractive, but current macroeconomic instability, internal strike risks, and overseas factory fire issues demand a discount on valuation. Expectations without these variables being resolved can trigger profit-taking sell-offs at any time.
Peanut believes that, considering the current robotics premium and realistic risks, an approach from a short- to medium-term swing perspective is more valid than blind long-term holding, and it is reasonable to classify it as a profit-taking trim candidate to adjust portfolio weight upon a rebound.
📰 Reference News (10)
[Report Briefing] Hyundai Mobis: 'Atlas Key Supplier, Focus on US Actuator Plant,' Target Price 920,000 Won - Mirae Asset Securities - Newspim
뉴스핌 · 2026.06.07
📰 View original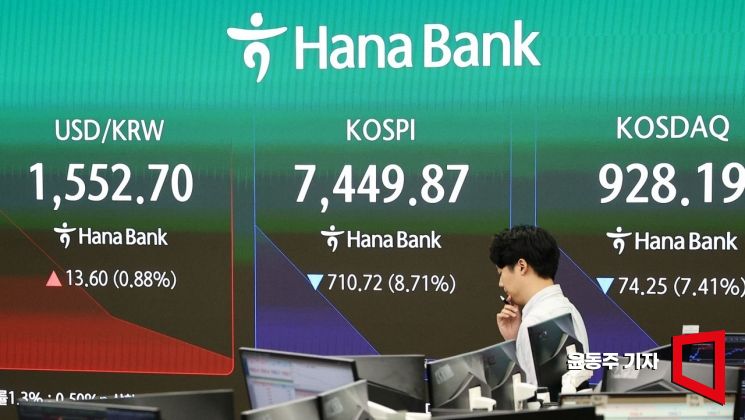
KOSPI Weighed Down by High Interest Rate Fears
네이버뉴스 · 2026.06.08
📰 View original
[Exclusive] Boston Dynamics Finds Korean Parts Suppliers... Gears Up for Humanoid Mass Production
네이버뉴스 · 2026.06.08
📰 View original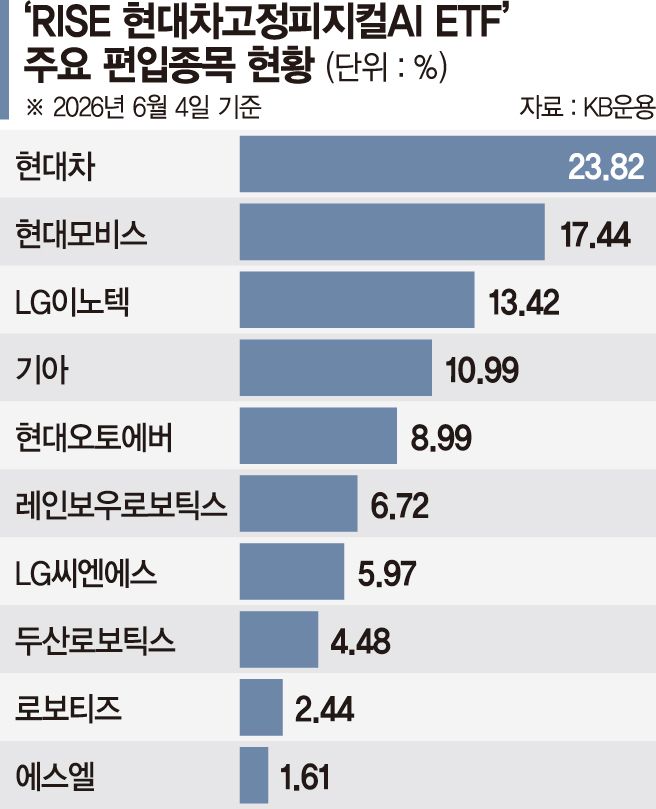
Adding Robotics Growth to Core Auto Competitiveness... [How About This Fund?]
네이버뉴스 · 2026.06.07
📰 View original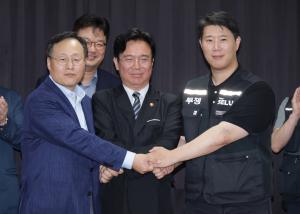
[Feature] Performance Bonus Controversy Spreading... Labor Conflicts, Shareholder Intervention, and Legal Battles
네이버뉴스 · 2026.06.07
📰 View original
[Weekly Picks by the Top 1% Super Investors]
네이버뉴스 · 2026.06.07
📰 View original
'Get In Now to Make Money'... The Stock the Rich Swept Up for Over 80 Billion Won
네이버뉴스 · 2026.06.07
📰 View original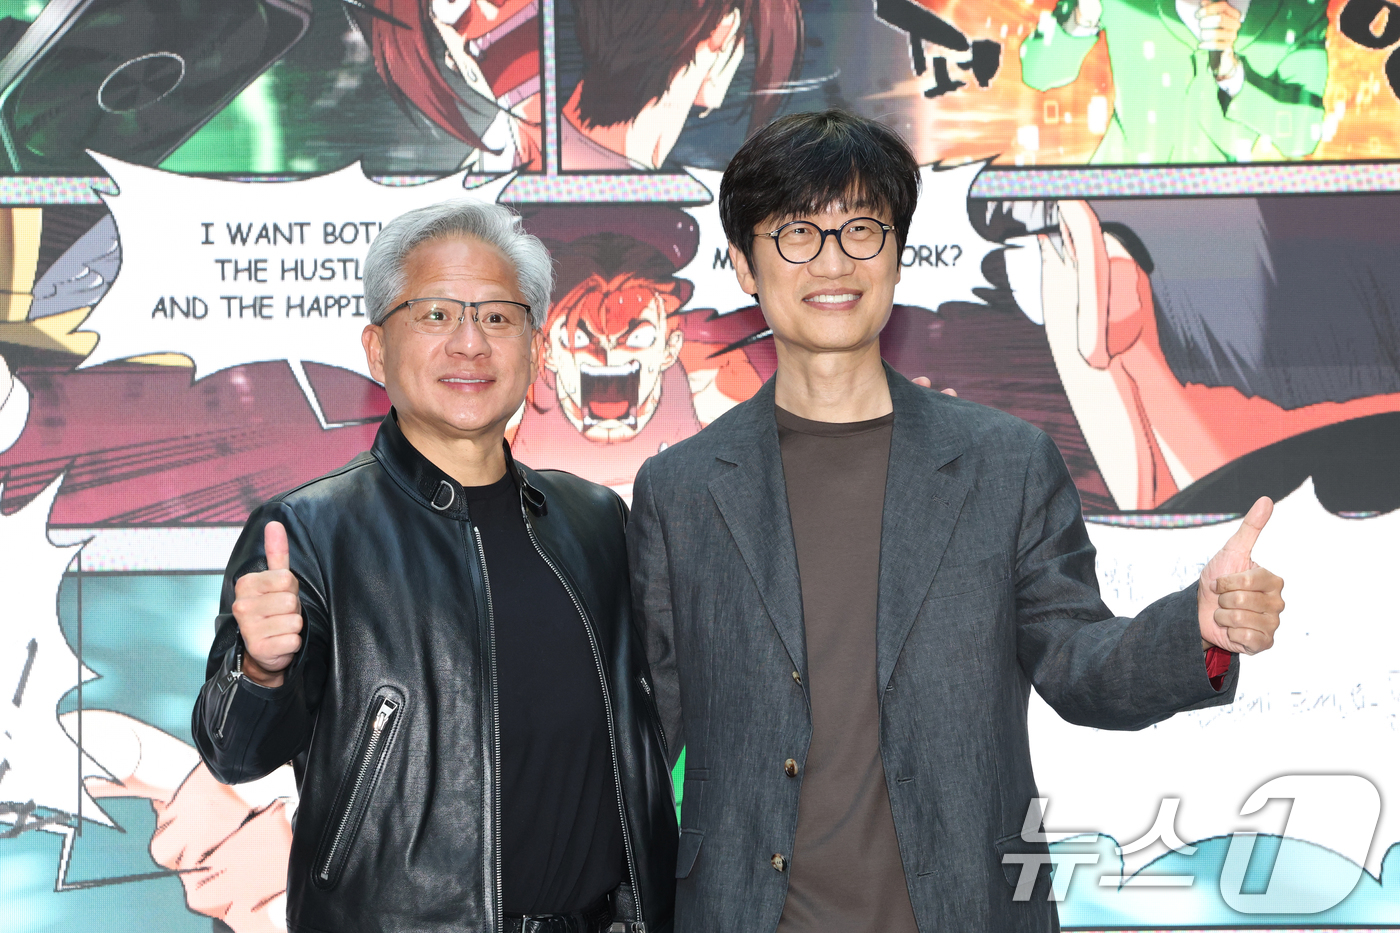
Naver Smiles with 'Nvidia Alliance'... Surges 9% on AI Factory Push [Hot Stock] (Update)
네이버뉴스 · 2026.06.08
📰 View originalBoston Dynamics Atlas and Figure AI's Figure 03 Simultaneously Enter Mass Production - Global Economic
네이버뉴스 · 2026.06.08
📰 View original
SK in the Morning, Samsung in the Evening... Why Jensen Huang's 'Crazy Schedule' of 5 Meetings a Day?
네이버뉴스 · 2026.06.08
📰 View original
Comments 0
to comment Login