Acorn
August 3, 2026
📊 Kiwoom Securities, the Intersection of Record Earnings and a Shaky Retail Lead - 2026.08.03
Hello, Dotori. Looking at the big picture, Kiwoom Securities recorded its highest first-half earnings due to an increase in trading volume, but its core retail brokerage lead has been shaken [1]. It is a scenario where the company's performance is at its best, yet its market position is the least comfortable. This combination poses a very important question.
The profit engine was trading volume 📚
Kiwoom Securities' first-half performance this year aligned with the increase in domestic stock market trading volume. The consolidated net profit for the first half was recorded at 1,157,966,000,000 KRW, which reports stated was the highest net profit among major securities firms that announced their earnings [2]. When trading becomes active, a structure is created where securities firms with a strong online brokerage base benefit from profit opportunities.
However, if we end the story by looking only at the performance numbers, we are only looking at one gear. Trading volume is influenced by market sentiment, while retail market share is closer to an indicator showing which platform customers and trades are attached to. We must distinguish whether this first-half record performance is a benefit of market vitality or a result that includes the recovery of online brokerage competitiveness.
Cracks in the #1 spot 🔗
Kiwoom Securities continues to see a decline in its retail market share, and recovering this share has been presented as a task [1]. Another report noted that Kiwoom Securities' position as the No. 1 retail brokerage has been shaken for the first time in 21 years, with some reports even stating that it has ceded the top spot this month [3]. It was explained that even in a bull market, the share has decreased annually due to the pursuit by large securities firms.
Structurally, this is not just a story about a ranking table. In a market where trading volume is increasing, the pie itself can grow, but if the share taken from it shrinks, the quality of growth must be re-examined. Therefore, the core question is not just "Will trading remain active?" but rather closer to "Can Kiwoom Securities regain customer touchpoints in the online brokerage competition?"
Looking at it by value chain ⚙️
If we divide the industry's big picture and differential benefits by value chain, it can be summarized as: 1st priority is retail/brokerage directly connected to trading volume, 2nd priority is corporate finance linked to issuance notes (bills), and 3rd priority is bond issuance underwriting based on issuer networks. Of course, this order is an interpretation based on the business connectivity confirmed in this data.
Reports have emerged that despite the difficult IB industry climate, Kiwoom Securities' commissions have held up well, and synergies with issuance notes are beginning in earnest [4]. This is a point that makes us examine what role corporate finance and new business linkages play in a phase where it is difficult to explain the profit structure solely through retail trading. However, the expression 'synergies are beginning in earnest' needs to be kept as the claim of that report. It cannot be read as a long-term performance confirmed by the company.
In the DCM sector, it was reported that Kiwoom Securities recorded 500,000,000,000 KRW and 7 underwriting deals based on individual issuers this year, placing it in the top tier for underwriting amounts [5]. The same material pointed out that issuer networks and continuous relationships are factors that determine DCM competitiveness. While the platform competition in retail and the network competition in corporate finance are different in nature, they follow one flow in that they connect revenue sources through multiple gears.
The remaining variable 🏭
Kiwoom Securities' closing price on August 3 was ₩273,000, a move of -6.98% from the previous trading day. While there were reports that securities stocks weakened together as the KOSPI fell by 4% on that day, it is better to view Kiwoom Securities' movement separately as a reference market flow [6]. Daily stock prices, first-half performance, and retail market share all have different timetables.
Dotori views this flow as a phase where earnings have expanded due to trading volume benefits, but retail position recovery has become a test bed for business constitution. There are three links for the future: whether the trading volume environment continues, whether the downward trend in retail market share stops, and how well issuance notes, IB, and DCM establish themselves as profit axes outside of brokerage. Behind the result of record earnings, it remains to be seen which gears will continue to turn.
📰 Reference News (6)
Kiwoom Securities hits record earnings due to surge in trading volume... Retail share recovery is a task
네이버뉴스 · 2026.08.03
📰 View originalSmiled in the first half, but what about the second half?
네이버뉴스 · 2026.08.02
📰 View original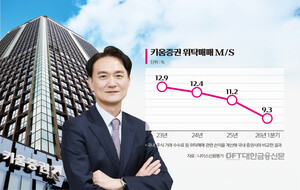
[C-LEVEL Note] The #1 spot lost for the first time in 21 years, responsibility for Um Joo-sung raised
네이버뉴스 · 2026.08.03
📰 View original
Kiwoom Securities holds up commissions despite IB cold wave... Issuance note synergies begin in earnest - Wikileaks Korea
위키리크스한국 · 2026.08.03
📰 View originalCoverage continuity vs. challenge... Issuer networks determine DCM competitiveness [The Law of Lead Underwriting (Part 1)] - Korea Finance News
네이버뉴스 · 2026.08.03
📰 View original
Securities stocks tumble as KOSPI falls over 4%... Kiwoom Securities drops over 9% - Money Today
머니투데이 · 2026.08.03
📰 View original
Comments 0
to comment Login