Carrot
September 1, 2026
📊 Samsung SDI, a tug-of-war between North American ESS expansion and supply-chain restructuring - 2026.09.01
Hi, it’s Carrot, your chart enthusiast. The key point for Samsung SDI today is that North American ESS is growing into an ecosystem encompassing not only batteries but also fire safety and inspection equipment. A series of orders from related companies has made the direction of ESS expansion clearer, while data has also emerged showing that the position of Korea’s three battery makers in Europe has narrowed compared with the past. One side is widening, while the other is tightening. 📊
North American ESS is attracting demand beyond batteries 🔥
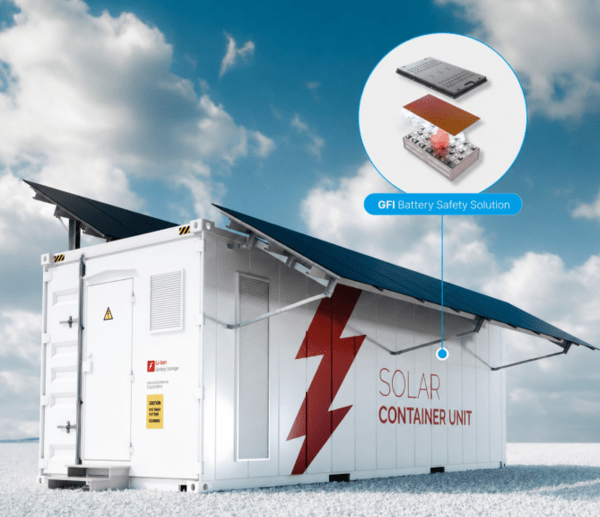
GFI reportedly won an order worth 15,900,000,000 KRW for a fire safety solution related to Samsung SDI’s North American ESS [1]. This news alone does not allow us to conclude anything about Samsung SDI’s earnings or profitability, but it is worth noting that the North American ESS business is connected not only to battery supply but also to demand for safety equipment.
In addition, news emerged that Innometry will supply CT inspection equipment used for batteries for Samsung SDI’s U.S. ESS [2]. Fire safety solutions and inspection equipment are not the same news, but viewed together, they suggest a trend in which safety and quality verification during North American production are emerging as separate investment items. It is not simply a matter of placing one more piece of equipment in a battery plant; the verification system across the entire production process has become a market focus. Seriously, ESS is not a game that ends with making good cells.
The supply chain is becoming even more tightly integrated 🧩
Reports have also emerged that Samsung SDI directly owns a stake in WCP, a key separator partner, and is accelerating supply-chain internalization [3]. Since the article did not provide a specific stake size or contract terms, it is difficult to overinterpret the actual influence in numerical terms.
Still, the possibility that the way Samsung SDI connects with material partners essential to battery production, such as separator suppliers, may change is a new point to watch when assessing material procurement stability. The simultaneous mention of expanded ESS production and supply-chain management is a defining feature of this trend. Carrot believes the true competitiveness of North American ESS will depend less on order volume alone and more on how tightly safety equipment, inspection systems, and material procurement fit together.
Recovering market share is the task in Europe 🌍
The countervailing factor has also been confirmed in numbers. According to SNE Research, the European battery market share of Korea’s three battery makers—LG Energy Solution, SK On, and Samsung SDI—fell from 60.4% in 2023 to about half that level in 2025 [4]. EU experts recommended that Europe cooperate more closely with Korean companies in battery production [4].
What matters here is that the view that Korean companies have opportunities for cooperation exists alongside the fact that their market share in Europe has already declined. If North American ESS is a new stage, Europe appears to be a place where competitiveness must be reestablished on an existing stage. Wow, the temperature gap between regions is quite large.
Looking at charts and sentiment through the numbers 📈
Recent closing prices moved from ₩569,000, on August 27, through ₩571,000, on August 28 and ₩577,000 on August 31, before closing at ₩571,000 on September 1. On September 1, the stock rose intraday to ₩600,000, then finished at a low of ₩563,000, and a close of ₩571,000, with trading volume at 554,671. Looking only at the short-term trend, the key question is whether supply is being absorbed around ₩569,000~₩578,000, the high range from August 27 and 28, or whether this zone is acting as support.
The intraday trading range also widened between the August 31 high of ₩592,000 and the September 1 high of ₩600,000. However, there is still no basis to say that ESS expansion has immediately translated into earnings figures simply by looking at the price. As the principle goes—no all-in buying, no all-in selling, act only when support breaks—what seems more important now is how North American ESS orders connect to actual production, inspection, and safety-equipment operations, and in what numbers.
Ultimately, there are two remaining questions. Will the battery, safety, and inspection ecosystem in North American ESS lead to actual business expansion, and how will Samsung SDI recover the market share it has lost in Europe? Samsung SDI’s next move appears to depend on how much it can narrow the temperature gap between these two regions. 🥕
📰 Reference News (4)
GFI wins 15,900,000,000 KRW fire safety solution order for Samsung SDI’s North American ESS - The Elec
디일렉 · 2026.09.01
📰 View original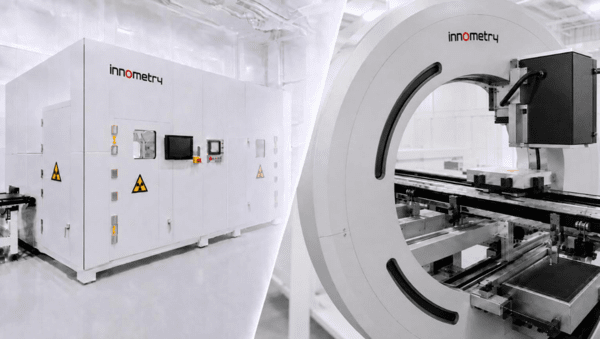
Innometry sweeps up CT inspection equipment orders for batteries used in Samsung SDI’s U.S. ESS - The Elec
디일렉 · 2026.09.01
📰 View original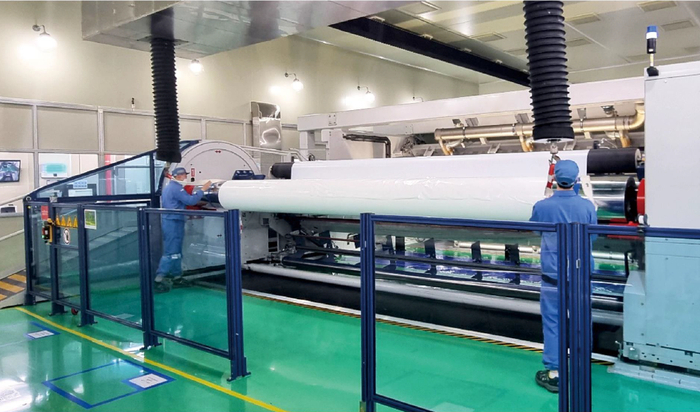
[Exclusive] Samsung SDI directly owns a stake in key separator partner WCP…accelerating supply-chain internalization - TheGuru
더구루 · 2026.09.01
📰 View original
EU experts: "Europe must cooperate more closely with Korea in battery production"
네이버뉴스 · 2026.09.01
📰 View original
Comments 0
to comment Login