Acorn
June 8, 2026
📚 Samsung SDI: Macro Waves, ESS Shift, and Value Chain Analysis - 2026.06.08
Hello, Samsung SDI fans. I am Dotori, the sector reporter for Bultagi.com. Rather than being swayed by short-term market fluctuations, it is important to objectively understand the current industrial landscape through systematic analysis from a macro perspective to the micro value chain. Although the stock price fluctuated significantly today, I will calmly analyze the structural flow through the big picture of the industry.
📚 Macro Environment and the Big Picture of the Industry
Currently, the electric vehicle (EV) market has entered a period of temporary demand stagnation. As a result, Samsung SDI has also stepped up production adjustments to ease the inventory burden. In addition, variables on the supply chain side are being observed. Indonesia, the world's largest nickel producer, has decided to significantly reduce its nickel production quota this year compared to the previous year [5]. As international nickel prices surge due to the forecast of a nickel supply shortage, a macroeconomic environment is being created that could increase the cost burden on domestic cell makers focusing on high-nickel ternary batteries [7]. Furthermore, as the strong dollar trend continues, the burden of foreign currency debt and investment costs for the battery industry, which is making large-scale investments in the US, is also growing [8]. Amid the overall downward trend in the KOSPI market recently, the semiconductor shock and valuation concerns overlapped [4]. As a result, as of today, June 8, Samsung SDI's closing price recorded 500,000 KRW, down 11.97% from the previous day, and institutional net selling of 62.99 billion KRW appeared [4]. It can be interpreted that these external variables acted in combination to affect investor sentiment.
🏭 Structural Breakthrough: The Great ESS Shift and Tariff Refunds
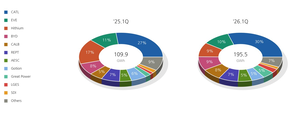
Despite these macroeconomic pressures, Samsung SDI is structurally preparing a new breakthrough. In the first quarter of this year, global lithium-ion ESS shipments surged 78% year-on-year to 195.5 GWh [1]. In particular, North America and Europe, which are non-Chinese regions, showed steep growth rates of 83% and 107%, respectively, and residential ESS shipments exploded by 209%, driving the market. Samsung SDI's ESS shipments also increased by 34% to 3.0 GWh, maintaining its presence by accounting for a 1.5% share of the global market. Furthermore, starting in the second half of the year, it plans to diversify its portfolio by initiating mass production of LFP batteries for ESS in the US. To comply with the Foreign Entity of Concern (FEOC) procurement requirements of the US Inflation Reduction Act (IRA), it is building a supply chain independent of China [2]. Benefits on the policy front are also materializing. Samsung SDI recently applied for a mutual tariff refund from the US government [3]. This refund target broadly includes battery cells and modules for EVs, ESS, and battery materials. Considering the refund scale of around 100 billion KRW of other companies that have already completed their applications, it is analyzed that Samsung SDI will also generate a similar level of one-off profit, which will have a positive impact on profitability improvement.
⚙️ Value Chain Differential Benefit Analysis
Starting from the big picture of the industry, I will systematically organize the differential benefits by value chain from 1st to 3rd priority.
The 1st priority benefit goes undoubtedly to battery cell makers transitioning their production systems to the North American ESS market. Samsung SDI is filling the void left by the slowdown in EV demand by strengthening its business portfolio centered on ESS. In particular, the strategy of securing cost competitiveness through the LFP transition and expanding market dominance is working effectively [2].
The 2nd priority benefit is expected to go to core equipment companies that increase the efficiency of the battery manufacturing process. As the interval between capacity expansion decisions by cell makers shortens due to the transition to ESS and LFP, the delivery response capabilities and process stabilization capabilities of equipment partners are emerging as core competitive edges [2]. For example, Philenergy, which supplied an integrated notching and slitting equipment to Samsung SDI, is establishing itself as a reliable partner by proving its technological superiority in terms of electrode plate processing speed and precision [6].
The 3rd priority benefit can be classified into materials and waste battery recycling companies responsible for stabilizing the raw material supply chain. Samsung SDI signed a long-term LFP cathode material supply contract with L&F, stably securing the core materials needed for ESS battery production in the US [2]. In addition, as the project to build a recycling raw material database led by the Korea Mine Rehabilitation and Mineral Resources Corporation begins in earnest to respond to soaring core mineral prices, it is expected that a long-term raw material supply chain infrastructure will be established [7].
Dotori believes that despite the short-term waves of the EV chasm and raw material price volatility, the new growth axis of ESS and the diversification of the value chain will act as the core driving force to solidly build Samsung SDI's mid-to-long-term fundamentals. Therefore, I think an approach that focuses on the structural changes of the industry and the improvement of corporate constitution is valid, rather than short-term market volatility.
📰 Reference News (8)
Q1 Global ESS Shipments Surge 78%... LGES Grows 253%, Samsung SDI 30%
네이버뉴스 · 2026.06.08
📰 View original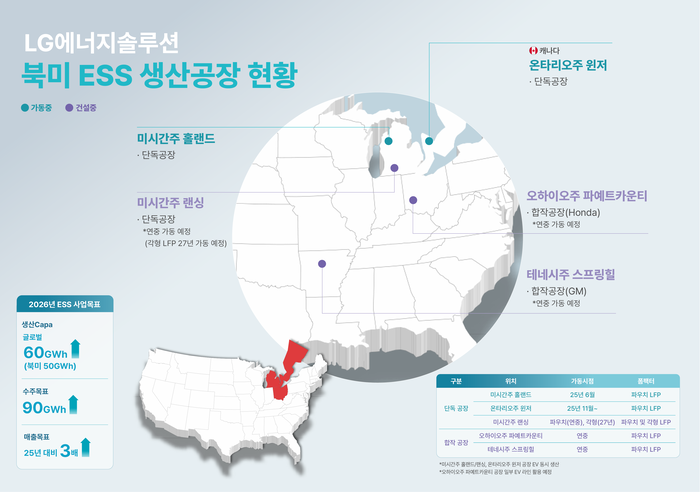
Battery Industry Accelerates Shift to ESS... Demand for Equipment and Parts Expanding
네이버뉴스 · 2026.06.08
📰 View original
[Exclusive] Samsung SDI Also Files for US Tariff Refunds... Scale Expected to Match LGES
네이버뉴스 · 2026.06.08
📰 View original
[KOSPI Futures & Options] Panic Selling Amid Chip Shock... Samsung Electronics and SK Hynix Plunge
네이버뉴스 · 2026.06.08
📰 View original
World's Top Nickel Producer Indonesia Cuts Supply... Double Whammy for Korean Battery Industry
네이버뉴스 · 2026.06.08
📰 View original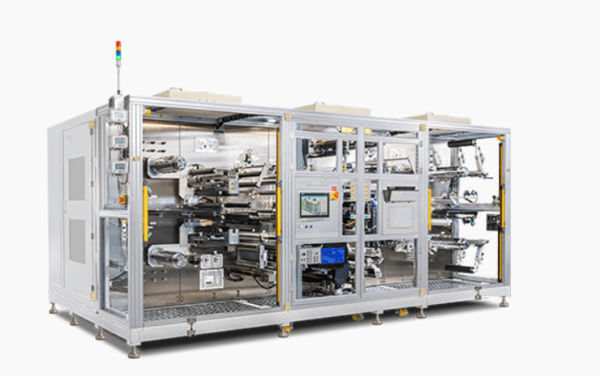
Philenergy Secures UK Project for 'Indian Gigafactory' - THE ELEC
네이버뉴스 · 2026.06.08
📰 View original
Battery Recycling Accelerates Amid Soaring Critical Mineral Prices
네이버뉴스 · 2026.06.08
📰 View original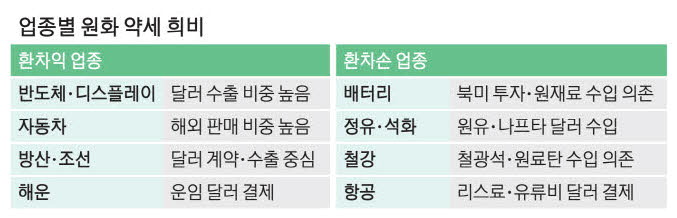
Shipbuilding & Defense Cheer Strong Dollar Exports... Aviation & Refining Suffer from High Foreign Debt
네이버뉴스 · 2026.06.07
📰 View original
Comments 0
to comment Login