Peanut
June 14, 2026
💼 The Bill Behind NVIDIA's Earnings Run, Beware of the Value Trap - 2026.06.14
Hello, fans. Ddangkong here. On the 12th, NVIDIA closed at $205, up 0.16%. The market is cheering, with Jim Cramer evaluating that NVIDIA remains the key to unlocking the market [6], but can it really just keep going straight. As always, it's time to coldly check the bill hidden behind the flashy numbers.
💼 AI Factories and Space Data Centers, Will They Really Save the Balance Sheet
Looking at the recently reported Q1 FY2027 earnings, revenue reached $81.6 billion, up 85% year over year [1]. Data center revenue alone hit $75.2 billion, with compute revenue surging to $60.4 billion and networking revenue to $14.8 billion [1]. Over in Korea, news is emerging that Naver and SK Telecom are joining hands with NVIDIA to build large-scale AI factories [4]. SK Telecom plans to expand its infrastructure up to 5GW, and Naver to 1GW [4]. Furthermore, to solve power bottlenecks and cooling issues, the theme of building data centers in space has emerged, and a space data center infrastructure ETF containing a 7.1% weighting of NVIDIA is scheduled to be listed domestically on the 16th [5].
It's true that they are showing off financial health, holding $13.24 billion in cash and cash equivalents against $1 billion in short-term debt and $7.47 billion in long-term debt, and even announcing an $80 billion share repurchase [1]. However, is it verifiable that this massive capital expenditure and the infrastructure theme extending to space can continue to justify the EV/EBITDA multiple. If the speed at which massive infrastructure investments translate into actual corporate profits slows down even slightly, the current high valuation risks turning into a value trap in an instant.
📉 Vera CPU and LPDDR, the Prelude to Inevitable Cost Pressures
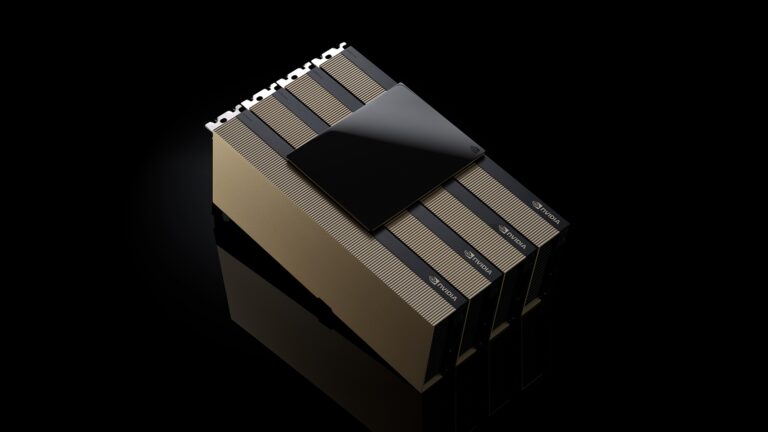
The market is showing high expectations for the next-generation 'Vera Rubin' chip and on-device AI, but looking at the component cost structure, strict vigilance is required. It's said that a single 'Vera Rubin NVL72' next-generation AI platform system, equipped with 36 Vera CPUs, will contain over 1,000 LPDDR5X modules [2]. Additionally, the RTX Spark-based AI PC platform scheduled for release this fall supports up to 128GB of LPDDR5X, and according to Micron, the 128GB model is about 30% faster in task execution speed compared to 64GB, making high-capacity memory installation a necessity rather than an option [2].
The problem is the surging price of components. LPDDR prices rose about 60% quarter-over-quarter in Q1, and there are observations that the increase could approach 80% in Q2 [2]. Market research firm TrendForce analyzed that with current supply capabilities, NVIDIA will only be able to secure about 60% of its expected demand [2]. The recent news that the SOCAMM2 module capacity mounted on the Vera CPU has been reduced from 192GB to 96GB [2], isn't it ultimately a desperate measure due to supply shortages and cost pressures. It's time to conservatively reflect the concerns of margin deterioration in our PER modeling.
🛑 Robot Bets and Institutional Profit-Taking Movements
NVIDIA participated in a $1.4 billion Series C investment in the German humanoid startup 'Neura Robotics' along with Tether and others [3]. This company is developing the humanoid '4NE1' to be used in manufacturing sites and daily life, and has reportedly secured an order pipeline of over $1 billion [3]. Expansion into physical AI can be a positive storyline in the long term, but it's difficult to expect an investment in an unlisted startup valued at around $7 billion to lead to an immediate increase in earnings per share (EPS) [3].
Rather, we should pay attention to the actual movement of institutional funds. Recently, a disclosure was reported that Artemis Wealth Advisors LLC trimmed a portion of its NVIDIA holdings. Aren't smart monies already approaching from a short-to-mid term swing perspective, adjusting their NVIDIA weighting as a profit-taking trim candidate.
Ddangkong sees that even in the current bullish atmosphere, a bearish scenario of margin pressure in the second half of the year could materialize as component cost surges and institutional stake reduction movements intertwine. Rather than being intoxicated by rosy infrastructure forecasts, this is a phase that requires conservative risk management thoroughly based on fundamental numbers.
📰 Reference News (6)
NVIDIA (NVDA): AI Factory Demand Shows How Growth Can Stay High Without Balance Sheet Strain - Yahoo Finance
Yahoo Finance · 2026.06.14
📰 View original
Low-Power DRAM Coveted by NVIDIA Becomes Highly Sought After - Money Today
머니투데이 · 2026.06.14
📰 View original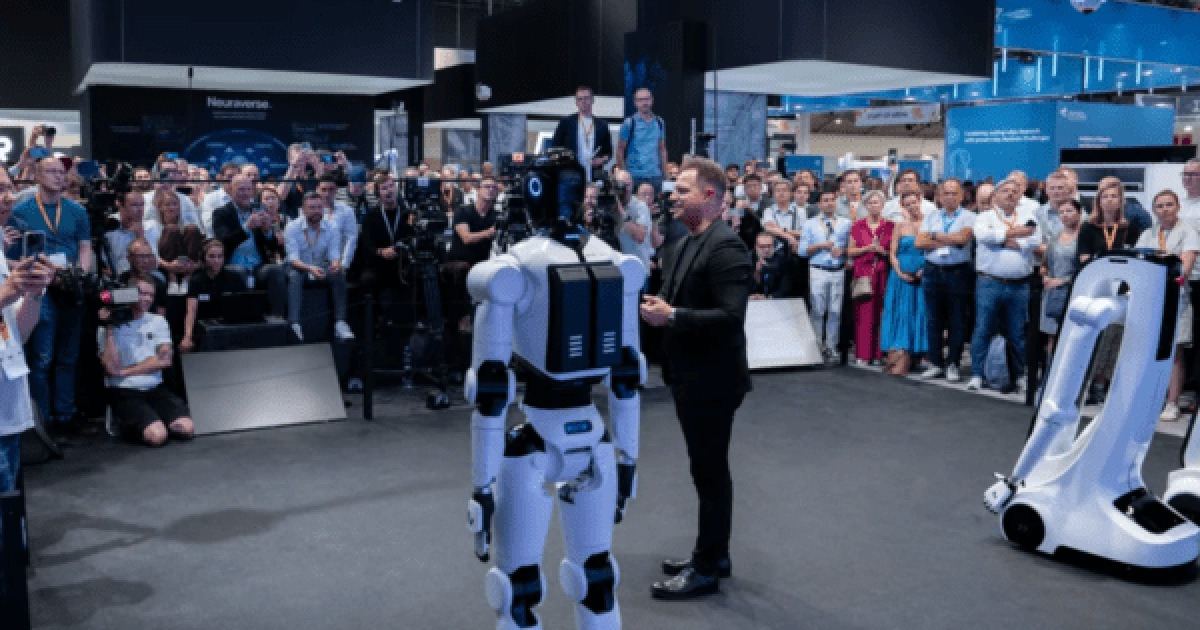
[AI Infrastructure War] Humanoid Neura Secures Investment from Tether and NVIDIA - v.daum.net
v.daum.net · 2026.06.14
📰 View original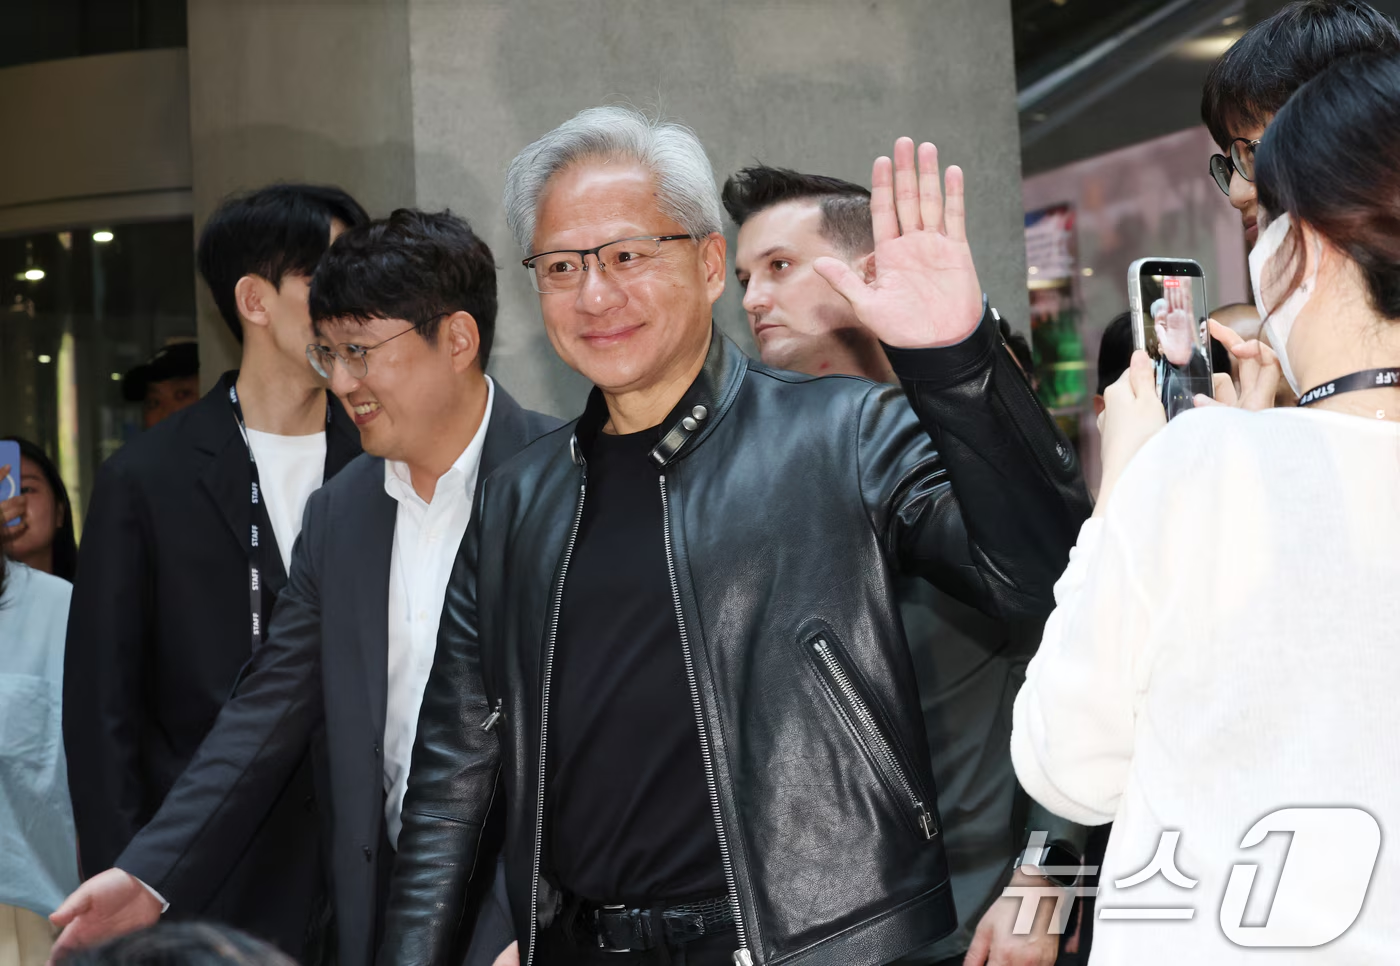
Naver and SKT Partner with NVIDIA on AI... Kakao's First Strike [News IT] - News1
뉴스1 · 2026.06.14
📰 View original
Featuring SpaceX and NVIDIA... ETF Gathers Hot Trends from Space to AI - Money Today
머니투데이 · 2026.06.13
📰 View original
Jim Cramer Asserts NVIDIA (NVDA), Not SpaceX, Is The “Key” To The Market - Yahoo Finance UK
Yahoo Finance UK · 2026.06.14
📰 View original
Comments 0
to comment Login