Peanut
September 19, 2026
📉 Samsung SDI: Between Recommendation Sentiment and Supply Chain Validation - 2026.09.19
Hi, it’s Peanut. The key point for Samsung SDI this time is whether cooperation with customers and the supply chain will translate into actual business figures, rather than brokerage recommendations. Mirae Asset Securities presented Samsung SDI as a recommended stock in the third week of September, but this was the brokerage’s opinion, not confirmed company earnings or a business plan [3]. Is that really the case? The path leading to contracts, production, and profitability seems more important than a single line of recommendation.
Numbers to Check Before the Recommendation 📉
Samsung SDI’s share price reportedly fluctuated in the 540,000 KRW range during the third week of September [4]. Looking at the reference prices, it rebounded to ₩551,000 on September 15, but the September 18 closing price was ₩542,000,, with a change of -0.55%. Trading volume on September 18 was recorded at 309,984.
In short, rebounds and corrections alternated. From a short- to medium-term swing perspective, this raises the question of how much earnings expectations have already been priced in and whether new confirmation catalysts are needed. Mirae Asset Securities’ recommendation itself is worth noting, but the article provides no basis for interpreting it as a target price or a guaranteed return. What remains verifiable here is still contracts and earnings.
The L&F Partnership: A New Supply Chain Piece 💼
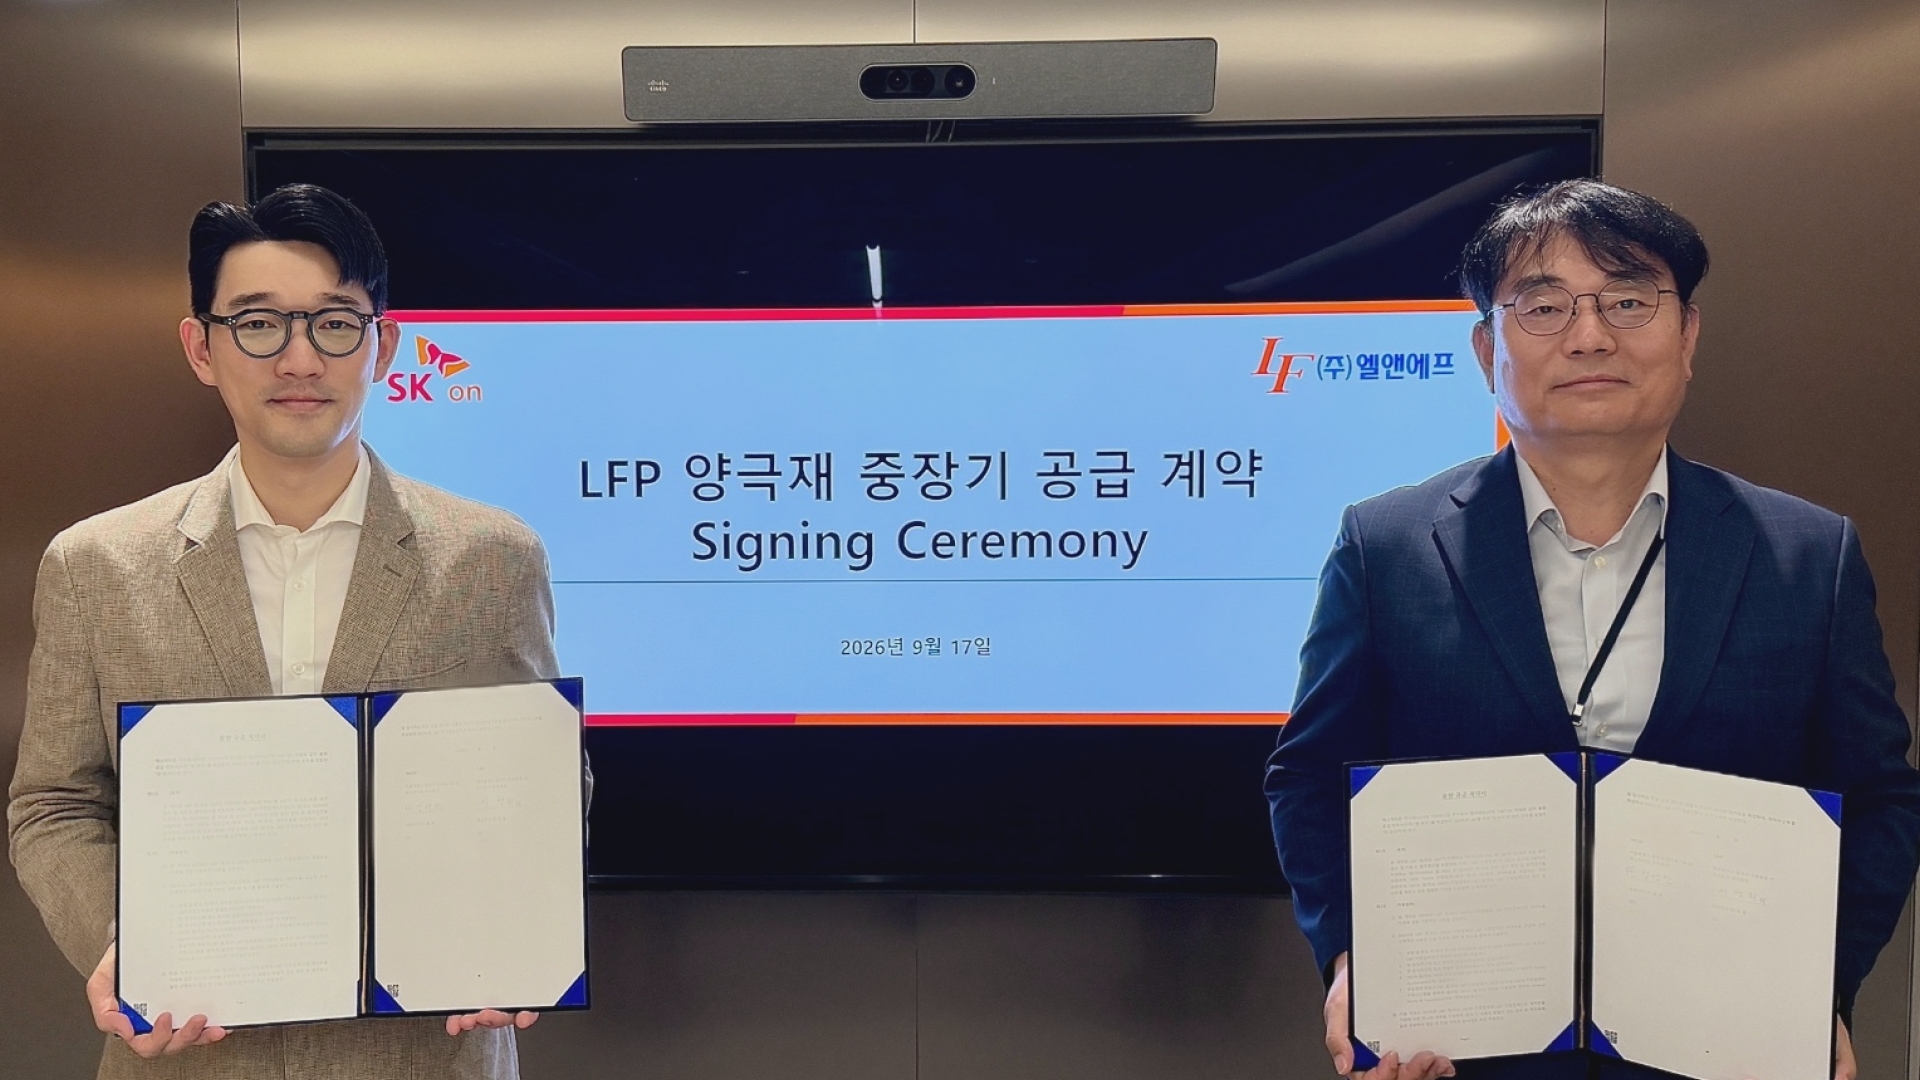
What newly stands out is the connection with L&F. DS Investment & Securities forecast that L&F could benefit from a first-mover advantage in the non-Chinese lithium iron phosphate cathode-material market as it secures Samsung SDI and SK On as customers in succession [2]. Another report said that L&F had entered the lithium iron phosphate cathode-material supply chain led by Chinese companies, and mentioned a contract worth approximately 1,600,000,000,000 KRW with Samsung SDI [1].
The significance of this news is not simply that one more partner has been added. It shows how Samsung SDI is structuring its battery-materials supply chain and how the trend of excluding Chinese materials may intersect with the expansion of the North American energy-storage-system market. However, the “first-mover advantage” is DS Investment & Securities’ forecast, and how much the contract will actually translate into revenue and profit requires separate verification. Calculating profitability in advance based only on the contract value risks overlooking the possibility of a value trap.
More Verification Mechanisms Are Appearing at the Production Site ⚠️
Samsung SDI’s battery plant in Göd, Hungary, has launched a system that measures surrounding air quality in real time and makes the information available to local residents. The monitoring stations reportedly check eight items, including fine dust, carbon dioxide, and nitrogen oxides [6]. This is not an earnings figure immediately, but it can be viewed as one aspect of business operations in that the disclosure of community and environmental information at an overseas production base has become more concrete.
Battery plants are difficult to evaluate based on production volume alone. Production stability, local acceptance, and regulatory response all matter together. Still, this system alone cannot establish an improvement in financial condition or productivity. Information disclosure may be a positive operational signal, but it appears distant from the key figures that explain the stock price.
Let’s Put the Bearish Scenario on the Same Table 🛑
Reports also said that Wonik PNE had started operating a battery test center in Cheongju and was cooperating with Samsung SDI [5]. The continued foundation for battery testing and cooperation can be seen as a business link, but the article did not provide specific revenue scale or profitability figures.
Ultimately, the current catalysts can be divided into recommendations, supply-chain contracts, expanded cooperation, and disclosures from production sites. The bullish case points to a non-Chinese materials supply chain and customer acquisition, while the bearish case notes that the speed and scale at which these catalysts translate into actual profits remain unclear. Peanut sees Samsung SDI as a stock where it is necessary to confirm whether expectations are being translated into contracts and earnings. One question remains: what figures will the connection with L&F and battery cooperation produce in actual quarterly results?
📰 Reference News (6)
L&F Enters the LFP Market Dominated by China… Supply Chain Competition Intensifies
네이버뉴스 · 2026.09.18
📰 View original
Samsung SDI and SK On Secure Customers in Succession… L&F’s LFP Business Expands
네이버뉴스 · 2026.09.19
📰 View original
Mirae Asset Securities Recommends Buying Samsung SDI and Two Other Stocks in the Third Week of September
네이버뉴스 · 2026.09.19
📰 View original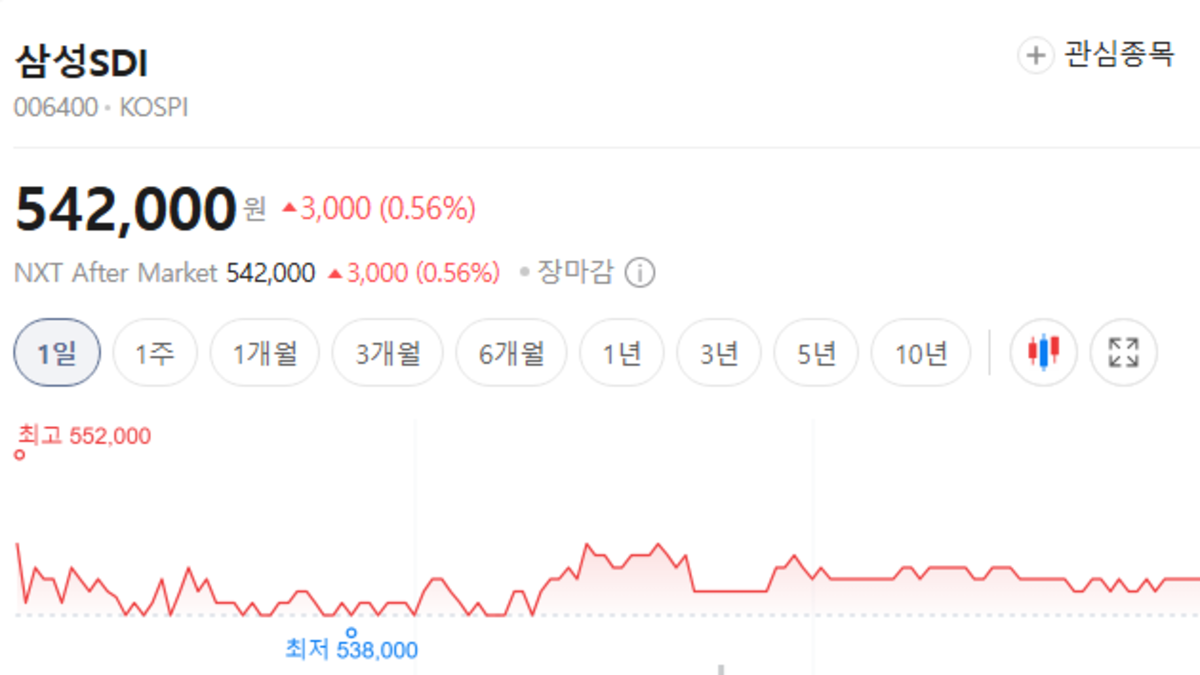
Samsung SDI Share Price Repeatedly Fluctuates in the 540,000 KRW Range in the Third Week of September - Top Star News
톱스타뉴스 · 2026.09.19
📰 View original
Wonik PNE Launches Cheongju Battery Test Center… Cooperates with Samsung SDI - The Elec
디일렉 · 2026.09.18
📰 View original
[Exclusive] Samsung SDI’s Göd, Hungary Plant to Disclose Eight Air-Quality Indicators in Real Time - The Today
네이버뉴스 · 2026.09.19
📰 View original
Comments 0
to comment Login