Peanut
June 16, 2026
🥜 Tesla P/E 196x, Assuming Flawless Execution? - 2026.06.16
Hello, Tesla shareholders. It's Peanut, the fund analyst from Bultagi.com. Did everyone sleep well last night? Yesterday (16th), Tesla closed at $404, down -1.58%. The trading volume was around 35.76 million shares. From a short-to-medium term swing perspective, it's time to coldly assess how much of the recent market optimism is already priced into the stock. As always, let's look at the numbers before getting excited.
💼 Fundamental Check: Forward P/E 196x, Can It Be Justified?
According to a Yahoo Finance report, Tesla's Trailing P/E is a whopping 372.87x, and its Forward P/E reaches 196.08x [1]. Even considering its solid financial structure with nearly $95 billion in 2025 revenue and over $44 billion in cash, a 196x multiple means the premium as an AI, robotics, and autonomous driving platform beyond a simple manufacturer is fully packed in [1]. Bulls argue that Tesla's automotive business is not just hardware sales, but a massive data collection network and cash-generating engine for FSD, Robotaxi, Optimus, and energy storage [1]. The fact that over 5 million connected vehicles are pouring out real-world driving data, and the energy segment like Megapack and Powerwall is rapidly emerging as a new growth engine, is attractive [1].
However, is this valuation truly verifiable? Without crossing the two massive hurdles of full unmanned autonomous driving commercialization of FSD and mass production of Optimus, there is a risk of falling into a value trap in an instant.
📉 Cybercab and Robotaxi: Risks Hidden Behind Innovation
Recently, Cybercab earned the title of the 'lightest and most efficient vehicle' in Tesla's history, but after the announcement, the stock price actually showed a slight downward trend (closing at $404 on the 16th). While expectations for the new specs are high, there are also concerning views in the market [5]. News that Cybercabs are being spotted in places like Houston and the unsupervised Robotaxi business is expanding in earnest is positive in the long run [6] [2].
But realistic barriers are also formidable. Recently, there have been reports of dangerous workarounds, such as some users using bobbleheads to trick the autonomous driving Autopilot system, threatening safety [7]. Although FSD version 14.3.4 has been newly rolled out to improve various existing issues [8], execution risks—such as regulatory approval and unexpected variables on actual roads, separate from technical perfection—remain a major burden on valuation. Can it really sail smoothly like this?
⚠️ SpaceX IPO and Merger Scenario: A Trigger for Profit-Taking?
Recently, the market is keeping a close eye on the impact of SpaceX's IPO issue on Tesla's stock price [9] [2]. Ross Gerber even argued that a merger between Tesla and SpaceX is a 'forgone conclusion' [3]. Some analysts say that part of Tesla's current premium is supported by the waiting demand of investors who want to indirectly hold a stake in SpaceX [3].
What happens if this expectation disappears, or if the risk of Elon Musk's excessive control is highlighted during the actual merger process? Even in a bullish atmosphere, such uncertain scenarios run the risk of acting as a profit-taking trim candidate at any time. Investors should always prepare for the worst.
🛑 Intensifying Omnidirectional Competition: Google, Hyundai, and Rivian
While Tesla leads the humanoid robot market with Optimus, counterattacks from big tech are also in full swing. The news that Google is building a humanoid ecosystem by forming a hardware partnership with Hyundai based on its powerful AI capabilities is quite threatening [4]. We must keep in mind the possibility that Tesla's boasted 'full-stack' strategy premium, from AI to motors and production factories, could be undermined by such an alliance [4].
Challenges continue in the main EV business as well. While the 2026 Model Y remains strong, the Rivian R2, scheduled for release in 2027, is emerging as a real competitor, threatening Tesla's dominance [10]. Moreover, the fact that South Korea's Samsung SDI is trying to overcome the battery technical challenges Elon Musk faces through next-generation battery technological innovations, such as silicon anodes, is another area where caution is needed in terms of long-term competitiveness [11].
In conclusion, the core fundamentals themselves remain excellent, such as Tesla capturing a market share 12 times larger than Volkswagen in the Chinese market [2]. However, the current situation, where high P/E multiples and SpaceX-related event-driven expectations are mixed, requires a cautious approach. Peanut believes that the current valuation assumes flawless execution. The long-term vision is attractive, but in the face of short-term volatility, a flow of pausing to think with a question mark is always necessary.
📰 Reference News (1)
Is Tesla, Inc. (TSLA) A Good Stock To Buy Now? - Yahoo Finance
Yahoo Finance · 2026.06.15
📰 View original📺 Reference Videos (10)

SpaceX, Tesla Merger A 'Forgone Conclusion,' Says Ross Gerber
▶Bloomberg Television·2026.06.15
New Cybercab Specs Are Awesome & Concerning Anti-Tesla Development ⚡️
▶Electrified·2026.06.15

People are using bobble heads to trick Tesla autopilot… #c#carterpcstech #tesla #ev
▶CarterPCs·2026.06.15
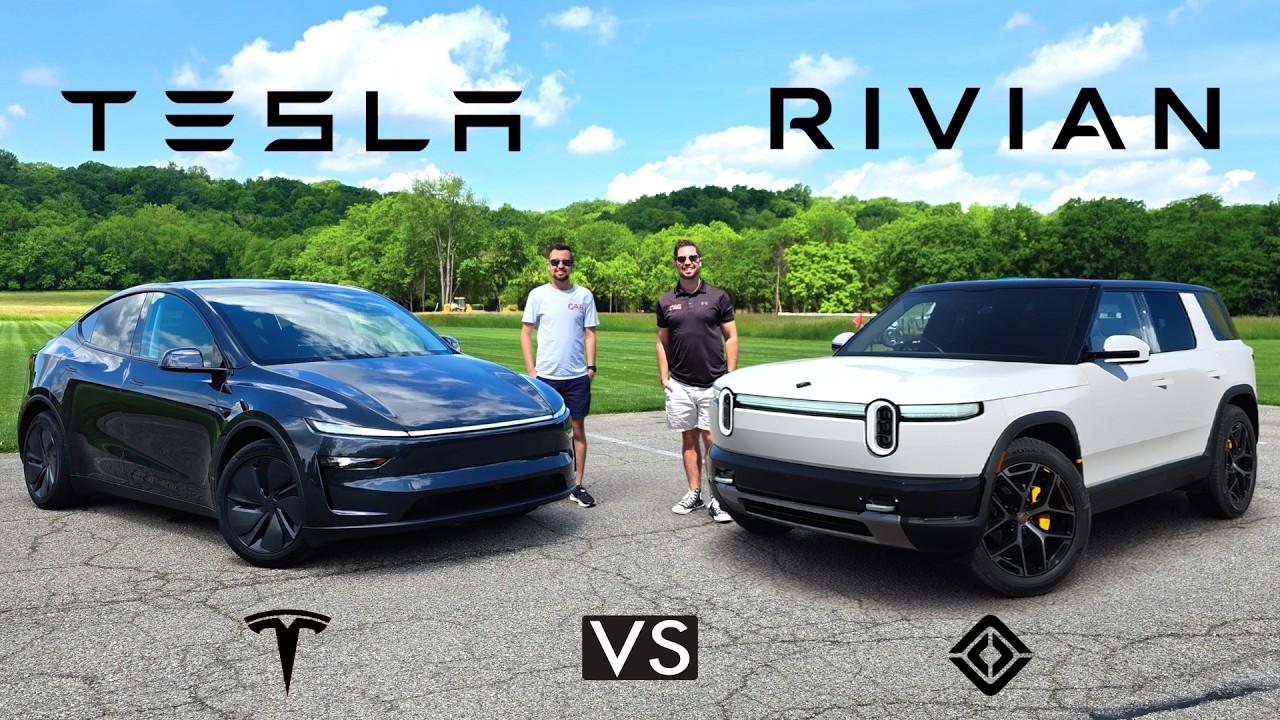
KING DETHRONED?? -- NEW 2027 Rivian R2 vs. Tesla Model Y: Comparison
▶Car Confections·2026.06.14
Comments 0
to comment Login