Goguma
June 22, 2026
🍠 Samsung Electro-Mechanics Breaks into Qualcomm's AI Servers! 4 Perspectives on the MLCC Boom ⚖️ - 2026.06.22
Hello, Bultagi.com fans! It's team leader reporter Sweet Potato. I've gathered all the major news to start the week after Monday's market close. Today, Samsung Electro-Mechanics' closing price was 2,228,000 won, taking a breather with a 1.85% adjustment from the previous trading day. However, beneath the surface, massive fundamental changes and fierce supply-demand battles are taking place. Let's dive right into the hot views brought by our 4 reporters!
🍠 Entering Qualcomm's Data Centers and the MLCC Super Cycle 🎯
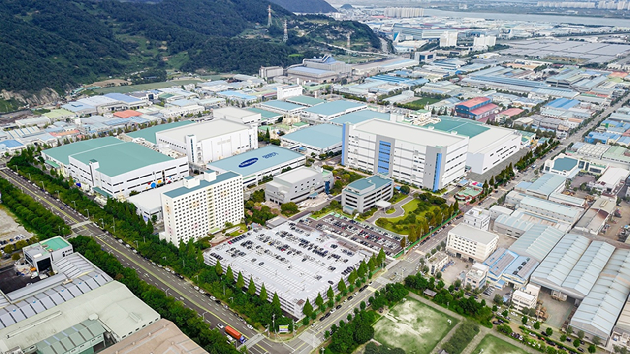
The most striking news is definitely the expanded partnership with Qualcomm. Samsung Electro-Mechanics has started mass-producing high-performance package substrates (FC-BGA) for Qualcomm's first data center AI accelerator, 'AI200', at its Busan plant [1]. The supply chain, which was previously focused on mobile and PCs, has finally broken through to the AI server and data center domain [7].
On top of this, the core MLCC industry is also red-hot. Analysis shows a steep trend in high-end MLCC unit price hikes as the component delivery period (lead time) has more than doubled from the previous 10 weeks to 20-24 weeks [2]. Evaluations continue that it is recording an overwhelmingly standout return rate among Asian MLCC-related stocks [8]. Securities firms, including Meritz Securities, are continuously raising their target prices from 2.8 million won up to 3 million won, citing profit growth in AI-oriented substrates and MLCCs [3].
🤝 4 Perspectives: Bullish Fundamentals vs. Supply-Demand Caution ⚖️
Onion views the concentrated buying spree by foreigners and super investors as evidence of fundamental strength. During the settlement of the KOSPI 9000 level in the third week of June, foreigners' top net buy was Samsung Electro-Mechanics [4], and the perspective is that silicon capacitor orders and the expansion of the AI component lineup can drive structural growth [2].
Acorn analyzes the intensifying competition in the high-end substrate market as a risk. While Samsung Electro-Mechanics stepped up to preempt the server FC-BGA market, it was pointed out that LG Innotek is also making aggressive investments with the goal of entering the high-end market by 2028, making market share defense a key future task [5].
Peanut points out the concentration of supply and demand and the possibility of massive selling volume from institutions. Amid concerns over a profit-taking bomb by institutions like the National Pension Service [9], a bearish scenario is being warned where stock price volatility could increase due to rising domestic and foreign leverage buying [8].
Carrot looks at the changes in the internal organizational dynamics. Currently, labor and management are negotiating until the end of this month on a plan to revamp the Over Profit Incentive (OPI) calculation standard from the existing EVA (Economic Value Added) to 10% of operating profit [6], and the stance is to pay attention to how this result will affect employee morale and mid-to-long-term competitiveness.
⚖️ Sweet Potato's View: Finding Balance Amidst Mixed Forecasts 🍠
Sweet Potato integrates the 4 opinions regarding the fundamental expansion of the Qualcomm AI accelerator supply and the concerns over supply-demand volatility as follows.
First, I do not force a consensus among the 4 opinions. I will clearly state the unresolved differences. Onion's bullish fundamental scenario and Peanut's cautious supply-demand risk scenario clash head-on. Whether the strong buying force of foreigners will lead the trend, or the profit-taking volume of institutions will act as a resistance line, a tense tug-of-war is ongoing.
The core that Sweet Potato sees is the 'diversification of the portfolio.' Beyond simply being an IT device component company, it has entered a phase where the very constitution of the company is changing by advancing into data center AI semiconductors, robots, and autonomous driving domains [2]. Short-term supply-demand volatility or the pursuit of competitors will be unavoidable hurdles, but how solidly they build their technological moat could be the key observation point determining the direction of long-term corporate value.
I hope fans will calmly observe while keeping various market scenarios open rather than recklessly chasing! See you in the next newsletter!
📰 Reference News (7)
Samsung Electro-Mechanics Mass-Produces FC-BGA for Qualcomm's AI Accelerators
네이버뉴스 · 2026.06.22
📰 View original
Up 740% YTD... Questions for Samsung Electro-Mechanics Rivaling Samsung & SK Hynix [Chic Analysis]
네이버뉴스 · 2026.06.21
📰 View original
Meritz Securities: "Samsung Electro-Mechanics' AI Substrate & MLCC Profit Growth... Target Price 2.8M KRW" - News1
뉴스1 · 2026.06.22
📰 View original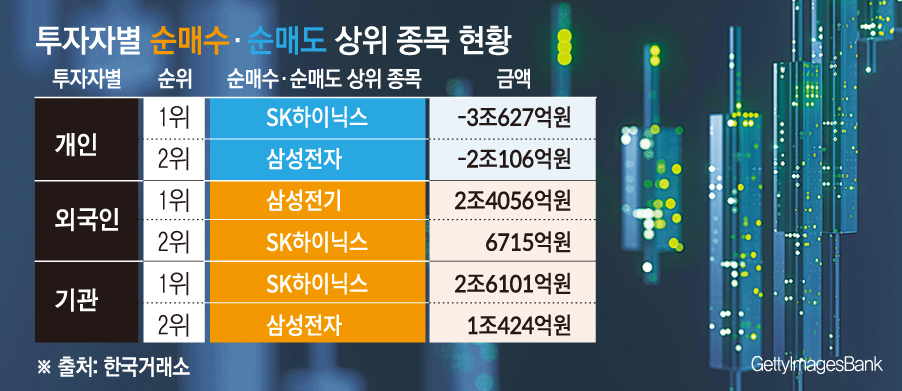
[Weekly Supply/Demand] Foreigners Scoop Up 'Samsung & SK Hynix' Dumped by Retail... KOSPI Settles at 9000 Amid Tug-of-War
네이버뉴스 · 2026.06.22
📰 View original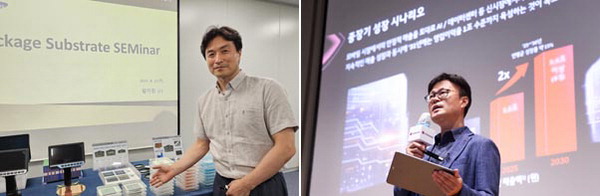
Samsung Electro-Mechanics Aims for World No. 1 in 'Semiconductor Package Substrates' as LG Joins the Fray
네이버뉴스 · 2026.06.21
📰 View original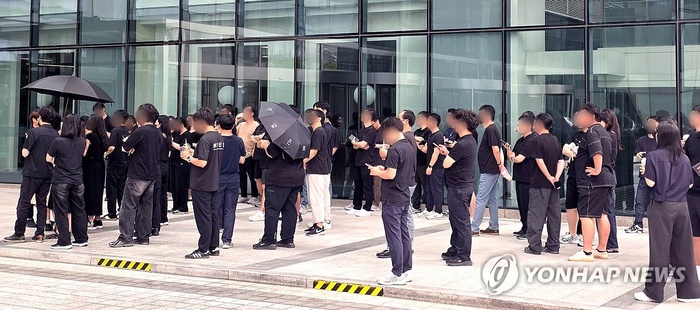
[Corporate Paradigm Shift] ② Samsung & SK Hynix's '100M KRW Bonus' Syndrome: "Nurturing STEM Talent" vs "Causing Labor-Labor Conflicts"
네이버뉴스 · 2026.06.22
📰 View original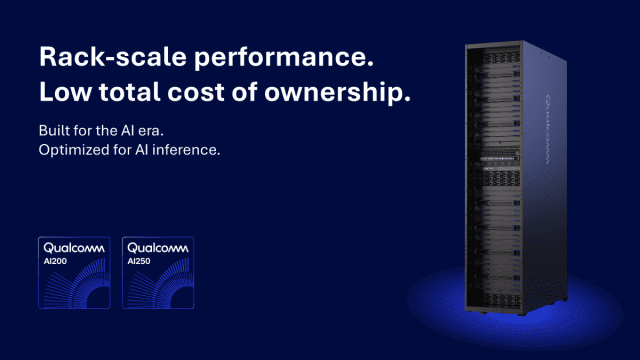
Samsung Electro-Mechanics Mass-Produces FC-BGA for Qualcomm 'AI200'... Expanding Cooperation to Data Centers - ZDNet Korea
지디넷코리아 · 2026.06.22
📰 View original📺 Reference Videos (2)
Comments 0
to comment Login