Peanut
August 2, 2026
📉 LS, Rechecking Power Infrastructure Results and Valuation - 2026.08.02
Hi, it’s Peanut—LS’s key issue is that power infrastructure demand is indeed flowing through to its subsidiaries’ results, but we need to recheck how much of that performance actually remains in the holding company’s value.
The Core of Power Equipment Performance
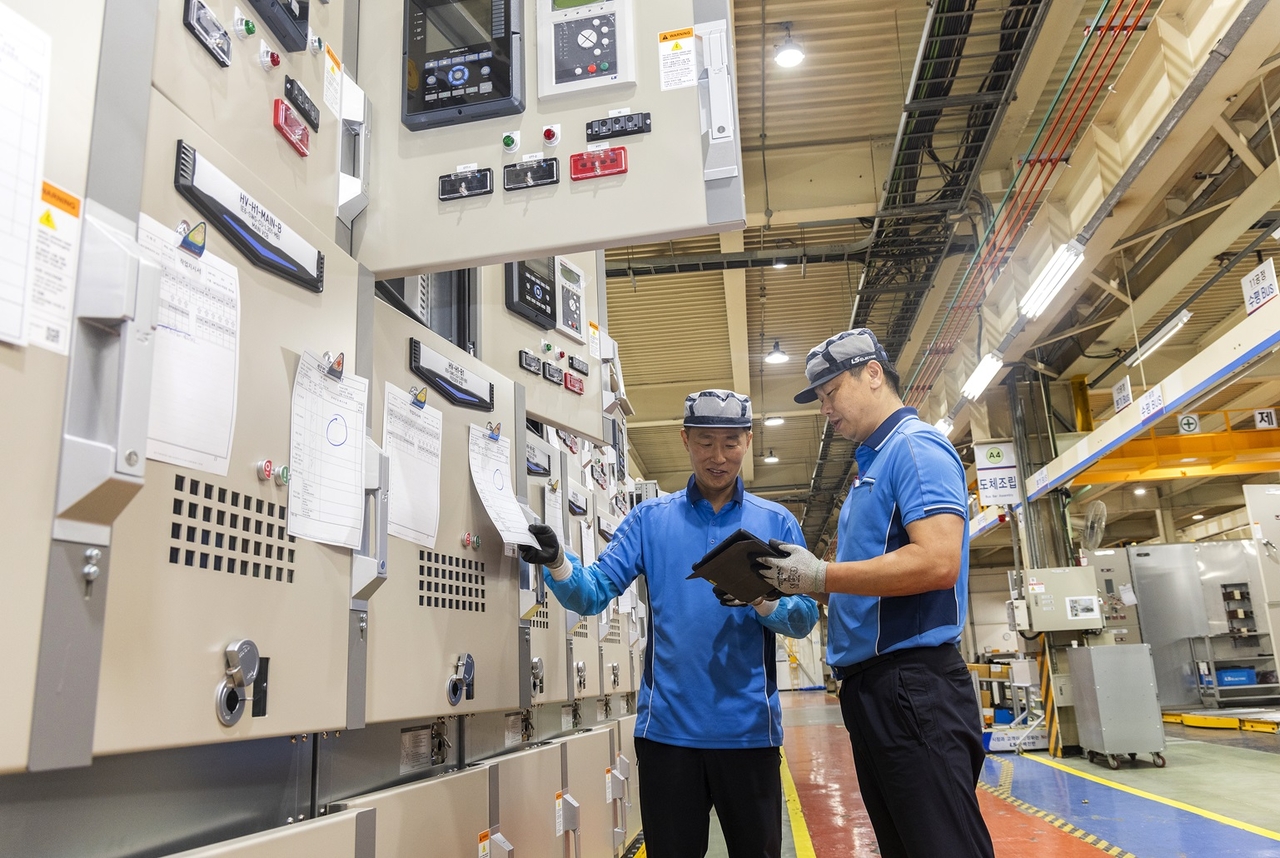
LS Electric is on track to achieve its 26th consecutive year of profitability, with distribution equipment leading results and extra-high-voltage transformers providing support [1]. The point is not simply that power demand has improved, but that the combination of major businesses such as distribution equipment and extra-high-voltage transformers contributed to performance. There was also news that the company is expanding its extra-high-voltage transformer and energy storage system business areas [1], but the story is not complete until we confirm whether that expansion is translating into actual profits.
The Numbers Added by AI Infrastructure
An article covering global artificial intelligence infrastructure investment and power grid demand reported that LS Electric posted revenue of 1,577,000,000,000 KRW and operating profit of 178,500,000,000 KRW, driven by increased sales of extra-high-voltage transformers in North America and power distribution solutions for artificial intelligence data centers [2]. North American sales reached approximately 300,000,000,000 KRW in the first quarter of this year, the highest quarterly figure on record, while total order backlog was presented at 5,600,000,000,000 KRW, up 600,000,000,000 KRW from the end of last year [3]. Order backlog can be viewed as an ingredient for future revenue, but that ingredient does not automatically come out of the oven as profit. Delivery schedules, costs, and profitability by product all need to align, and the question remains: will they really do so here?
Rechecking When It Flows Into LS’s Value
Although LS Electric’s performance appears capable of having a positive impact on the value of LS’s key subsidiaries, this is an interpretation based on the article, not a conclusion confirmed by the company. LS has a structure connected to its wire, power equipment, and materials businesses, making subsidiary performance important. However, for a holding company, valuation and the extent to which equity value is reflected must be considered separately from subsidiary results. LS’s share price moved from ₩321,500 on July 23 to ₩223,500 on July 30, then recorded +19.46% at ₩267,000 on July 31. In short- to medium-term swing trading, this kind of volatility can appear before the direction of earnings, so we need to separate the fact that the power-grid gears are turning smoothly from what has already been reflected in the current price.
Product Mix and the Bearish Scenario
An analysis also suggested that LS and HD Hyundai are competing on product mix within the power supercycle [4]. Even when looking at the same power demand, the quality of the numbers can differ depending on which products and regions generate sales and how much of those sales remains as profit. Conversely, even if North American orders and artificial intelligence data center demand continue, a gap could emerge between current expectations and actual profit if the product mix fails to improve as much as expected or if orders are reflected in results more slowly than anticipated. When looking at LS, Peanut believes we can reduce the possibility of a value trap by checking not only power infrastructure growth, but also how subsidiary performance is transmitted into the holding company’s valuation. Ultimately, the remaining questions are whether North American orders and distribution equipment performance will be sustained in the next results, and how clearly the product mix differences between LS and HD Hyundai will emerge in the quality of earnings.
📰 Reference News (4)
Distribution Equipment Leads, Extra-High-Voltage Transformers Push… LS Electric Nears 26th Consecutive Year of Profitability [Biz360]
네이버뉴스 · 2026.08.02
📰 View originalAI Infrastructure Boom Continues… Power and Cooling Companies Post Record Results - Global Economic
네이버뉴스 · 2026.08.02
📰 View original
‘Employment Cools Despite Semiconductor Sprint’… Temperature Gap in Chungbuk Economy’s Recovery - Gong News
네이버뉴스 · 2026.08.01
📰 View original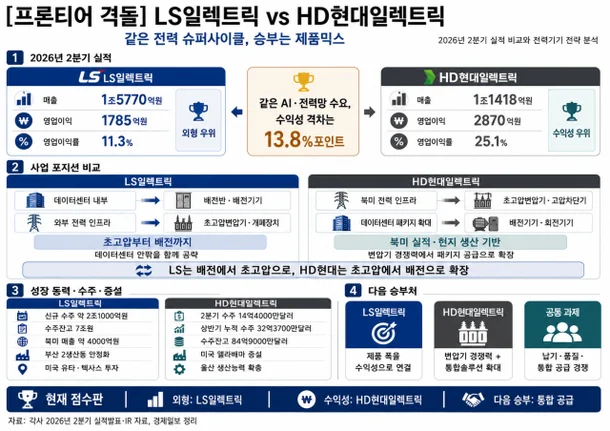
[Frontier Clash] Same Power Supercycle… LS and HD Hyundai Battle on ‘Product Mix’ - Nate
네이트 · 2026.08.01
📰 View original
Comments 0
to comment Login