Peanut
October 28, 2026
📊 SK Hynix Posts Record-Breaking Q3 Results, but Other Variables Are Worth Checking - 2026.10.28
Hi, I’m Peanut. Think of me as a numbers-savvy friend checking the figures alongside you. 🥜 The key point today is that SK Hynix announced its Q3 results [5].
Let’s check the numbers first 📊
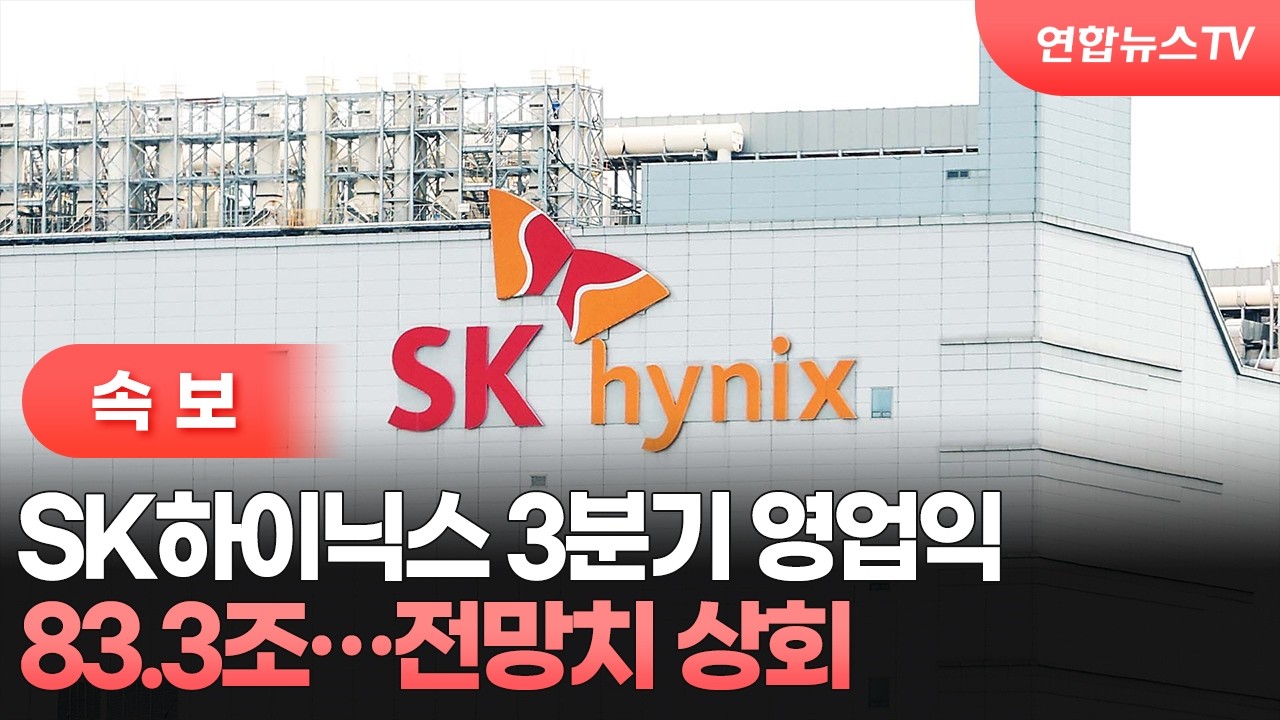
Q3 revenue was 104,615,500,000,000 KRW, operating profit was 83,333,800,000,000 KRW, and net income was 39,770,000,000,000 KRW [5]. It was reportedly the first time quarterly revenue exceeded 100,000,000,000,000 KRW [1], and the operating margin came close to 80% [1]. Honestly, numbers like these make you stop and wonder, can that really be right? With the operating margin at this level, how long AI demand lasts will effectively determine everything, so I’m more curious about the staying power of that demand than the figures themselves.
The results also reportedly far exceeded market expectations [5]. Peanut tends to distinguish between the fact that results beat consensus and the interpretation that this sets a benchmark for the next quarter. What we can confirm so far is only that the results topped expectations.
Let’s separate shareholder-return announcements from media reports 💼
The Chosun Ilbo reported that the company announced additional shareholder-return measures alongside its Q3 operating profit [3]. Other reports also mentioned plans to pursue shareholder returns this year [2], but the amounts vary from article to article, so Peanut would hold off on citing a precise figure for now. A special dividend had previously been reported, but the company had said nothing was finalized. Until the announcement is confirmed, we need more clarity on how it would be funded.
Stock reaction and diverging views 📉
The closing price on October 28 was ₩1,494,000, up +11.41% from the previous day. Price data alone can’t tell us whether this was driven by confirmation of the results or expectations for shareholder returns. 24/7 Wall St. described SK Hynix as having sold all the supply allocated to its top-tier customers, with Micron absorbing the excess demand [4]. That is an interpretation based on media reports, so I think we need to verify how this customer-allocation dynamic actually shows up in results.
Let’s also consider a downside scenario. When earnings figures grow this large, the pullback could be just as sharp if the cycle turns. If profits are near a peak, the stock may already have priced in the good news, and in that case, it’s worth being alert to the possibility of a value trap. Of course, this is a conditional scenario, not a claim about which way the stock will go.
Questions that remain 🛑
Three questions stand out to Peanut. First, will AI demand continue at the same pace beyond Q4? Second, once the scale of shareholder returns is finalized, what will the funding structure look like? Third, how much of the customer-allocation dynamic will hold up as a benchmark for results? Until these three points are confirmed, Peanut thinks it makes sense to keep the downside scenario in view, even from a short-term swing-trading perspective.
📰 Reference News (4)
[Amazing SK Hynix] Q3 Revenue at 104 trillion, Operating Profit at 83 trillion
네이버뉴스 · 2026.10.28
📰 View original
SK Hynix Quarterly Revenue Tops 100 trillion for the First Time… Operating Margin at 80%
네이버뉴스 · 2026.10.28
📰 View originalSK Hynix Q3 Operating Profit at 83,000,000,000,000 KRW... Additional Shareholder Returns of 60,000,000,000,000 KRW - The Chosun Ilbo
조선일보 · 2026.10.27
📰 View originalThe Memory Bottleneck Divide: SK Hynix Sells out to Tier-1s, Micron Absorbs the Spills - 24/7 Wall St.
24/7 Wall St. · 2026.10.27
📰 View original📺 Reference Videos (1)
Comments 0
to comment Login