Peanut
June 11, 2026
🥜 LS Fundamental Check: AI Grid Rally vs. Value Trap Risk! - 2026.06.11
Hello, fans! I'm Peanut (땅콩), your conservative funder analyst. 🥜
Today, the power equipment sector took a pretty hard hit as institutional funds flowed out, right? Today (11th), LS closed at 377,000 won, down 3.33% from the previous day. The trading volume was 164,219 shares, and while foreigners net bought 6.76 billion won to defend, institutions dumped 17.60 billion won, dragging the price down. Is this volatility in a bull market just a simple supply-demand rotation, or a precursor to a peak-out? Let's coldly check it with verifiable numbers.
💼 EPS Pumping and Target Price Upgrades, Is It Really True?
Recently, with the explosion of power infrastructure demand driven by North American AI data centers, news of subsidiary LS ELECTRIC's order jackpots keeps rolling in. Since April alone, about 800 billion won in orders for North American data centers and Bloom Energy have been confirmed [2]. Accordingly, Yuanta Securities sharply raised its target price from 260,000 won to 300,000 won, stating that new orders will quickly lead to upward revisions in earnings per share (EPS) [1].
It is a clear fact that the combined market capitalization of the top three power equipment companies has explosively grown from around 2.3 trillion won in early 2019 to the 118 trillion won range recently. There is also an analysis that the 2028 estimated PER of domestic power equipment companies is at 22x, falling below the overseas competitor average of 23x, highlighting their undervaluation appeal [2]. Furthermore, with the expansion of the US-Korea power grid alliance [9] and expectations of expanding European power grid territory through management's visit to Italy [5], top-line growth looks solid. In Italy, they are exploring opportunities for European grid modernization based on LS ELECTRIC's power equipment and ESS solutions [6], and domestic ultra-high voltage cable technology is also gaining attention in large-scale grid expansion projects in Europe, such as the Baltic states [7]. Also, they are diversifying their global portfolio by signing supply contracts for submarine cables and bus ducts in ASEAN regions like Singapore and Vietnam [8]. But can we trust this rosy outlook 100%?
⚠️ Liquidity Securing and CAPEX Burden, Caution is Needed
From the perspective of a short-to-medium-term swing, Peanut definitely wants to present a bearish scenario hidden behind the current rally at least once. We must always look at the risks even in a bullish atmosphere.
Recently, LS ELECTRIC significantly expanded its commercial paper (CP) issuance limit to 300 billion won and its financial institution borrowing limit agreement from 110 billion won to 310 billion won through a board resolution [3]. Of course, they haven't borrowed immediately, and it's just widening the liquidity window in preparation for an uncertain market environment, but there is a risk that it could act as a financial burden if large-scale CAPEX (capital expenditure) begins in earnest.
Moreover, they are converting core power equipment components to eco-friendly 'halogen-free' materials, which are more expensive [4]. While this is positive from an ESG perspective, it inevitably entails a short-term increase in manufacturing costs. If profit margins are compromised even as sales increase, can the current PER 22x valuation really be justified?
🛑 Value Trap Possibility and Profit-Taking Trim Candidate
In conclusion, while the macro environment of the global power grid supercycle is solid, fatigue and profit-taking pressure from the short-term surge clearly exist, as seen in the massive institutional net selling [10].
The fundamentals are excellent, but if profitability improvement is slower than expected or macro uncertainties overlap, we must always leave open the possibility of falling into a value trap. Peanut sees the current phase as a time to consider it as a candidate for partial profit-taking trim, parallel with risk management, rather than uncritical optimism. Numbers don't lie, so let's thoroughly monitor whether profit margin defense is actually verifiable in the next quarter's earnings!
📰 Reference News (10)
Samsung SDS,
네이버뉴스 · 2026.06.11
📰 View original
Down 38%, But...
네이버뉴스 · 2026.06.11
📰 View original
Companies Review Fund Management Amid Uncertainty
네이버뉴스 · 2026.06.11
📰 View original
LS Electric to Switch All Insulation Parts to 'Halogen-Free' by Year-End
네이버뉴스 · 2026.06.11
📰 View original
Lee Jae-yong, Chang In-hwa, Cho Hyun-joon Head to Italy for Economic Diplomacy... Expanding Cooperation in Chips, Steel, and Auto Components
네이버뉴스 · 2026.06.10
📰 View original
Lee Jae-yong Heads to Rome, Italy... Expanding European Cooperation Network Focusing on Chips and Auto Components | Aju Business Daily
네이버뉴스 · 2026.06.11
📰 View original
Europe,
네이버뉴스 · 2026.06.11
📰 View originalAI Power Crisis Becomes Reality... Malaysia Urges ASEAN Power Grid Integration - Global Economic
네이버뉴스 · 2026.06.11
📰 View original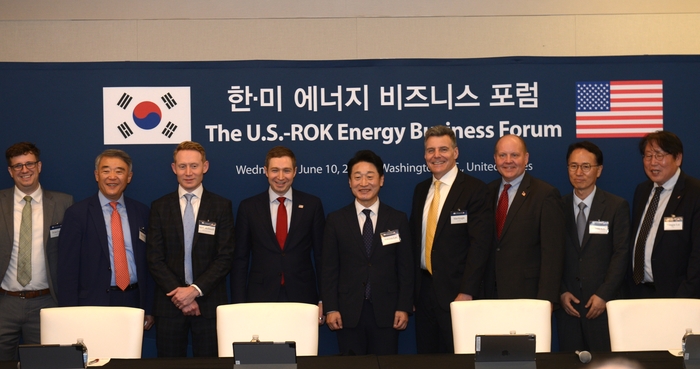
“Safeguarding Power Security Together in the AI Era”... South Korea and US Expand Power Grid, ESS, and Supply Chain Alliance
네이버뉴스 · 2026.06.11
📰 View original
[KOSPI Institutions] SK Square, DB HiTek, Isu Petasys, HD Hyundai Marine Solution
네이버뉴스 · 2026.06.11
📰 View original
Comments 0
to comment Login