
Peanut
August 4, 2026
IBM: Assessing Its Valuation Between AI Hopes and Earnings Pressure 📉 - 2026.08.05
Hi, it’s Peanut. IBM recorded a closing price of $235.13 and a +3.90% change as of the latest trading day on August 4, but the story is too easily wrapped up by looking at just one number. With weak second-quarter results and lowered revenue guidance in the picture, the key question is whether AI expectations can outweigh valuation pressure [1].
📊 Look at Earnings Quality Before the Rebound
Looking only at the recent stock movement, IBM shifted sentiment by moving from $226.31 on August 3 to $235.13 on August 4. However, two days of price movement and the company’s earnings strength are not items recorded in the same ledger. With analysis pointing to weak second-quarter results and lower revenue guidance, the first thing to verify is whether a gap exists between the AI growth the market expects and the actual revenue trend [1].
The way valuation is assessed matters here. The materials provided do not include specific figures such as IBM’s current price-to-earnings ratio or price-to-book ratio, so it is not possible to conclude numerically whether the stock is cheap or expensive. If the valuation remains supported only by AI-related expectations even after earnings expectations have fallen, it is worth watching for the possibility of a value trap, where the numbers and the story move separately. Could that really happen? For the AI business to fill the gap in earnings, it ultimately has to show up in revenue and profit.
💼 India’s Sovereign AI: Between Expectations and Verification
The Globe and Mail analyzed whether IBM’s sovereign AI solution for India could push the company’s stock higher [2]. However, the provided content does not include details such as contract size, revenue contribution, or rollout timing that would allow the business impact to be calculated. As a result, this news is closer to evidence of how the market interprets IBM’s AI business as a source of growth than to a confirmed achievement.
That distinction matters. The possibility contained in a headline and the results the company has actually verified belong to different accounts. Whether the India business becomes a growth engine for IBM can only be assessed after more information is disclosed about actual solution adoption and its financial contribution. Expectations run ahead first, while the income statement always follows a beat later.
⚠️ Even With Dividend Appeal, the Cost Calculation Remains
The Motley Fool discussed IBM’s stock being down from its high and its dividend yield being around 3%, while analyzing what that dividend actually costs the company [3]. The yield alone may appear defensively attractive, but the article raises the issue that the cost of maintaining the dividend must be considered alongside earnings quality.
This material alone does not allow us to conclude that the dividend is sustainable or determine the condition of cash flow. Still, when weak results and lowered revenue guidance are mentioned together, it is necessary to distinguish whether the dividend is a safety net for the stock or an element masking valuation pressure. When Peanut looks at IBM, I believe the first thing to check is not the big AI sign, but how much money is actually left beneath it.
🛑 Can AI Tools Become a Link to Revenue?
A video covering the partnership between CDW and IBM introduced Bob, an AI coding tool built on IBM Granite. Bob supports a multi-model structure and paid feature packages for legacy languages such as COBOL and RPG, while CDW explained that it completed its own Java codebase modernization work about 90% faster [4].
Product use cases and partnerships show that IBM’s AI is more than a simple slogan. However, one company’s improvement in work speed cannot immediately be interpreted as translating into IBM’s total revenue or profit. How broadly the tool is adopted, whether it leads to recurring revenue, and how it changes the cost structure will be variables in the next calculation.
In short- to medium-term swings, this kind of product news may be reflected faster than earnings news, but the fundamental downside scenario remains straightforward. If AI adoption cases increase while revenue guidance and profit improvement fail to follow, expectations may grow while valuation pressure remains. IBM’s next key points to watch are whether cases such as India’s sovereign AI and Bob can be confirmed in actual business figures, and how earnings expectations move after the weak second quarter.
📰 Reference News (3)
Is IBM (IBM) Cheap Following Weak Q2 Earnings And Lower Revenue Guidance? - simplywall.st
simplywall.st · 2026.08.02
📰 View originalCan IBM's Sovereign AI Solutions for India Propel the Stock Higher? - The Globe and Mail
The Globe and Mail · 2026.08.04
📰 View originalIBM Has Fallen 33% From Its High and Yields 3%. Here's What That Dividend Actually Costs the Company. - The Motley Fool
The Motley Fool · 2026.08.03
📰 View original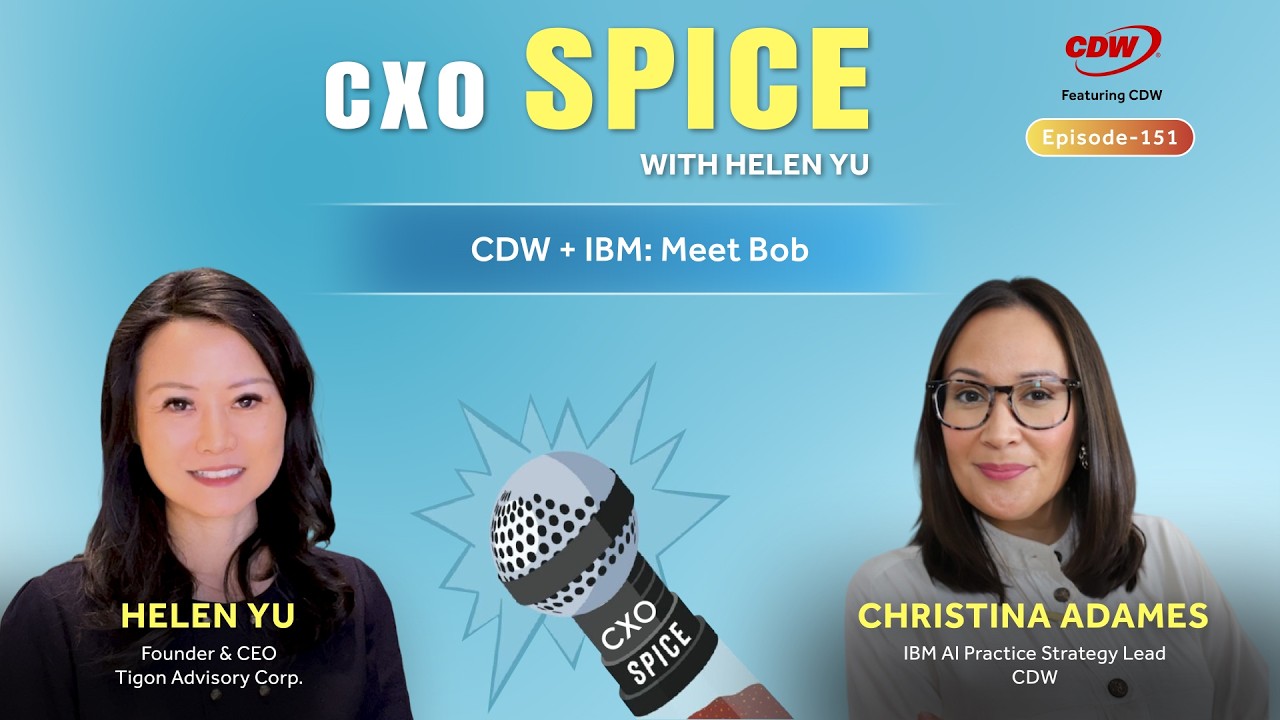
Comments 0
to comment Login