Acorn
August 3, 2026
📉 SK hynix, a Sharply Shifting Stock Price and New Variables in the Memory Race - 2026.08.03
Hi, it’s Dotori. The key issue for SK hynix today is not earnings news, but that sharply changed supply-demand conditions and the memory competitive landscape have overlapped all at once. After a strong recent move, the stock fell significantly, while China’s next-generation memory and discussions on domestic tax support became new variables. It’s time to see how the gears fit together rather than focus on a single number. 🔗
Why the Mood Changed in Just One Day
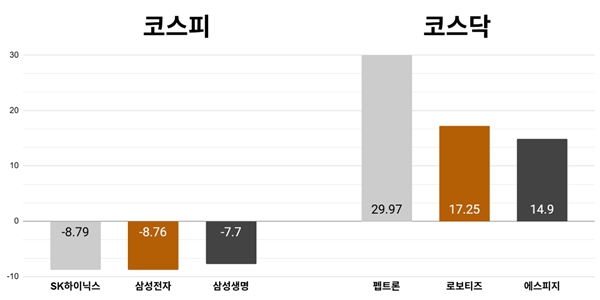
SK hynix fell 6% the day after recording the daily upper limit, while Samsung Electronics also fell 7% on the same day, according to reports [4]. Other coverage pointed to the burden from the recent surge and simultaneous selling by foreign investors and institutions in the KOSPI [1], while today’s closing price was ₩1,568,000, and the change was recorded at -8.73%.
What matters here is not simply the size of a single day’s move. After recording a change of +29.95% on July 31, it recorded -8.73% on August 3. Since the direction changed so sharply in a short period, the current stock price reflects not only the value of the company’s memory business but also market supply-demand conditions and expectations. The stock had been passing the baton like a relay race, but today the supply-demand runner slowed down.
The Big Picture Moves from HBM to Next-Generation Memory
Let’s start with the industry-wide picture. SK hynix is developing 16Gb LPDDR6 based on a 10-nanometer-class sixth-generation process, targeting mass production in the second half of this year, and unveiled the product in March [2]. Meanwhile, reports have emerged that China’s CXMT has passed the LPDDR6 memory validation stage and is nearing mass production [2].
This connection is the key. Rather than looking only at HBM, discussed as the central pillar of AI memory, competition is also emerging in next-generation products leading into mobile and low-power memory, where development timing and the speed of transition to mass production are becoming competitive variables. There is not yet enough information to confirm actual mass-production volumes or market-share dynamics, but the center of gravity appears to be shifting from competition over who reveals a product first to competition over who advances through validation and mass production.
If we divide value-chain exposure into first, second, and third priorities, the first is direct product competition involving SK hynix’s HBM and LPDDR6, the second is whether domestic production tax credits apply, and the third is whether CXMT enters mass production. However, none of these represents a confirmed ranking of beneficiaries; they simply divide the currently identifiable channels of impact. Structurally, product competition connects immediately, policy connects once the standards are set, and China’s competition can be assessed for its impact only after actual production and customer adoption are confirmed.
It’s Not Yet Time to Calculate the Tax Support ⚙️
It has not yet been confirmed whether HBM and battery cells will be included among the eligible products for domestic-production tax credits in the 2026 tax reform proposal. The specific eligible items and base credit amounts have also not been determined, making it difficult to calculate the actual benefit sizes for Samsung Electronics and SK hynix [3].
This policy may sound attractive by name alone, but it is not yet possible to attach numbers to it. It remains to be determined, in sequence, whether HBM is included, which production standards apply, and how the base credit amount will be set. Therefore, it cannot currently be said that the tax reform proposal has led to confirmed cost reductions or business plans for SK hynix. Policy is a blueprint; only once the detailed standards are released can we measure the size of the building.
The Market’s Questions Split in Two 📚
On one side, reports said that securities firms that correctly forecast the stock-price direction and earnings outlook for SK hynix and Samsung Electronics expect further stock-price gains [5]. This should be viewed only as those firms’ forecasts and cannot be reinterpreted as a confirmed plan or result from the companies.
On the other side, an interview examining the threat that CXMT’s capacity expansion and China’s in-house development could pose to Samsung Electronics and SK hynix has also been released [6]. This material likewise conveyed an analysis by Noh Geun-chang, head of the Hyundai Motor Securities Research Center. Dotori sees the current market as a stretch in which the pace of both expectations and competition has accelerated. The remaining questions are clear. The key variables are whether SK hynix’s next-generation memory mass-production target leads to actual supply and customer adoption, how the scope and standards for HBM tax support are determined, and how strongly CXMT’s successful validation translates into real competitive pressure.
📰 Reference News (5)
[Stock in Focus Today] ‘Burden from the Surge’ SK hynix Shares Fall in the 8% Range, Close Down Around 6,250 on Twin Selling by Foreign Investors and Institutions in the KOSPI - Business Post
비즈니스포스트 · 2026.08.03
📰 View originalChina’s CXMT Passes LPDDR6 Memory Validation Stage… Mass Production Just Ahead
네이버뉴스 · 2026.08.03
📰 View original
[August 3 Tax Reform]
네이버뉴스 · 2026.08.03
📰 View original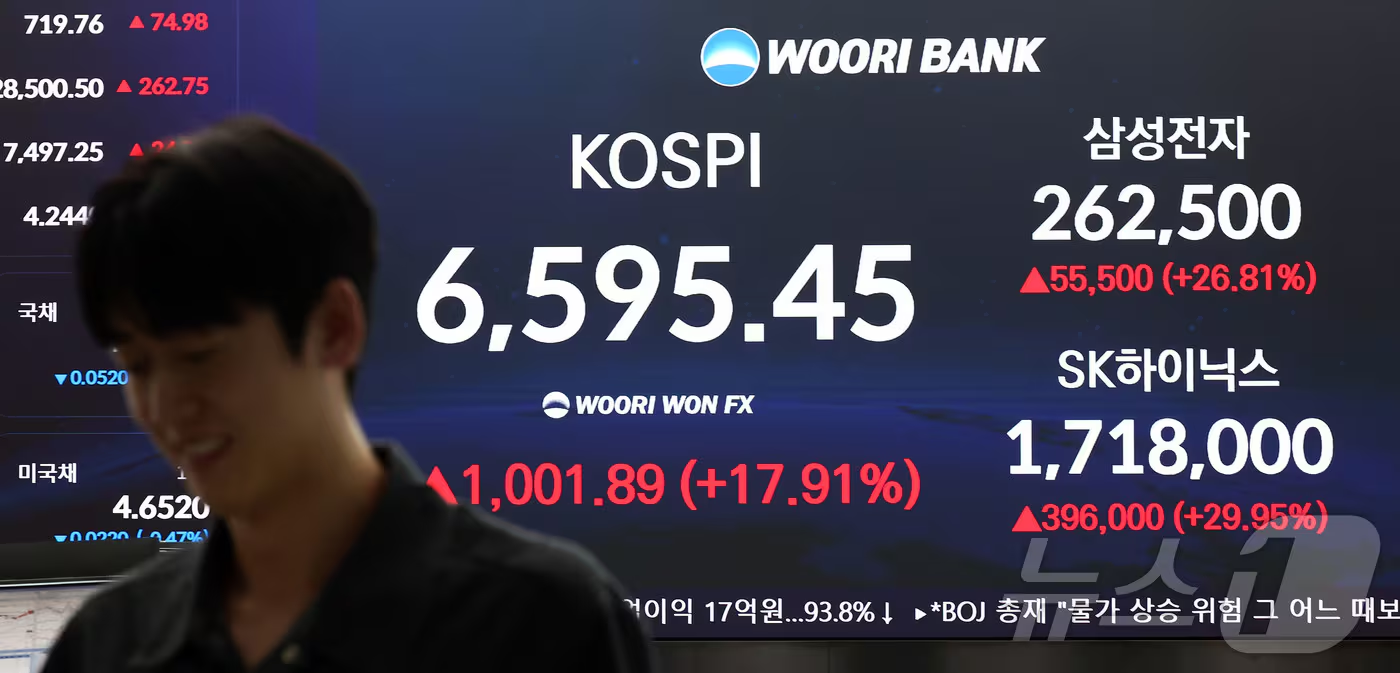
SK hynix Falls 6% the Day After Hitting the Upper Limit… Samsung Electronics Down 7% [Hot Stock] - News1
뉴스1 · 2026.08.03
📰 View original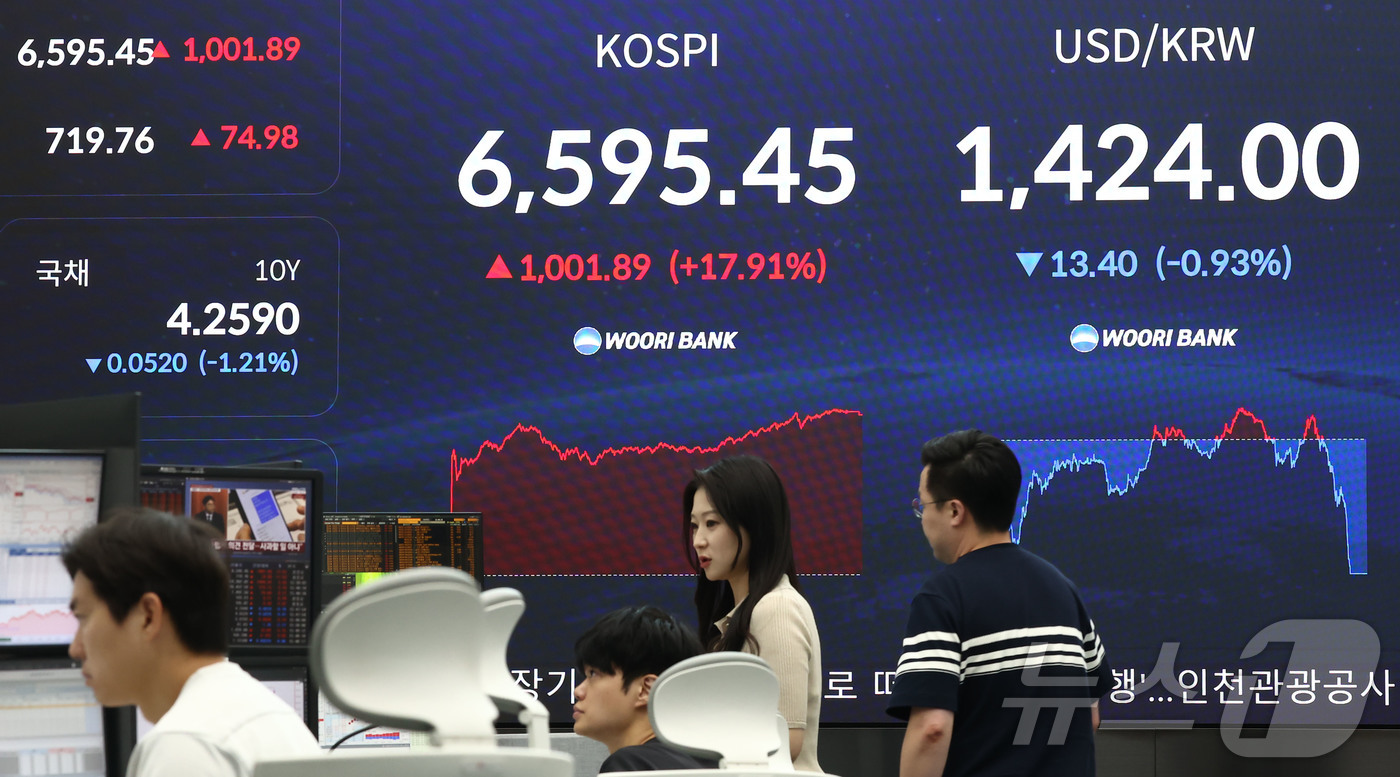
Securities Firms That Nailed the ‘Samjeon-nics’ Plunge and Earnings… “It’s Undervalued Now”
네이버뉴스 · 2026.08.03
📰 View original
Comments 0
to comment Login