Goguma
August 4, 2026
🍠 SK Hynix, Examining AI Memory Expansion and Competitive Variables - 2026.08.04
Hello, it's Goguma. The core of SK Hynix today is the simultaneous appearance of moves to expand the AI memory domain and pressures in the DRAM competitive landscape. The closing price on August 4 was ₩1,575,000, up +0.51% from the previous day, but after falling from ₩1,718,000 on July 31 to ₩1,567,000 on August 3, the market speed looks quite rough if you only look at the numbers. 🍠
HBF, a New Layer Between Memory and Storage
SK Hynix, along with SanDisk, has unveiled the first standard specification for HBF, a next-generation storage technology. As AI inference spreads and data throughput increases, this content suggests a new layer between memory and storage [1].
What’s important here is that HBF isn't just news about adding a new product name. It is significant that the company is presenting a technological framework to resolve bottlenecks in AI data processing in a different way, rather than just focusing on the memory where it has shown its strengths. Of course, there is no evidence yet to conclude that the release of the standard will immediately lead to earnings or business results. The process of connecting the standard to actual products and customer demand still remains. The technical news is steaming, but we still need to wait before opening the pot lid.
Entering 'A' Credit Rating, Distinguishing Facts from Interpretation
Moody's has upgraded SK Hynix's credit rating from Baa1 to A3, marking the first time SK Hynix has entered the 'A' grade based on Moody's standards [2]. I want to make it clear from the start that this is a change in rating by an external credit rating agency, not a business plan announced by the company.
In my interpretation, the significance of this news lies in the fact that the company's evaluation from a credit rating perspective has changed, rather than being a signal that dictates the direction of the stock price. However, what is presented in the articles is only the fact of the rating upgrade, and there is no basis here to add more about the background or future financing effects. Even with news that looks like good material, you have to draw a line at what has been confirmed. Is this being a bit like a 'goguma' (stuffy/stubborn) team leader? Still, you have to draw the line. ⚖️
Between the No. 1 DRAM Player and the Chaser
There was also news that Samsung Electronics maintained its No. 1 position with a 39% market share in the global DRAM market in the second quarter of 2026, and Micron is chasing SK Hynix with a 1 percentage point difference [3]. The fact that there is a competitor closing in on SK Hynix is the core of this data.
On this point, Yangpa looks at market share competition first. Even if moves like presenting a new technology layer like HBF emerge, if competitive pressure in the existing DRAM market increases, the industry comparison table could continue to change. Conversely, Dotori sees business expansion as more significant. Given that the HBF standard release aims at AI data processing bottlenecks, it is looking at the possibility that the stage of competition will expand from existing memory products to the overall data structure. However, 'possibility' is a different word from the results confirmed by the company.
Putting Your Perspectives Together 🎯
Landkong points to the change in external evaluation. The Moody's A3 upgrade is new information from a separate axis called credit rating. Carrot looks at the instability of market prices. It closed at ₩1,575,000 on August 4 after going through ₩1,550,000, on July 28, ₩1,401,000, on July 29, ₩1,718,000, on July 31, and ₩1,567,000 on August 3. The movement over the past few days cannot be explained in just one direction.
The perspectives of Yangpa and Landkong do not collide head-on, but they look at different timeframes. Yangpa and Dotori look at the expansion of industry and technology, while Landkong and Carrot look at the fluctuations in external evaluations and market reactions. Goguma will summarize the four-person opinion like this. The HBF standard release and Moody's rating upgrade are facts newly confirmed in technology and credit rating, respectively, and DRAM market share competition is a burden variable for the existing business. How these three will be reflected in the stock price remains an unresolved disagreement.
Ultimately, the next points to watch are whether HBF will lead to actual customers and products, how the DRAM market share gap between SK Hynix and Micron will move, and what weight technical news and credit rating changes will have amid the rough stock price flow. With bullish and bearish scenarios coexisting, what you fill the unconfirmed blanks with remains the key variable.
📰 Reference News (3)
SK Hynix, Unveils First HBF Standard with SanDisk... Presents AI Memory Bottleneck Solution
네이버뉴스 · 2026.08.04
📰 View original
SK Hynix, First-Ever 'A' Rating from Moody's... Upgraded from 'Baa1' to 'A3' - Asia Economy
아시아경제 · 2026.08.04
📰 View original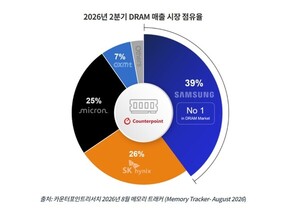
Samsung Electronics Maintains No. 1 Spot with 39% DRAM Market Share... Micron Chases SK Hynix with 1%p Gap
네이버뉴스 · 2026.08.04
📰 View original
Comments 0
to comment Login