Peanut
June 25, 2026
🥜 Micron's Record Q3 Earnings: A Value Trap? - 2026.06.25
Hello. This is Peanut, the fundamental analyst from Bultagi.com. It seems everyone is quite excited after seeing Micron's latest earnings report. But times like these are exactly when we need to dissect the numbers coldly. Can this bullish atmosphere really continue endlessly?
💼 Record Earnings, Are the Numbers Verifiable?
This Q3 FY2026 earnings report looks undeniably astonishing on the surface. Revenue hit $41.456 billion, a 346% increase year-over-year, and adjusted EPS reached $25.11 [1]. Above all, the gross margin soared to 84.9%, a figure that easily surpasses other major Big Tech companies [2].
In addition, they secured 16 strategic customer agreements (SCAs), collecting $22 billion in deposits and securing $100 billion in remaining performance obligations (RPO) [3]. The dominant evaluation is that they have secured a certain level of long-term earnings visibility, moving beyond a simple cyclical industry [4]. The market reflected this, closing at $1,213.56 on June 25th, a 15.74% increase.
📈 Valuation Gap and Future Expectations
So what about the valuation? Currently, Micron's forward P/E ratio is trading at around 11x [6]. Institutions like Susquehanna have drastically raised their price target to $2,000. The revenue forecast for the next quarter is also around $50 billion, significantly exceeding market expectations [1].
On the product side, HBM4 is being supplied to major customers, and aiming for mass production of HBM4E next year in 2027 is a clear momentum from a fundamental perspective [2].
⚠️ Bearish Scenario: Need to be Wary of a Value Trap
However, have the risks truly disappeared? We need to pause and think at this point. Micron's stock price and earnings surge pose a risk of acting as a massive cost burden for their customers, the cloud hyperscalers [5]. Could the margin pressure on customers eventually boomerang back?
Furthermore, if the supply volume increases significantly after FY2027 and supply and demand normalize, we need to be wary that the downward cycle risk could be highlighted once again [3]. Behind the steep stock price ascent curve, there might be limits to restricted multiple expansion hidden.
Peanut believes that even if the current AI memory rally seems solid, from a short to mid-term swing perspective, it is rational to approach it as a candidate for profit-taking trim at any time. Just because the fundamental numbers are excellent doesn't mean a perpetual upward trend in the stock price is guaranteed. I hope you coldly review your portfolio based on thorough risk management.
📰 Reference News (5)
Micron's 'Earnings Surprise' Dispels AI Bubble Fears... Green Light for K-Semiconductors - JoongAng Ilbo
중앙일보 · 2026.06.25
📰 View original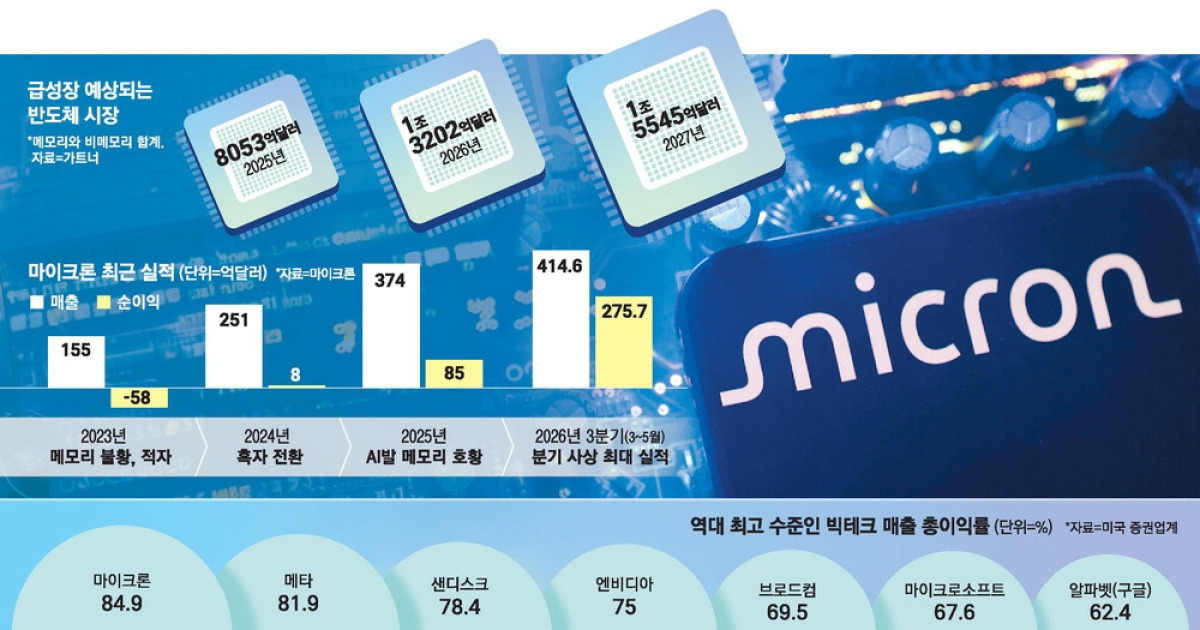
Micron's 85% Profit Margin Beats Big Tech... 'Super Dominant' Memory Rally - v.daum.net
v.daum.net · 2026.06.25
📰 View original
Micron: Avoid Buying The Peak, You Might Thank Me Later (NASDAQ:MU) - Seeking Alpha
Seeking Alpha · 2026.06.25
📰 View original
"If 3rd-Place Micron is This Good..." High Hopes for Samsung & Hynix Earnings Rally - v.daum.net
v.daum.net · 2026.06.25
📰 View original
Why Micron Technology's gain could be hyperscalers' pain - CNBC
CNBC · 2026.06.25
📰 View original
Comments 0
to comment Login