Acorn
October 21, 2026
📊 SK Hynix: Record-Breaking Results Forecast Meets Questions About HBM4 - 2026.10.21
Hi, I’m 🌰 Dotori. Let’s start with the big picture. The stock rose sharply in a single day and closed at ₩1,296,000 (+5.97%) [3]. We’ll have to wait and see whether this was a bounce off the bottom or a rebound amid volatility.
Earnings expectations are still supporting one side of the story 🔗
Market analysts say SK Hynix could post record operating profit again in the third quarter of this year [1]. The important point is that this is a forecast, not earnings confirmed by the company. It’s best to read it as a directional signal rather than focus on the number.
But what if things are stumbling on the HBM4 front? ⚙️
This is the key link. Reports in the same vein have also noted that shipments of sixth-generation high-bandwidth memory, HBM4, are falling short of expectations [2]. Earnings expectations are high, but if SK Hynix’s edge in HBM4 weakens, it’s like one cog in the machinery isn’t turning properly. Still, these are also forecasts and assessments, so we shouldn’t jump to conclusions about the causes or the company’s intentions.
Investor flows, the listing debate, and factory preparations 🏭
Reports say foreign investors have been net sellers for a month, while controversy over a subsidiary’s dual listing has added to the mix [7]. There’s also been news that Solidigm’s IPO is raising concerns among investors, though we’d need to read the original report to know the specific reasons [6]. Meanwhile, reports say the company has completed its share buyback [5], and Newsis reports that it is bringing in veteran investment professionals for its fab construction project [4]. Looking at the value chain, this suggests factory preparations are getting underway by moving people first.
Dotori’s value-chain take 📚
If I were to rank things in order, first would be how much HBM4’s competitive edge supports earnings expectations. Second would be the pace of capacity expansion execution, such as fab construction preparations, and third would be sentiment factors like investor flows and the listing debate. Dotori sees the HBM4 shipment trend as the central axis of this round. But this is my interpretation of the sources, not a plan announced by the company.
So there’s one question left: How will HBM4 shipments measure up to expectations, and will foreign investor flows shift enough to change direction? 🤔 Looking at both together should make the next picture a little clearer.
📰 Reference News (6)
‘77 trillion record’ for SK Hynix… ‘Warning lights’ for its HBM4 dominance
네이버뉴스 · 2026.10.21
📰 View original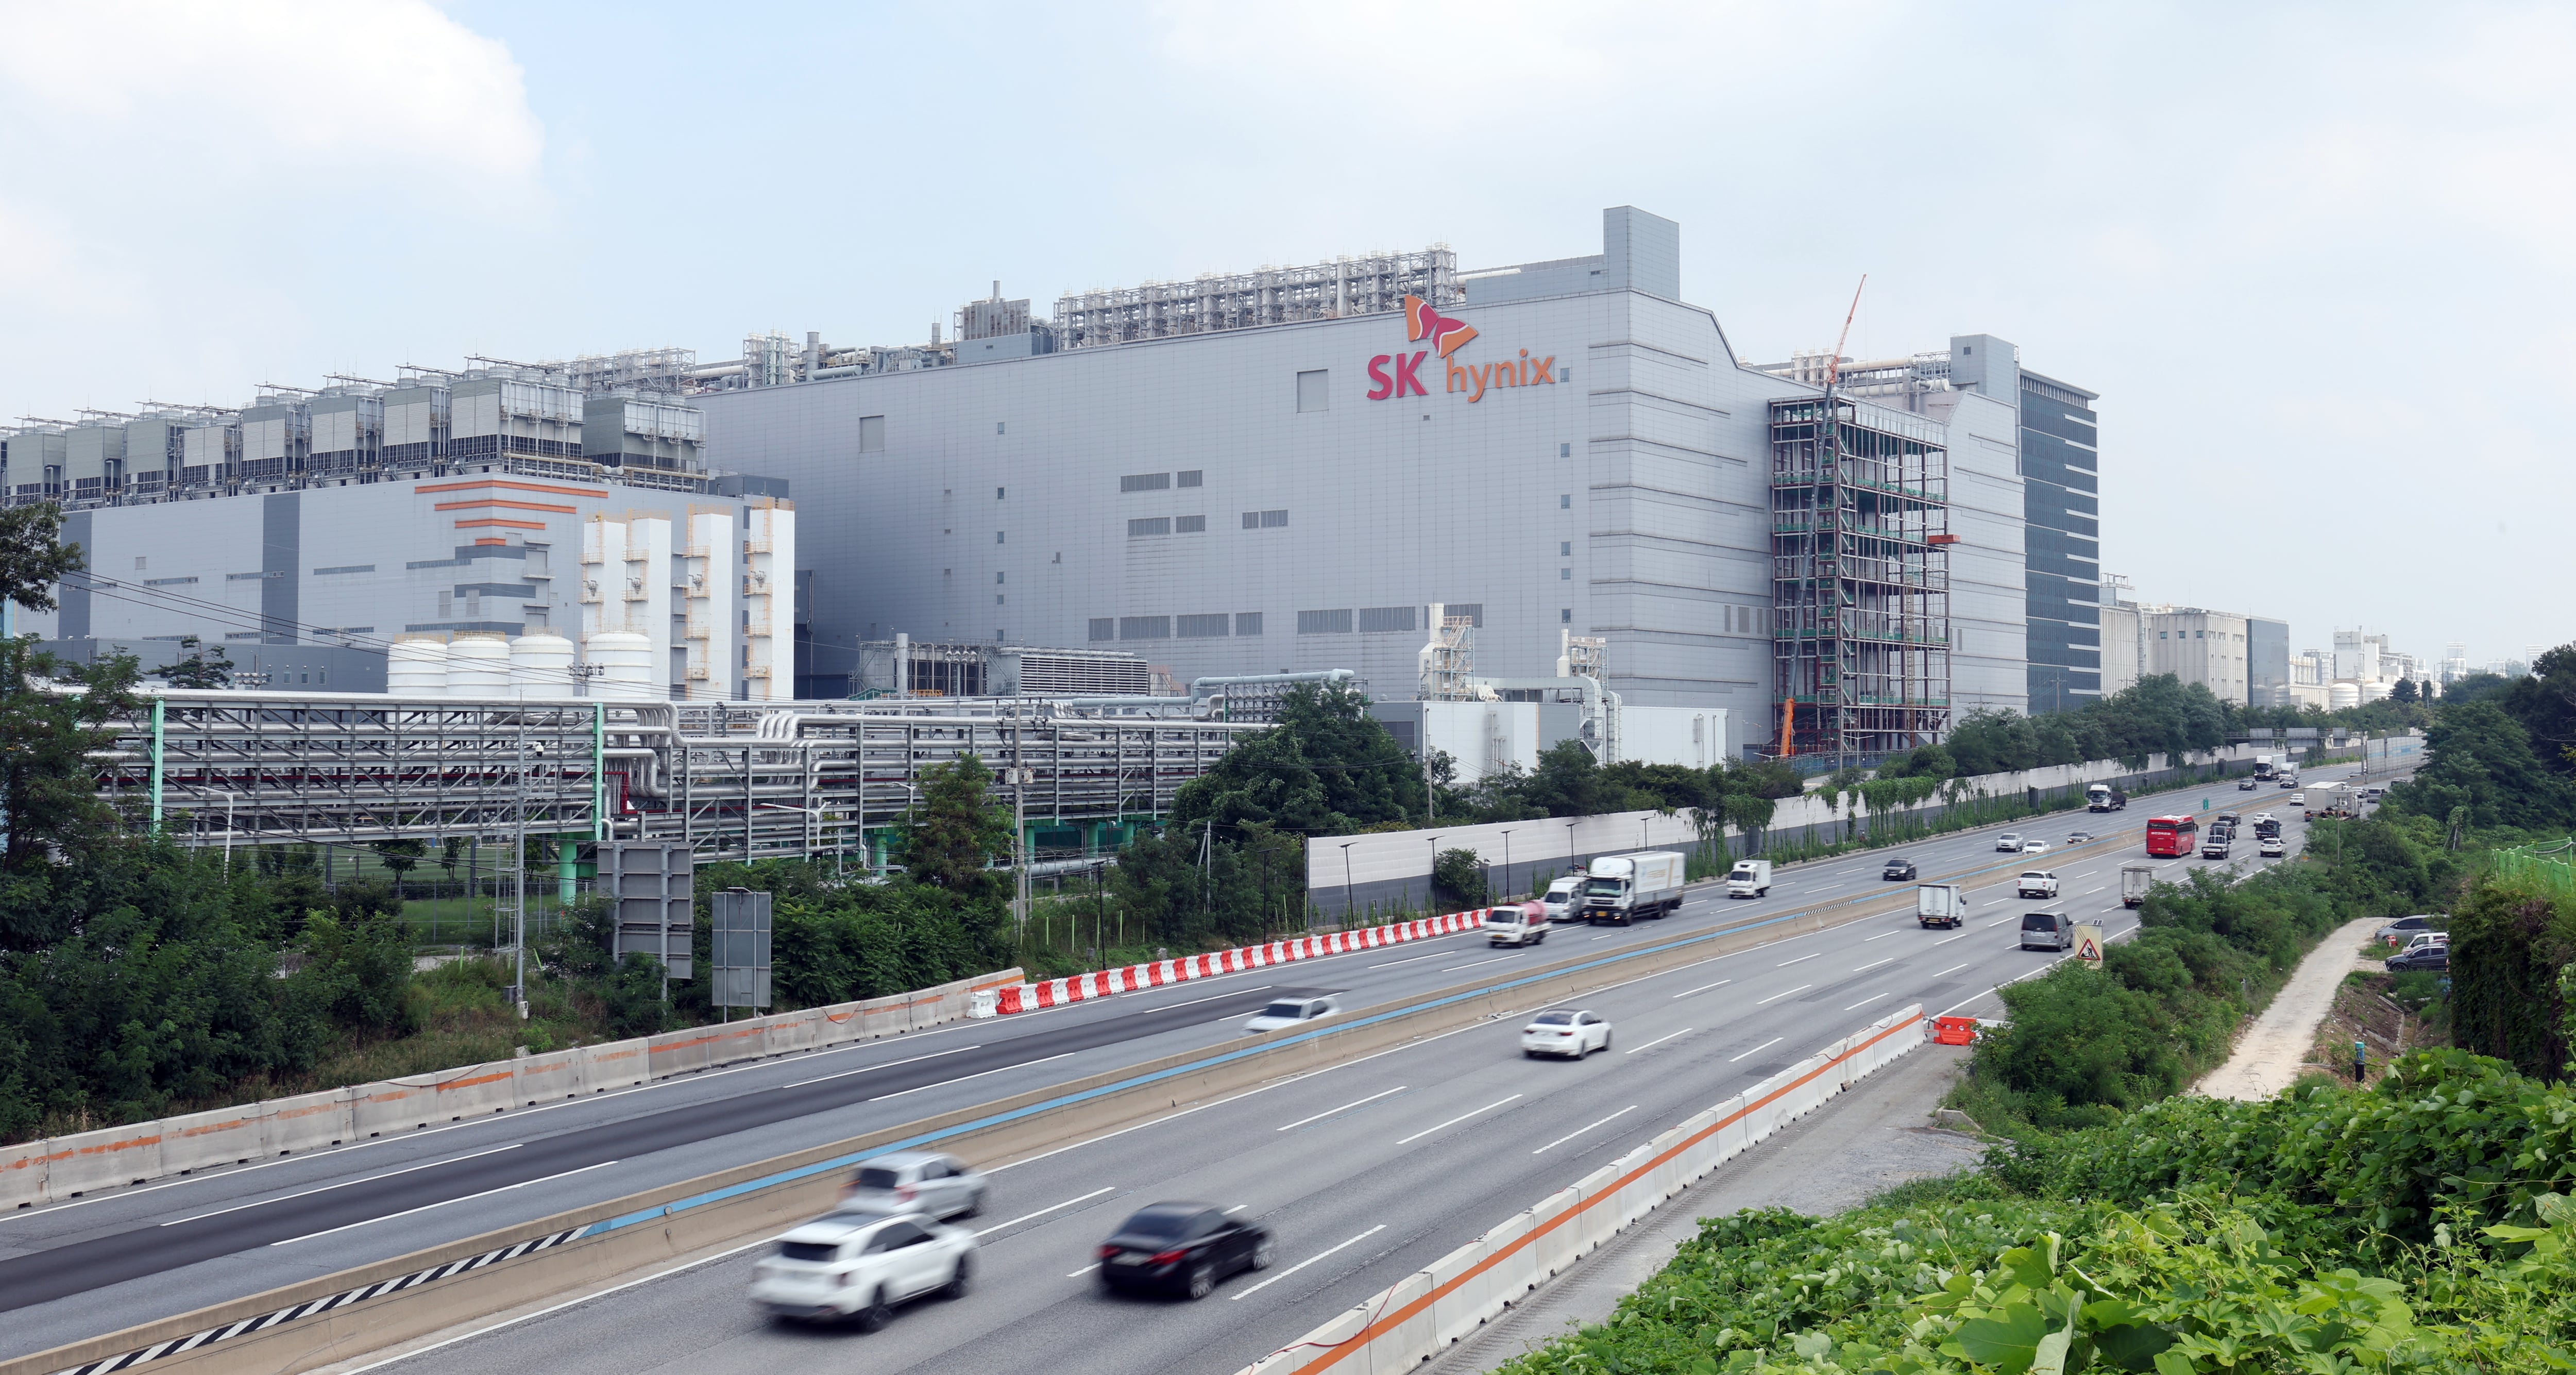
SK Hynix’s concern hidden beneath the boom… “Losing ground in the HBM4 market”
네이버뉴스 · 2026.10.21
📰 View original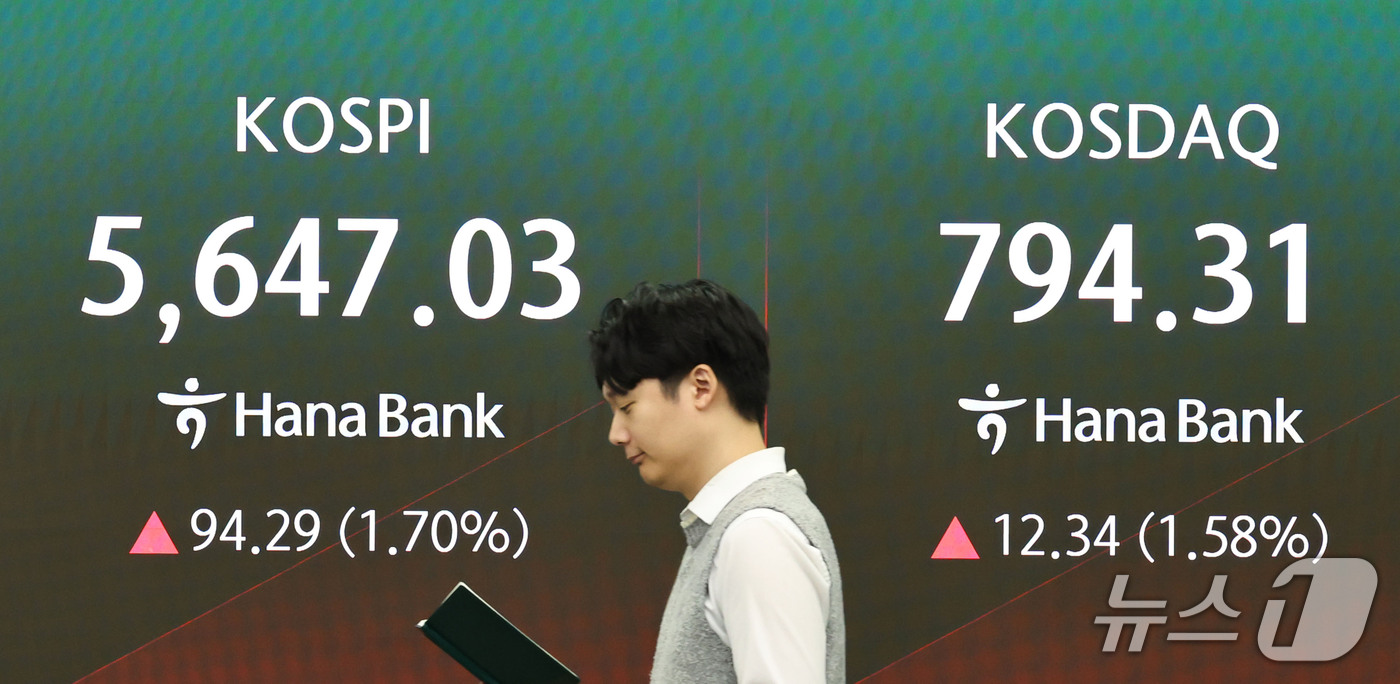
KOSPI surges 4%, triggering a buy-sidecar for the first time in two months… Reclaims the 5,800 level [Intraday Market Report]
네이버뉴스 · 2026.10.21
📰 View original
“Seeking investment veterans” SK Hynix recruits talent for ‘fab construction project’ - Newsis
뉴시스 · 2026.10.20
📰 View originalSK Hynix completes share buyback worth 40 trillion - Asia Economy
아시아경제 · 2026.10.21
📰 View originalSolidigm IPO raises concerns for 3.5 million SK Hynix investors - upi
upi · 2026.10.20
📰 View original📺 Reference Videos (1)
Comments 0
to comment Login