Peanut
September 8, 2026
📉 Alphabet, Between Earnings Momentum and Valuation Pressure - 2026.09.09
Hi, it’s Peanut. Alphabet has entered a phase where earnings and AI usage trends are providing support, while valuation pressure is rising at the same time. The September 8 closing price was $335.18, and the change was -0.04%. Looking only at the numbers, the market has not yet reached a one-sided conclusion. But is that really the case? This time, let’s carefully break down whether the growth drivers can turn into real business value.
Earnings Are Solid, but Traffic Quality Is Key 📊
According to TradingView’s weekly recap on September 7, Alphabet’s second-quarter revenue increased 24%, and Berkshire Hathaway’s stake in Alphabet Class C was also mentioned [1]. The fact that earnings growth and institutional ownership news appeared together suggests that the market’s attention remains focused on both the numbers and supply-demand dynamics.
However, the trends in search and AI services are a little more complicated. A report citing BofA’s September 8 analysis said that Google web traffic remained steady, while ChatGPT and Gemini showed gains [2]. This does not mean the search-based business is immediately under threat, but it does require separate verification of how rising AI service usage will connect to the economics of the existing search business. A rising usage graph does not automatically mean the income statement will move at the same pace.
The Overvaluation Debate Is About Assumptions More Than Numbers ⚠️
GuruFocus analyzed GOOG as overvalued based on its GF Value assessment [3]. This is not a forecast confirmed by the company, but the judgment of an external valuation model. Rather than drawing a conclusion from a single figure, it makes more sense to examine how much AI growth and stable search traffic have already been reflected in the current valuation.
That is where the possibility of a valuation trap emerges. The growth narrative is rich, but if the pace of conversion into earnings is slower than expected, the case for justifying a high valuation could weaken. Conversely, if rising AI usage connects meaningfully to the actual revenue structure, the assumptions behind external valuations could be revisited. When Peanut looks at Alphabet, I think it is important to separate “Is this a good business?” from “How much of that good business has the current valuation already priced in?”
AI Is Expanding Beyond the Search Box 💼
Google was reported to be working with Nevoya to deploy electric semi-trucks in Texas [4]. Another report said that Google and Cathay Pacific had begun trials using AI to avoid aircraft contrail clouds [5], which can be seen as examples of AI expanding beyond search and advertising.
However, the articles do not provide grounds to conclude that these partnerships will immediately translate into Alphabet’s financial results. The process of turning technology into actual contracts, recurring revenue, and cost savings still lies ahead. There is quite a long corridor between an impressive demonstration and a profitable business.
Competitive variables also remain active in autonomous driving. A September 4 Schwab Network video compared Tesla’s Cybercab with Waymo and introduced Waymo as an example of a company already operating autonomous driving services on public roads [6]. Since Waymo’s current operations and Tesla’s competitive position were discussed together, the value of the Other Bets business may ultimately depend less on whether the technology exists and more on service scalability and competitive intensity.
Questions That Remain for Short- to Medium-Term Swings 📉
The bullish case is clear. Second-quarter revenue growth, stable Google web traffic, increasing Gemini usage, and AI partnerships beyond search all appear to form one package. The bearish scenario, however, is one in which AI usage rises while the profitability of the existing business and external valuation concerns remain. In that case, the growth narrative could risk turning into a value trap.
From a short- to medium-term swing perspective, three links ultimately remain to be tested: whether AI traffic leads to actual revenue, whether business results strong enough to overcome external claims of overvaluation become visible, and whether Waymo and new AI partnerships establish themselves as repeatable businesses. Alphabet’s next chapter is unlikely to be decided simply by whether more people are using AI. It will more likely hinge on how much of that increase remains as verifiable value.
📰 Reference News (5)
Weekly Recap: Berkshire stake in Alphabet Inc. Class C and Q2 revenue +24% - TradingView
TradingView · 2026.09.07
📰 View original
Google web traffic is 'steady,' while ChatGPT, Gemini see gains: BofA (GOOG:NASDAQ) - Seeking Alpha
Seeking Alpha · 2026.09.08
📰 View originalGOOG Looks 32.7% Overvalued on GF Value™ - GuruFocus
GuruFocus · 2026.09.08
📰 View original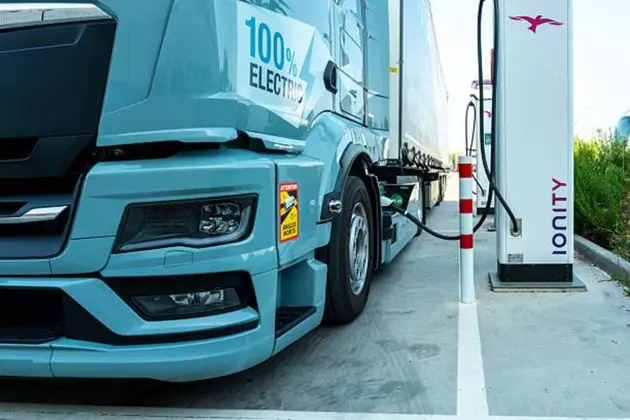
Google partners with Nevoya to deploy electric semi-trucks in Texas (GOOG:NASDAQ) - Seeking Alpha
Seeking Alpha · 2026.09.08
📰 View originalAlphabet's Google, Cathay Pacific Launch AI-Powered Contrail Avoidance Trials - Moomoo
Moomoo · 2026.09.08
📰 View original📺 Reference Videos (1)
Bull v. Bear: TSLA Cybercabs Hit Road, Accelerates GOOGL Waymo Competition
▶Schwab Network·2026.09.04
Comments 0
to comment Login