Peanut
June 20, 2026
💼 Hanwha Aerospace: 11T KRW European Investment & H2 Earnings... Beware of Value Traps? - 2026.06.20
Hello, this is Peanut from Bultagi.com, digging into fundamentals and valuation gaps. I wonder how everyone is managing their portfolios. Recently, Hanwha Aerospace's stock price has undergone a correction for two consecutive days, and market views are divided. It's time to coldly dissect the numbers hidden behind the glamorous order pipeline.
💼 The 11 Trillion KRW European Gamble: Is Free Cash Flow Safe?
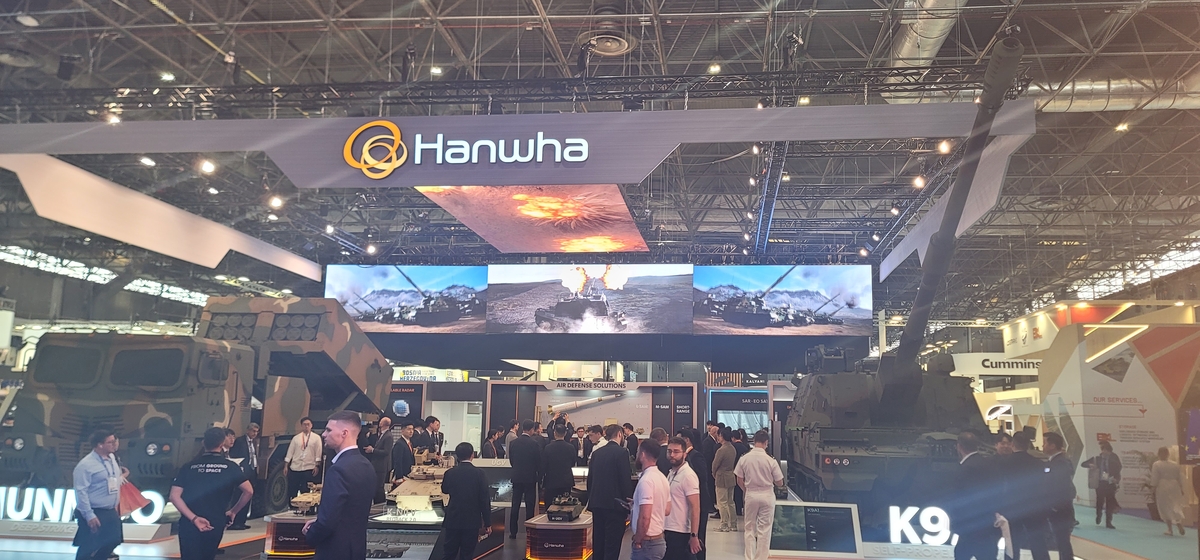
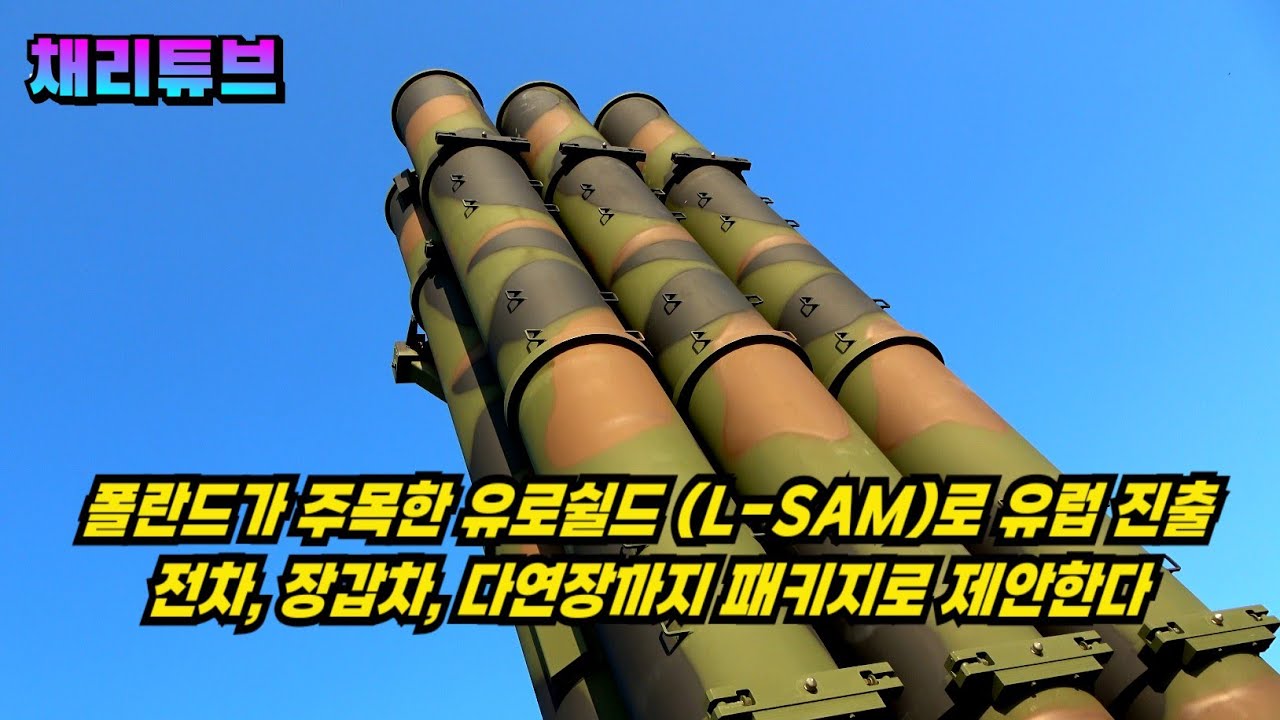
Hanwha Aerospace's recent moves at 'Eurosatory 2026' in Paris were prominent. They showcased the K9A2 self-propelled howitzer with an automatic reloading system capable of 8 rounds per minute, as well as the Chunmoo multiple rocket launcher [4]. In particular, Polish media are showing great interest in the direct hit-to-kill method of 'Euroshield', the export version of L-SAM [10].
What's noteworthy is that they are pushing an 11 trillion KRW investment plan to expand production bases across Europe [1]. 6.3 trillion KRW will be invested in establishing a joint venture (JV) in Poland, building the 'H-ACE Europe' production base in Romania, and setting up a Middle East joint factory [1]. On top of this, they signed an exclusive contract for the local production of K9 self-propelled howitzers with a local company in the UAE [2].
It's a truly impressive expansion, isn't it? But we need to stop and think here. A massive capital expenditure (CAPEX) of 11 trillion KRW can place a significant burden on the company's free cash flow (FCF) in the short term. While a localization strategy tailored to the 'Buy European' trend is essential, considering the payback period of this massive investment and the possibility of profitability impairment, is it verifiable?
📉 Dropping to the 1.11M KRW Range: Is Earnings Momentum Priced In?
Looking at recent stock price trends, it underwent a short-term correction, closing at 1,112,000 KRW (-6.48%) as of June 19 [3]. Nevertheless, Hyundai Motor Securities maintained a 'Buy' rating and proposed a target price of 1.78 million KRW [3].
The rationale is H2 earnings. They are forecasting this year's revenue at 30.568 trillion KRW and operating profit at 4.574 trillion KRW (a 48.1% increase YoY) [3]. The analysis suggests a clear 'low top, high bottom' earnings improvement is expected as the delivery of more than 30 K9s and 40 Chunmoos to Poland is concentrated in the second half [3]. It is true that the delivery schedules for major export volumes to Poland, Australia, and Egypt are concentrated in the second half of the year [9].
However, hasn't the market already fully priced this seemingly perfect H2 consensus into the valuation? Even if earnings visibility is high, if the valuation multiple has already reached its upper limit, there is a risk that the stock price will fluctuate wildly even on minor disappointment sell-offs.
⚠️ Mir-on Engine Defect and KAI Noise: An Excuse for Profit-Taking?
Even in a bullish atmosphere, we must always examine bearish scenarios. Recently, an investigation is underway regarding the cause of the engine defect in the Light Armed Helicopter (LAH) 'Mir-on', to determine whether it's Safran's design flaw or Hanwha Aerospace's assembly/manufacturing process issue [5]. If it turns out to be a manufacturing process issue, a hit to the quality reliability of K-defense built in the global market is inevitable.
Furthermore, noise is also occurring, such as the KAI labor union raising concerns that Hanwha's stake expansion could lead to a split between the fixed-wing and rotary-wing businesses [7].
From a short to mid-term swing perspective, Peanut views that behind the bullish atmosphere of H2 earnings expectations, the massive CAPEX burden and quality risks could stimulate the release of supply from profit-taking trim candidates, presenting a potential value trap. Even amidst rosy outlooks, vigilance for risk management is absolutely necessary at this juncture.
📰 Reference News (8)
Hanwha Aerospace Expands Bases in Poland & Romania... 11 Trillion Won for Local Production of Chunmoo [Eurosatory 2026]
네이버뉴스 · 2026.06.20
📰 View original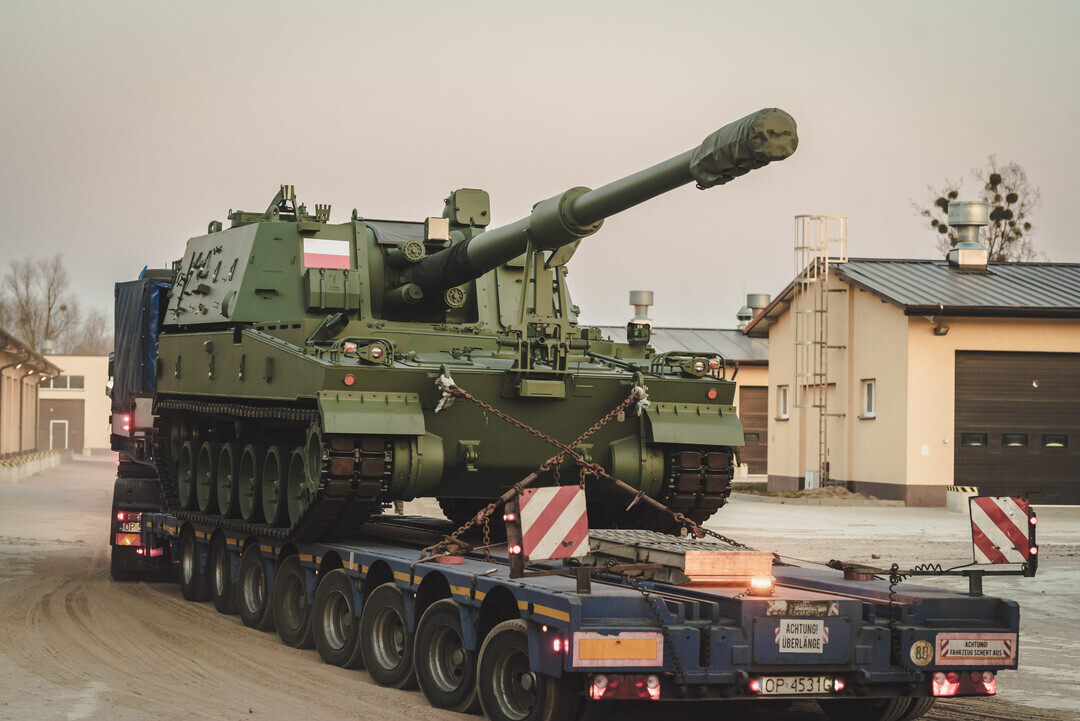
Hanwha Aerospace Signs Exclusive Contract with UAE for Local Production of K9 Howitzers
네이버뉴스 · 2026.06.20
📰 View original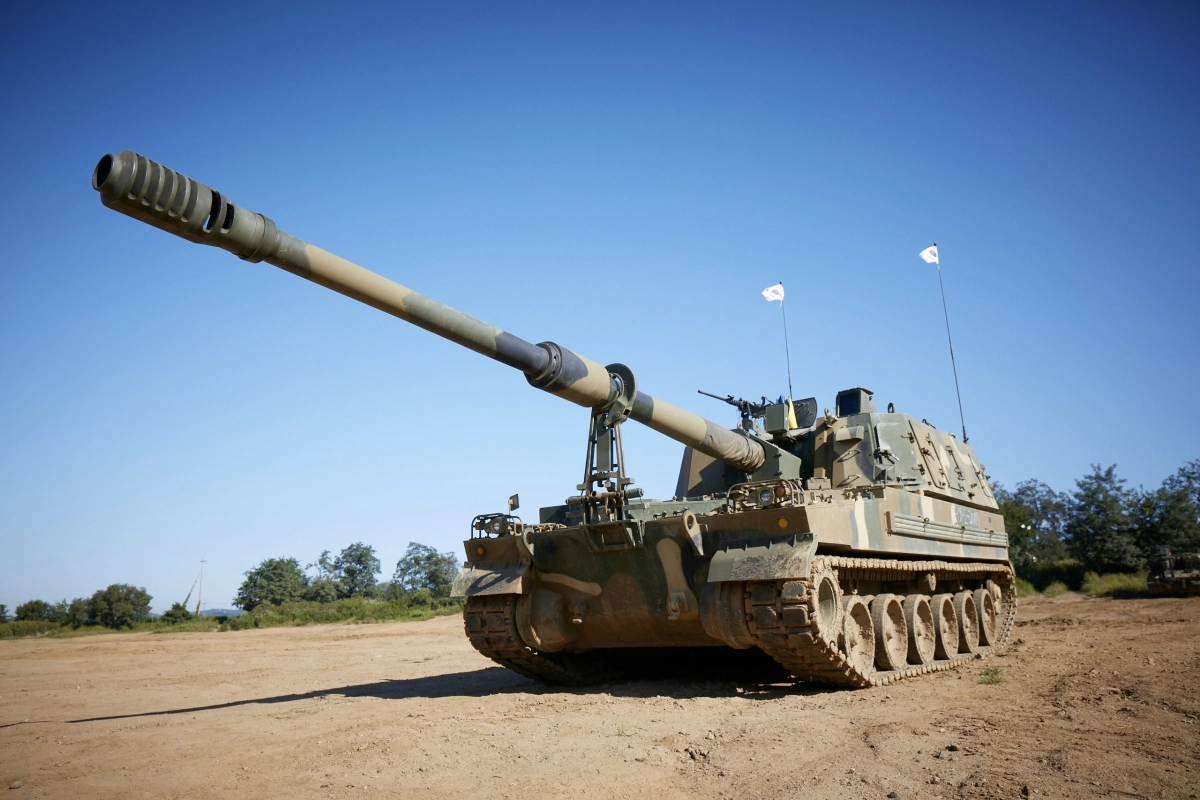
Hanwha Aerospace Down for 2 Consecutive Days... Analysts Say "Target 1.78M Won" [This Market, That Stock]
네이버뉴스 · 2026.06.20
📰 View original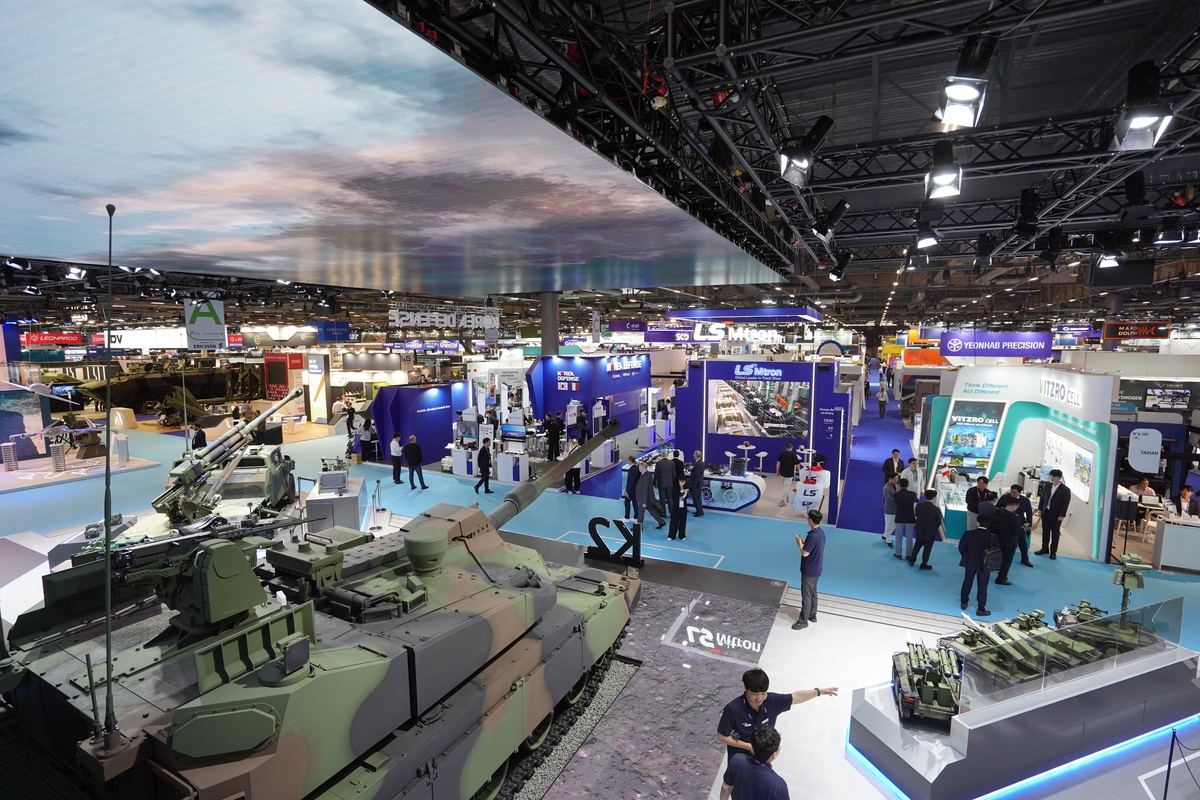
[Report] Multi-layered Defense with AI & Unmanned Systems... "K-Defense Seizes European Rearmament Boom" [Lee Hyun-ho's Military! Talk]
네이버뉴스 · 2026.06.20
📰 View original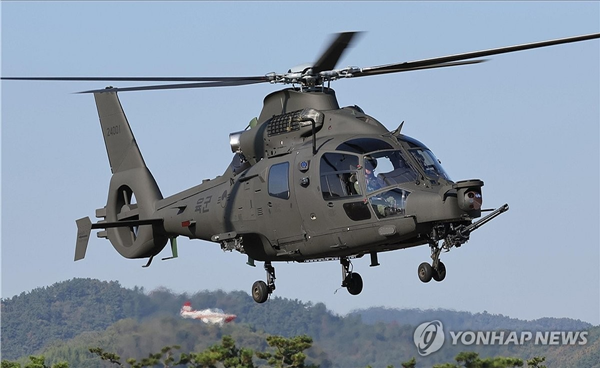
[Weapons in the News] Engine Defect Found in Light Armed Helicopter (LAH) 'Mireuon'... Needs to Prove Reliability to Prevent Recurrence
네이버뉴스 · 2026.06.20
📰 View original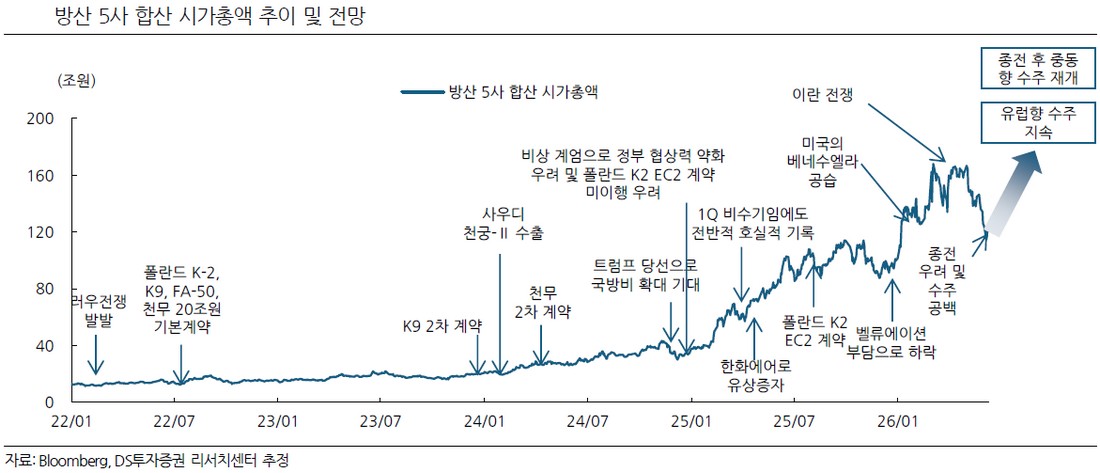
Collapsing European Security & Middle East 'End of War'... K-Defense Value Surges Amid Global Security Vacuum
네이버뉴스 · 2026.06.20
📰 View original
"Hanwha's KAI Stake Expansion is Not an Investment... Concerns Over Business Spin-off"
네이버뉴스 · 2026.06.19
📰 View original
[Newslock Special | K-Industry Earnings Weather Map Part 1] Thriving, Surviving, and Collapsing... Industry Forecast
네이버뉴스 · 2026.06.20
📰 View original📺 Reference Videos (2)

Comments 0
to comment Login