Peanut
June 4, 2026
💼 LS Fundamentals Check: Value Trap Risks Behind the Order Jackpot - 2026.06.04
Hello, fans. This is Peanut, the fundamental analyst at Bultagi.com.
Recently, the super-cycle narrative in the power equipment market has been dominating. But as always, it is time to coldly examine the numbers behind the flashy exterior. Today (the 4th), LS closed at 420,000 KRW, down 1.29% from the previous day, with a trading volume of 87,041 shares. Foreigners net sold 4.12 billion KRW, while institutions net bought 11.48 billion KRW, showing mixed supply and demand. Is this really the time to increase weight, or is it a moment that requires risk management.
💼 Strong Subsidiary Performance and Potential Re-evaluation of Holding Value
First, let's look at the positive fundamental indicators. NH Investment & Securities maintained its target price for the holding company LS at 600,000 KRW, citing mid-to-long-term earnings growth such as the expansion of LS Cable's extra-high voltage cable and busduct sales [1]. The momentum of its subsidiary, LS Electric, is also fierce. Korea Investment & Securities raised its target price by 29.5% to 285,000 KRW, noting that it secured 489.3 billion KRW in North American data center equipment orders in the second quarter alone [2]. The analysis states that a delivery speed 30% faster than competitors is its strong point [2].
In addition, the news that the combined order backlog of the three major power companies (HD Hyundai Electric, Hyosung Heavy Industries, and LS Electric) is on the verge of surpassing 35 trillion KRW supports the robustness of the downstream industry [4].
⚠️ Bearish Scenario Check Amidst the Bull Market
Is that really the case? It is a fact that orders are pouring in and earnings are being recorded, but is it verifiable that this will fully lead to the enhancement of shareholder value?
First, we must point out the double-edged sword of large-scale capital expenditure (CAPEX) burdens. Massive capital is being invested in factory expansions to meet the demand for AI data centers and aging power grid replacements [3]. There is no problem during a boom, but if the cycle turns or is delayed, there is a risk that this fixed cost burden will return as a financial risk.
Second, there is the governance and internal control noise. Recently, Chairman Koo Ja-yeol's responsibility for internal control supervision has come under scrutiny, drawing attention to negative disclosure events that occurred within a short period. No matter how good the fundamentals are, if question marks are attached to the management's risk control capabilities, resolving the holding company discount becomes distant, and there is a possibility of falling into a typical value trap.
📉 Short-to-Mid Term Swing Strategy and Conclusion
From a short-to-mid term swing perspective, the current price level is a section where the market's rosy outlook clashes with realistic financial and governance risks. The expectation that the strong performance of subsidiaries will be reflected in the holding company's value remains valid [1], but recent disclosure issues and foreign selling foretell short-term volatility.
Peanut views the current phase as a transition period digesting the financial burdens and governance noise behind the flashy order backlog.
Therefore, rather than blindly jumping on the bullish bandwagon, cautious vigilance is required by keeping bearish scenarios in mind and approaching it as a candidate for profit-taking trims during short-term spikes. Let's coldly observe how the next fundamental indicators turn out.
📰 Reference News (4)
NH Investment: "LS, Focus on Subsidiary Earnings Improvement and Holding Company Revaluation"
네이버뉴스 · 2026.06.04
📰 View original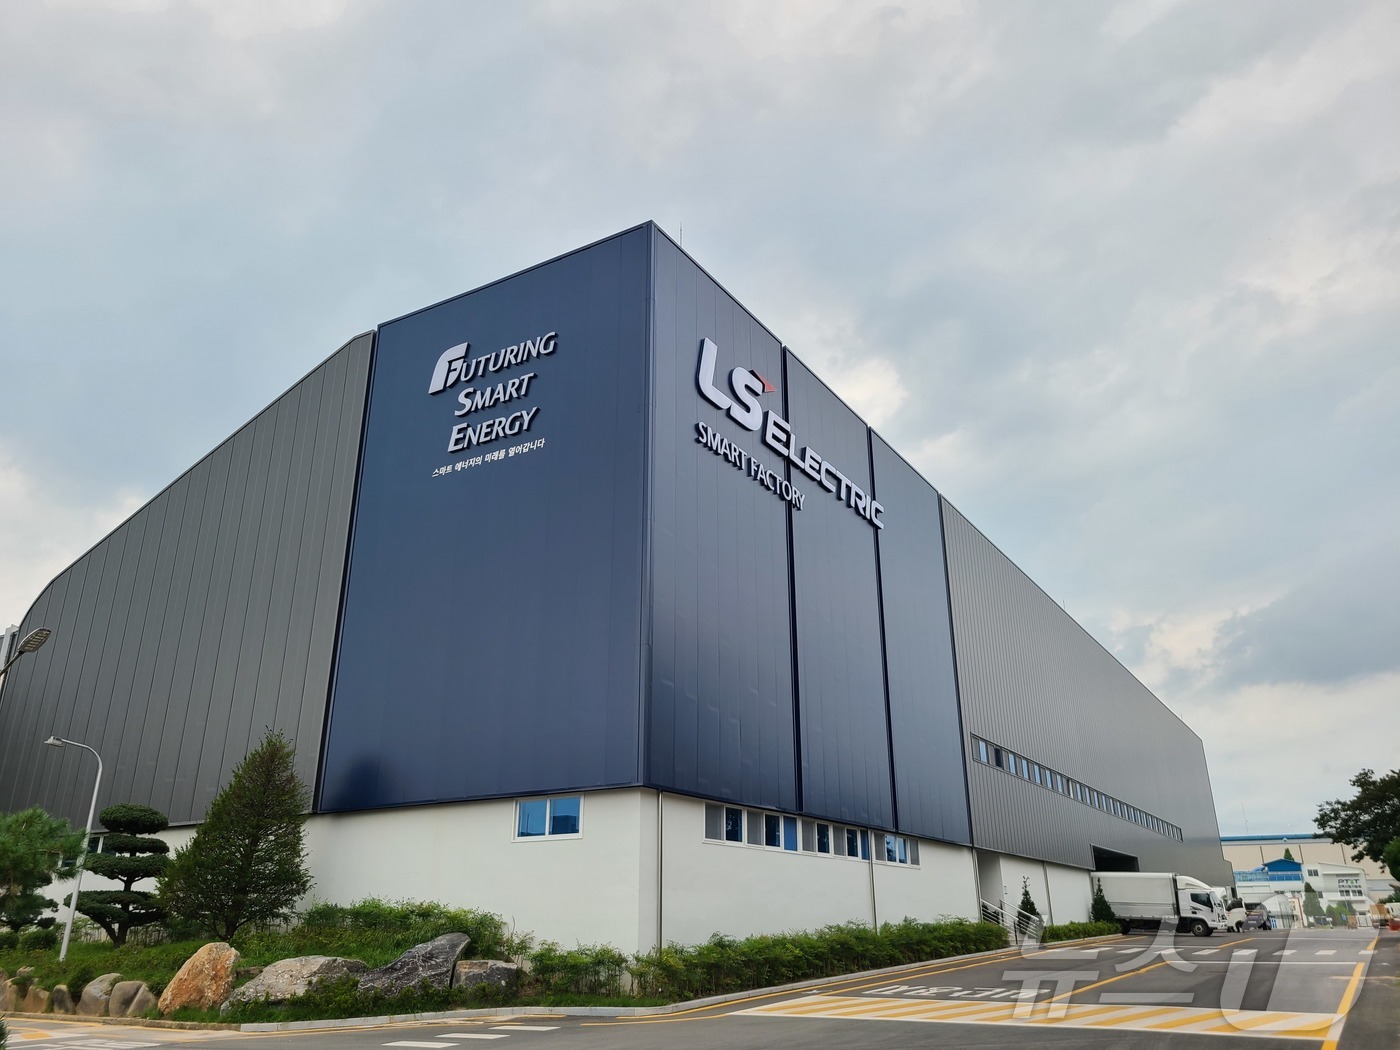
Korea Investment: "LS Electric, Simultaneous Growth in Orders & Earnings... Target Price KRW 285,000"
네이버뉴스 · 2026.06.04
📰 View original
LS Surges on AI Power Grid Boom... Growth Investment Burden is a 'Double-Edged Sword'
네이버뉴스 · 2026.06.04
📰 View original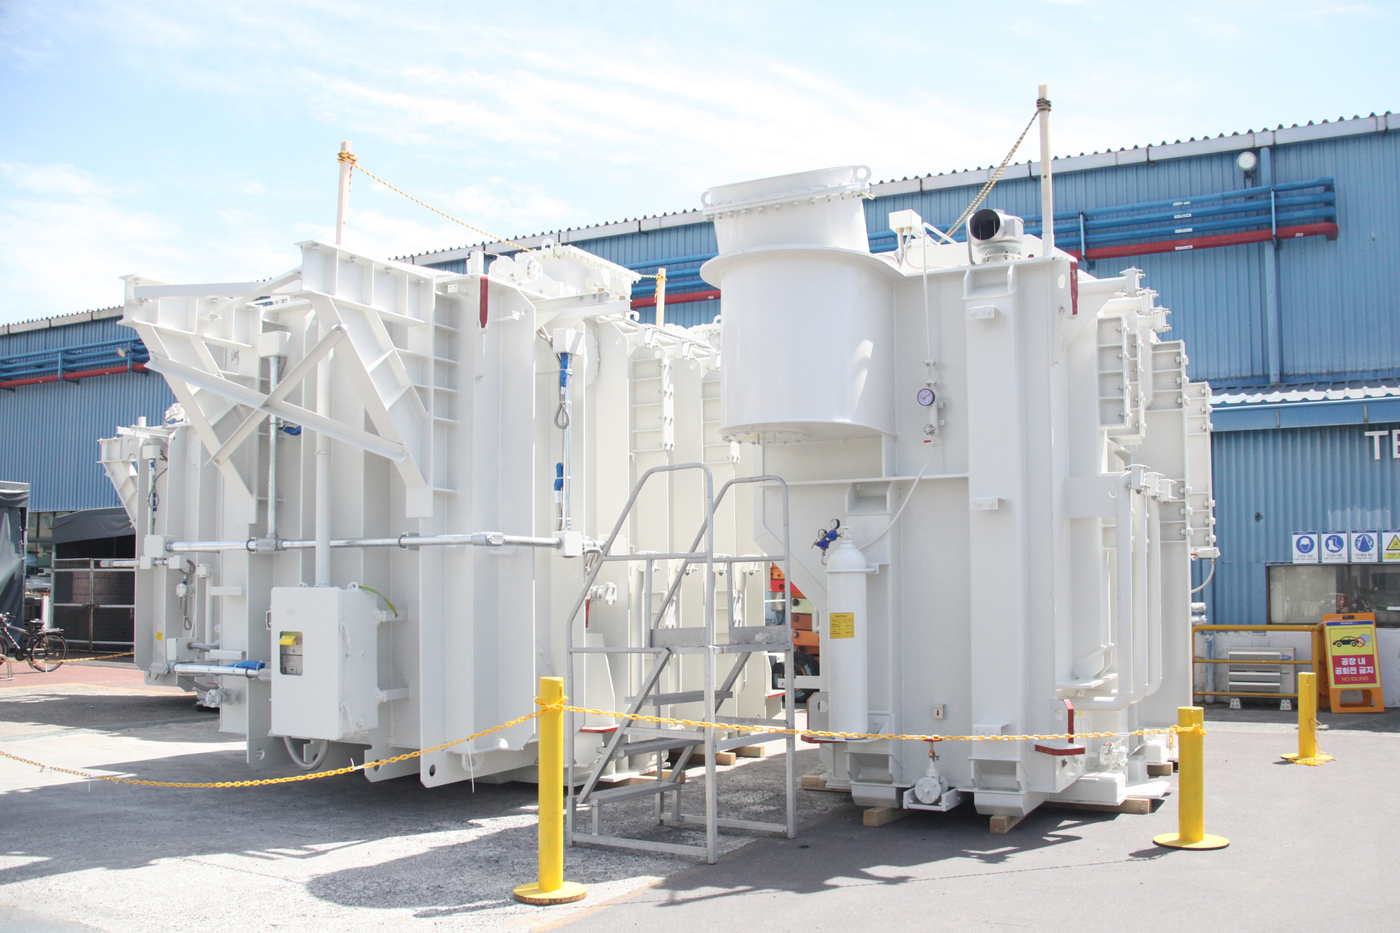
'Transformers & STATCOM' AI Power Supercycle... Top 3 Power Companies' Order Backlog Nears KRW 35 Trillion
네이버뉴스 · 2026.06.04
📰 View original
Comments 0
to comment Login