
Acorn
July 19, 2026
🏭 POSCO Holdings, Synergy of Steel Recovery and Materials Business Improvement - 2026.07.19
Positive signals are appearing simultaneously in two core business sectors: steel and secondary battery materials. The outlook that the company's performance will improve is spreading as the structural recovery of the steel industry and the improvement trend of the battery materials business overlap [1]. In particular, as structural changes in the steel industry are expected due to the easing of supply pressure from China and the effects of domestic anti-dumping measures, observations have been raised that the average PBR of major steel companies could recover from the current 0.3x to 0.7x in the future [2]. Accordingly, securities firms have raised the target price for POSCO Holdings to over 600,000 KRW, evaluating that it will lead the value re-evaluation trend in the steel industry [3].
🔗 Strategy for Strengthening National Core Resource Supply Chain
The re-evaluation momentum for POSCO Holdings goes beyond a simple rise in steel prices and is rooted in the strategy for strengthening the national core resource supply chain. Chairman Chang In-hwa revealed the strategy and future vision of POSCO Group as an 'irreplaceable company' that secures the entire supply chain process from raw materials to final parts, emphasizing that this role as a supply chain guardian will be key to redefining corporate value [11]. In particular, analysis suggests that the strategy for strengthening the national core resource supply chain is acting as a major factor in the stock price rise and serves as the background for the target price upward adjustment [6].
⚙️ Differentiated Value Chain Benefits: Steel, Materials, Energy
When systematically analyzing the benefit structure of POSCO Holdings from an industrial structural perspective, the following 1st/2nd/3rd priority differentiated benefits are derived.
1st Priority: Improvement of P·Q·C (Price, Quality, Cost) in the core steel business Daishin Securities selected POSCO Holdings as its top pick, citing the recovery of the steel industry and the turnaround of the lithium business as major growth drivers. The report forecast sales of 72.8 trillion KRW and operating profit of 3 trillion KRW for 2026, expecting an increase of more than 5% each compared to the previous year [4]. It also pointed out that POSCO Holdings' price-to-book ratio (PBR) is undervalued at 0.42x, significantly below the global steelmaker average (0.9x) and the market average (1.8x), and analyzed that the possibility of a rebound in undervalued steel stocks is gaining attention amid expectations for 'P·Q·C' improvement in the steel industry [5]. Hana Securities also predicted that earnings improvement is expected in the second half of the year as the recovery of the steel market begins in earnest, interpreting the improvement in the business environment due to steel price stabilization and increased demand [7].
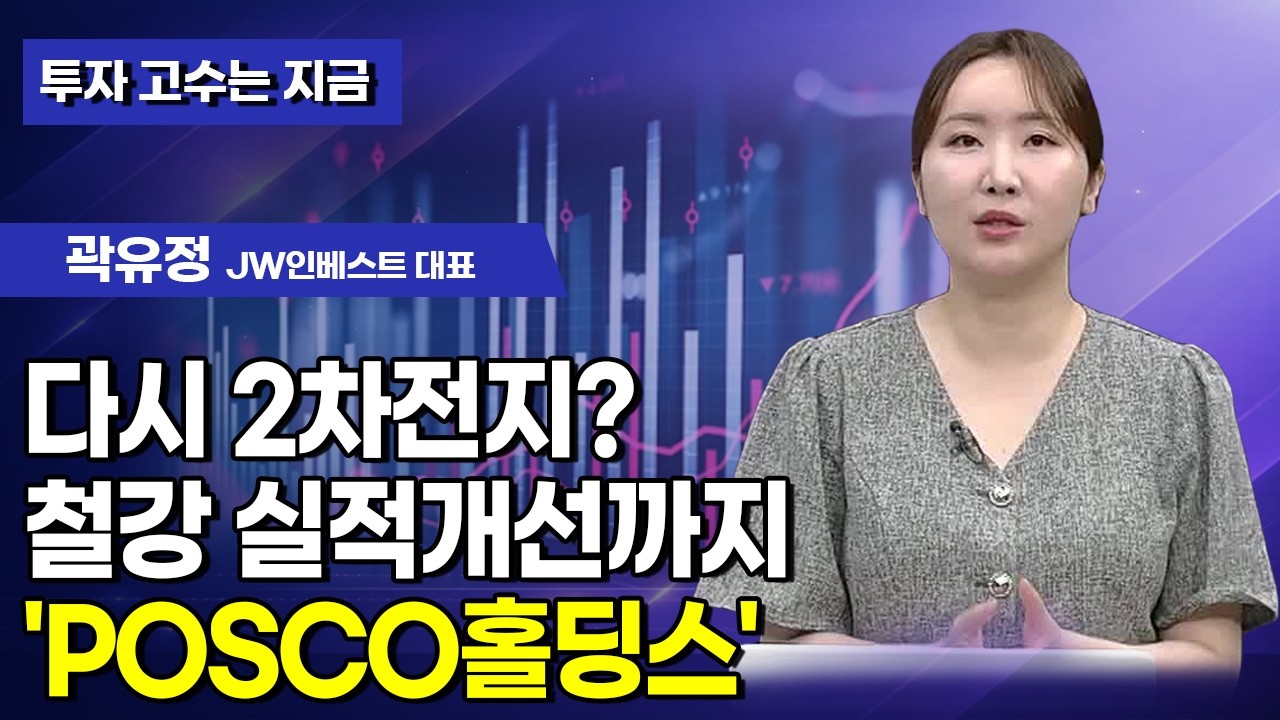
2nd Priority: Re-evaluation of the secondary battery materials business In addition to the core steel business, investors are paying attention to the performance of the materials business, a new growth engine, and the upward trend of the stock price continues as market expectations for the secondary battery materials business rise [8]. JW Invest CEO Kwak Yu-jung analyzed that POSCO Holdings has two positive factors at the same time: the re-evaluation of the secondary battery materials sector and the improvement in steel performance, noting that the improvement trend in second-quarter operating profit will particularly attract attention [12].
3rd Priority: Profit growth in the energy and palm sectors of POSCO International There is also analysis that POSCO International is being evaluated at a discount despite profit growth in the energy and palm sectors, and that the possibility of POSCO Holdings reducing its stake could act as a short-term supply and demand burden [9].
📚 Market Reaction and Acorn's Perspective
Looking at recent stock price trends, the closing price on July 17 was 311,500 KRW, down -0.95% from the previous day. The trading volume was 287,682 shares; foreign net buying data is unavailable, and institutional net buying is also unavailable. There was an adjustment reflecting the overall trend of the steel sector amid a market environment affected by Middle East issues [10], but the overall upward momentum is being maintained.
Acorn believes that the value re-evaluation trend for POSCO Holdings will accelerate as the structural recovery of the steel industry and the turnaround of the materials business align. In particular, the strategy for strengthening the national core resource supply chain is expected to act as a key driver for redefining corporate value.
📰 Reference News (10)
Steel reviving and batteries improving… Green light for POSCO Holdings’ earnings - Pinpoint News
핀포인트뉴스 · 2026.07.19
📰 View original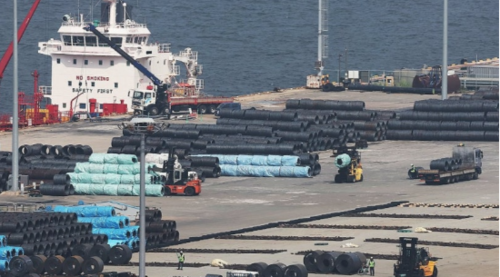
“Steel stocks finally seeing the light?”... POSCO Holdings target price exceeds 600,000 KRW
네이버뉴스 · 2026.07.18
📰 View originalPOSCO Holdings leads steel industry value re-evaluation… target price exceeds 600,000 KRW - Global Economic
글로벌이코노믹 · 2026.07.18
📰 View original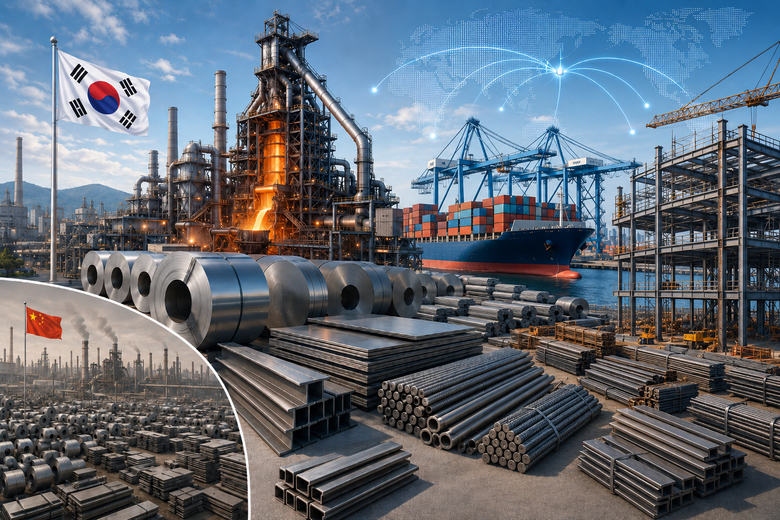
[In-the-Report] Steelmakers re-evaluated from simple material companies to AI, nuclear power, and secondary battery suppliers
네이버뉴스 · 2026.07.15
📰 View original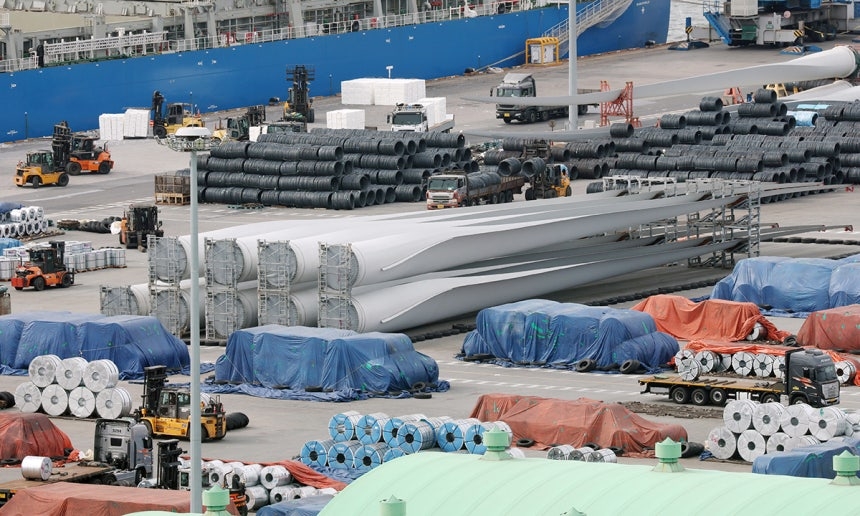
‘PBR 0.39x’ Steel Stocks… Sunshine on ‘P·Q·C’ improvement
네이버뉴스 · 2026.07.15
📰 View original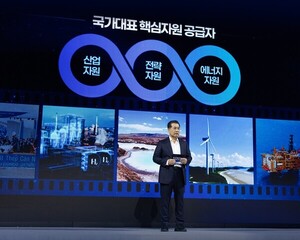
POSCO Holdings target price rises, re-evaluation driver... 'Strengthening national core resource supply chain' - thecommoditiesnews.com
thecommoditiesnews.com · 2026.07.18
📰 View original
[Securities Talk] Hana Securities "POSCO Holdings, steel recovery in full swing… H2 earnings improvement expected" - Mild Economy
마일드경제 · 2026.07.17
📰 View original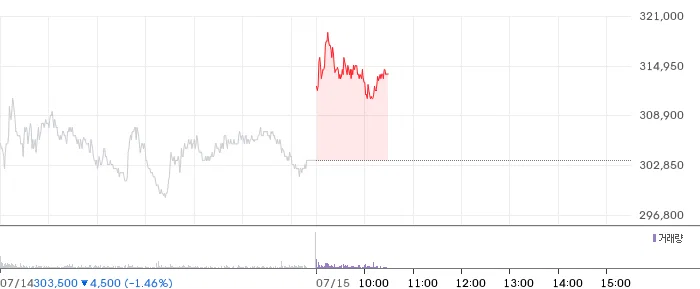
POSCO Holdings continues upward trend amid expectations for secondary battery materials: Corporate Stock Info - Jaekyung Ilbo
재경일보 · 2026.07.15
📰 View original
“Indonesian palm and Australian gas (SENEX) are doing their part… POSCO International forecasts Q2 earnings surprise”
네이버뉴스 · 2026.07.16
📰 View original
Overcoming Middle East issues, KOSPI
네이버뉴스 · 2026.07.14
📰 View original📺 Reference Videos (2)

Comments 0
to comment Login