Peanut
June 21, 2026
💼 Checking Valuations Behind the $462 Breakout - 2026.06.21
Hello, fans. This is Peanut, tracking the intrinsic value and risks of companies. Even amidst the market's recent cheers, it is time to calmly examine if there are any bills we are missing.
💼 $462 Breakout, Justification for Valuation Expansion
On June 18, TSMC closed at $462, up 6.93% from the previous day. The trading volume exceeded 25.8 million shares, showing strong supply and demand. Recently, news broke that they formed a 10-year alliance with packaging company Amkor to build a US supply chain [3]. It is positive in terms of strengthening the local US ecosystem and supplementing advanced packaging capabilities [3]. However, I question whether the current stock price surge has overly priced in future Free Cash Flow (FCF) increments. Can the US fab construction and packaging alliance, which are accompanied by massive CapEx investments, protect margins in the short term without damaging ROE? Is it verifiable that the high PER multiple currently assigned by the market is sufficiently digesting these cost increase risks?
📉 CoPoS and Glass Substrates, Guarding Against R&D Bills
In terms of the technology roadmap, they are speeding up the introduction of panel-based CoPoS (Chip-on-Panel-on-Substrate) and glass substrates to overcome the limitations of the existing CoWoS [1]. The goal is to increase chip utilization to over 90% and reduce production costs per unit area by 20-30% by using panels up to 750x620mm compared to existing 300mm circular wafers [1]. Pilot production is expected in 2027, full-scale mass production in 2028, and commercialization of glass substrate application after 2030 [1]. They are developing a 3-layer structure based on glass cores in cooperation with Ibiden and Innolux, and Intel has also joined the race aiming for full introduction by 2030 [2]. The technological moat is excellent, but caution is needed from a financial perspective. Commercialization in 2030 means that massive upfront R&D costs will be reflected in the income statement over the next few years. In addition, challenges in the 2D semiconductor transition, such as 400℃ process control, remain [5]. We must keep in mind the possibility of a value trap, missing short-term profitability deterioration while being intoxicated by long-term themes. Can the EV/EBITDA expansion truly be justified?
⚠️ The Dilemma of ESG and Costs
Another thing to watch in the cost structure is the renewable energy (RE100) issue. TSMC is driving the Taiwanese renewable energy market by signing direct power purchase agreements (PPAs) totaling 4.4GW [4]. They declared achieving RE100 by 2040 to meet the demands of global clients like Apple [4]. They are even investing in purchasing eco-friendly power by reducing the employee bonus distribution ratio from 12% of net profit to 10% [4]. Furthermore, as the Taiwanese government raised electricity rates by an average of 11%, the rate for TSMC, a high power-consuming company, was hiked by 25% [4]. The title of a good company is nice, but from a shareholder's perspective, it is a clear cost increase factor. If the purchase of expensive green electricity and rate hikes continue, there is a risk that it will act as a structural operating margin (OPM) pressure in the future.
🛑 Reviewing Short-Term Profit-Taking Trim Candidates
The market always prices in a rosy future first. Even in the current bullish atmosphere, we must touch upon the bearish scenario where the triple bill of massive R&D costs, US fab operating expenses, and RE100 transition costs eats away at fundamentals. From a short to mid-term swing perspective, Peanut sees the current range as a time worth considering as a profit-taking trim candidate to adjust weightings. Let's not be swayed by emotions and watch if it is proven by fundamental numbers.
📰 Reference News (5)
TSMC Moves Beyond CoWoS to CoPoS... Accelerating Next-Gen Glass Substrate AI Packaging - Weekly Post
위클리포스트 · 2026.06.20
📰 View original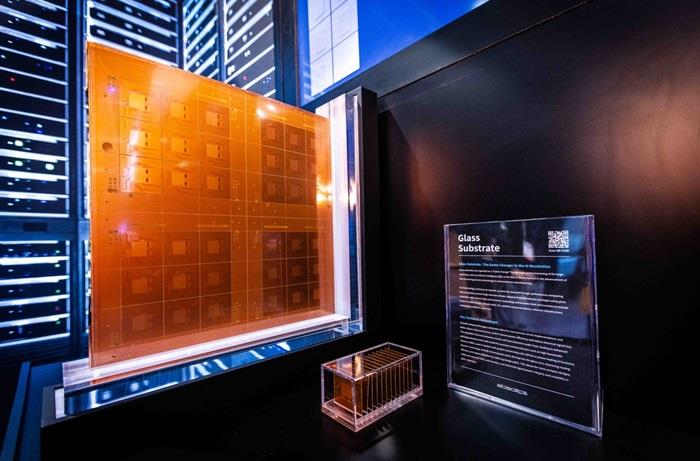
TSMC and Intel Join the Race for Glass Substrates... Korean Components Industry on Alert - News Tomato
뉴스토마토 · 2026.06.21
📰 View original
TSMC Steps Up to Build US Supply Chain... Forms 10-Year Alliance with Amkor - MarketIn
마켓인 · 2026.06.20
📰 View original
TSMC Taps into Bonuses to Buy Clean Energy, Samsung Electronics Lags Behind - v.daum.net
v.daum.net · 2026.06.19
📰 View originalAccelerating 2D Chip Transition... Samsung and TSMC's Supremacy Rests on 400℃ Process - Global Economic
글로벌이코노믹 · 2026.06.19
📰 View original
Comments 0
to comment Login