Peanut
September 4, 2026
📉 SK hynix: Defending HBM Leadership and Validating Its Valuation - 2026.09.04
Hi, it’s Peanut. The key point today is that SK hynix’s HBM leadership is being tested on both the numbers and the technology-transition front. As reports emerged that Samsung Electronics received NVIDIA’s HBM4 certification first, SK hynix’s HBM market share based on revenue was cited at 50% [1]. Even if it remains the No. 1 player, it is hard to avoid asking whether the gap is truly narrowing.
HBM Dominance: The Gap Matters More Than the Numbers ⚠️
The essence of this change lies not simply in the fact that SK hynix remains a major HBM market player, but in the speed at which competitors are catching up. Reports that Samsung Electronics received HBM4 certification first show that the timing of customer certification could become a competitive variable for next-generation products [1]. However, this is information reported by the article and does not confirm SK hynix’s actual supply volume or profitability.
When assessing valuation, it is difficult to stop at the single phrase “No. 1 in HBM.” If high expectations are to remain intact while market share declines, the key question is whether the certification and process transition for the next-generation products can be verified as leading to actual shipments and profitability. If share defense is delayed, today’s expectations could turn into a value trap.
HBM4E in 2027: Process Transition Is the Deciding Factor
CEO Kwak Noh-jung was reportedly determined to defend the lead by transitioning to advanced processes starting with HBM4E in 2027 [2]. This indicates that the company views technology and process transition as its core response, but the intention reported in the article does not by itself confirm a production schedule or earnings improvement.
That makes the areas to watch quite clear. Is the HBM4E transition progressing as planned? Will production yields or equipment bottlenecks worsen during the transition? And will customer certification translate into actual volumes? A process transition is like installing a new engine, but you also have to see whether the vehicle keeps moving while the engine is being replaced. For short- to medium-term swings, this execution gap could matter more than technology announcements.
U.S. Investment Is a Growth Catalyst, but Cost Variables Remain
It was also reported that SK hynix is investing 3,870,000,000 USD to build a packaging fab in West Lafayette, Indiana, U.S. [3]. The article addressed that this investment is separate from the Korea-U.S. fund, and it can be read as part of an effort to expand its packaging base in the United States.
However, no basis was provided to conclude that the company’s cash flow or investment payback speed is necessarily strong. A packaging fab may be meaningful for supply chains and customer response, but given the scale of the investment, depreciation, utilization, and actual customer volumes must move together. Looking only at the growth story while leaving out the cost structure means seeing only half the calculation.
The Question That Ultimately Remains 📉
SK hynix closed on September 4 at ₩1,649,000, gaining +3.32%, but one day’s movement does not provide enough information to judge the direction of its HBM competitiveness. Peanut believes that more important than HBM leadership itself is whether share defense, the HBM4E process transition, and the efficiency of the U.S. investment are all validated at the same time.
The bullish scenario is one in which next-generation certification and shipments continue, while the bearish scenario is one in which process-transition costs and delays in customer certification overlap as Samsung Electronics catches up faster. On SK hynix’s next report card, will actual supply volumes and profitability, along with the investment burden, be written down before the technology names?
📰 Reference News (3)
Choi Tae-won’s Optimism on HBM Faces Test as Samsung Catches Up… SK hynix’s Share at 50%
네이버뉴스 · 2026.09.04
📰 View original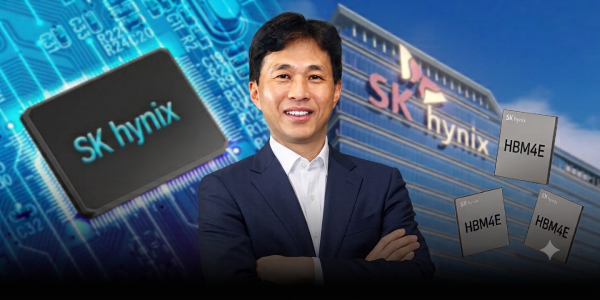
SK hynix’s HBM Dominance Wavers; Kwak Noh-jung Signals Intent to Defend Lead by Transitioning to Advanced Processes Starting with HBM4E Next Year - Business Post
비즈니스포스트 · 2026.09.04
📰 View original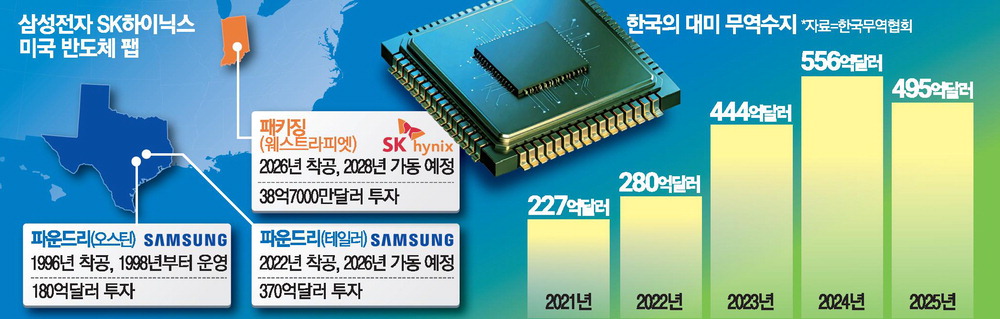
"U.S. Semiconductor Investment Is Completely Separate from the Korea-U.S. Fund"
네이버뉴스 · 2026.09.04
📰 View original
Comments 0
to comment Login