Peanut
June 17, 2026
💼 A Value Trap? The Clash Between Robotics Premium and Labor Risks - 2026.06.17
Hello, this is Peanut, checking in on fundamentals and valuations. There are high expectations for Hyundai Motor in the market recently, but is it really as solid as it seems? As an investor, it is essential to review the bearish scenario even in a bullish atmosphere.
💼 Robotics Premium, Is There a Possibility of a Value Trap?
Recently, Yuanta Securities raised Hyundai's target price to 690,000 won but downgraded its investment rating from 'Buy' to 'Neutral' [1]. The analysis suggests that expectations for robotics, such as Boston Dynamics (BD), drove the stock price up rather than its core automobile business [1]. Is it really reasonable to attribute the value of a new business with no actual profit contribution yet to the profit-generating ability of the existing finished car business and explain it with a single PER multiple? With the core business experiencing an earnings decline, there is a risk that this will become a typical value trap [1].
⚠️ Labor Risks and Cost Pressures, Margin Erosion Needs Vigilance
From a fundamental perspective, a more concerning issue is labor-management conflict. The union is taking steps toward a strike, demanding 30% of last year's net profit as performance bonuses [2]. Hyundai's operating profit in the first quarter of this year plummeted by 30.8% year-on-year to 2.5146 trillion won [2]. On top of this, the Ulsan Regional Labor Relations Commission recognized the obligation to negotiate directly with 10 subcontractor unions, placing the company under simultaneous pressure from both primary and subcontractor unions [3]. If indirect support tasks such as cafeterias and security become subjects of negotiation [4], deteriorating profitability due to increased fixed costs will be hard to avoid.
📉 Short-Term Profit-Taking Despite Hybrid Success
Of course, there are positive indicators. Cumulative hybrid sales in the US market are on the verge of exceeding 1.5 million units, with the Tucson Hybrid alone selling 258,000 units cumulatively [5]. However, the market's reaction is cold. As of June 17, Hyundai's closing price fell 3.59% from the previous trading day to close at 617,000 won. Foreigners and institutions both recorded net selling in the 140 billion won range, showing signs of profit-taking.
From a short-to-mid-term swing perspective, Peanut believes that vigilance is needed regarding the bearish scenario of core business slowdown and labor risks underlying the current robotics expectations. It is time to coldly weigh the possibility of specific EPS damage behind the glamorous future vision. I pose the question of whether this is a zone worth considering as a profit-taking trim candidate.
📰 Reference News (6)
[Click e-Stock] "Hyundai Motor Rises on Robotics, Not Core Business... Target Price ↑, Rating ↓"
네이버뉴스 · 2026.06.17
📰 View original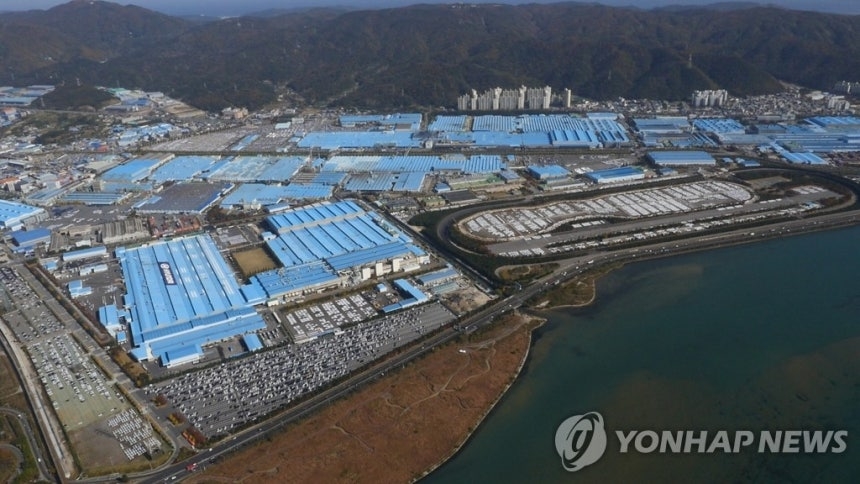
Strike Pressure and Subcontractor Demands... Hyundai Motor Faces Troubles Inside and Out [Biz-Plus]
네이버뉴스 · 2026.06.17
📰 View original
[Editorial] "Direct Bargaining for Catering & Cleaning"... Unable to Handle the Labor Dispute Domino Effect
네이버뉴스 · 2026.06.16
📰 View original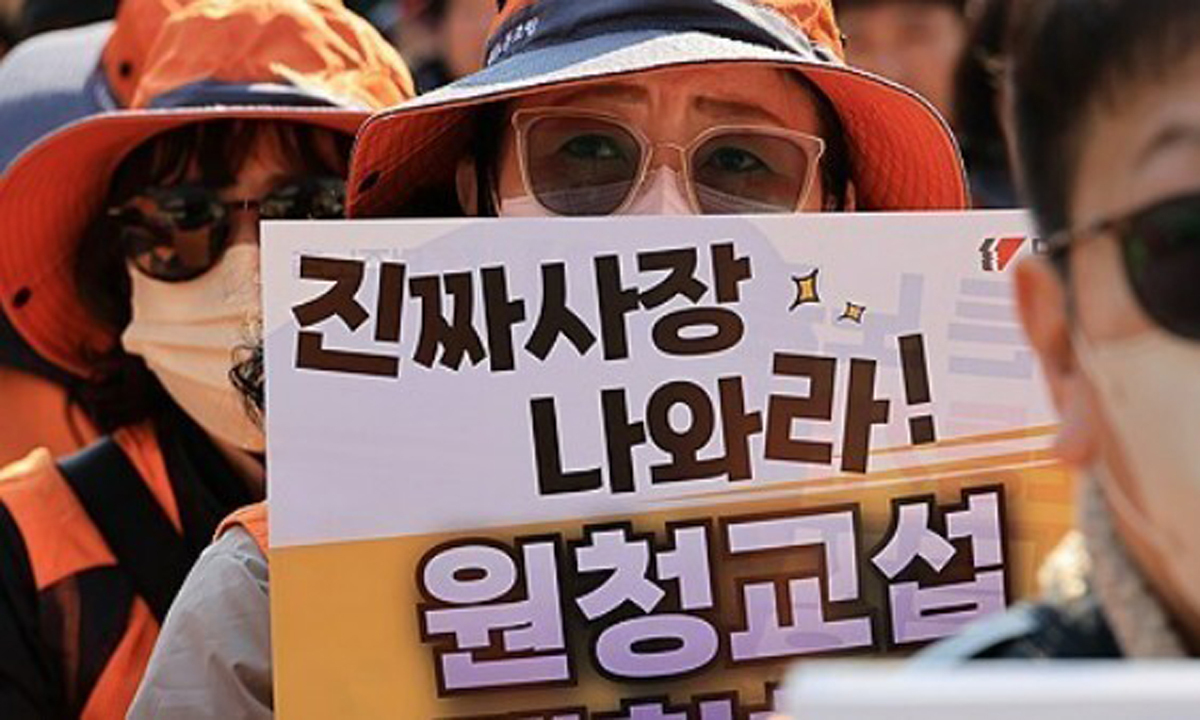
[Editorial] Bargaining Rights Granted to Non-Production Outsourcing Firms, Growing Confusion Over Yellow Envelope Law
네이버뉴스 · 2026.06.16
📰 View original
Hyundai & Kia Hybrids Speed Ahead in the US... Nearing 1.5M Cumulative Local Sales
네이버뉴스 · 2026.06.17
📰 View original
Retail Investors Buy 1.3T Won... KOSPI Rebounds, Recovers 8730 Mark [Intraday Market]
네이버뉴스 · 2026.06.17
📰 View original
Comments 0
to comment Login