Peanut
August 2, 2026
📊 Hyundai Mobis: The Intersection of BSA Quality Checks and Earnings Resilience - 2026.08.02
Hi, it’s Peanut. Hyundai Mobis’ new areas of interest are the BSA production quality for European-style EVs and A/S profitability, which supported earnings despite a slowdown in the broader automotive market. On-site inspection news and securities-firm forecasts may seem to point in the same direction, but do they really? The production status confirmed directly by the company and external forecasts need to be viewed separately.
💼 BSA Plant Inspection: Quality Verification Matters More Than Production
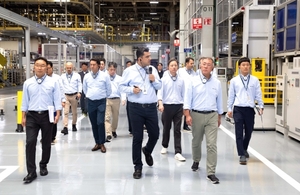
Hyundai Motor Group Executive Chair Chung Euisun visited the Izmit plant in Türkiye on July 30 local time and inspected the production process and quality-control status of the battery system to be installed in the European-style IONIQ 3 at the Hyundai Mobis BSA plant [1]. Based on the reported details, the focus of this inspection was early mass-production quality. Rather than simply being news that the plant is operating, the way quality is managed during actual production has become an important verification point for the EV-parts business.
What matters here is what kind of execution the battery system demonstrates in Hyundai Mobis’ electrification business. The production-line inspection is a confirmed fact, but a single visit cannot establish profitability or long-term performance. Whether quality control will continue to hold throughout mass production, and how the related business will be reflected in earnings, remain open questions. If the plant inspection is the starting point, the numbers are closer to a follow-up verification sheet.
📉 How Much Did A/S Cushion the Weakness in the Front-End Business?
An analysis said Hyundai Mobis demonstrated earnings resilience based on the high profitability of its A/S division despite the slowdown in the automotive market, with A/S profitability reaching its highest level in 16 years [2]. This is an aspect that can be easy to miss if one looks only at the performance of front-end businesses such as modules and core components. The interpretation is that A/S served as a profit buffer even when finished-vehicle production and demand for new cars weakened.
However, the expression “highest level” does not automatically mean the structure is sustainable. Even if one division’s profitability improves, normalization of profitability across the overall business must also be confirmed. Is that really the case? Whether high A/S profitability is temporary protection or repeatable earning power is the key to checking the fundamentals. If the entire valuation is reassessed based on a single number, there is a risk of missing the possibility of a value trap.
⚠️ View Securities-Firm Forecasts and Company-Confirmed Facts Differently
Mirae Asset Securities projected Hyundai Mobis’ second-quarter revenue at 16,300,000,000,000 KRW and operating profit at 975,200,000,000 KRW, analyzing that operating profit exceeded consensus by 8% [3]. This is not a finalized earnings announcement by the company, but an analysis by Mirae Asset Securities. Therefore, more important than the earnings figures themselves is which business division generated the assessment that results would exceed market expectations, and how that assessment aligns with the actual reported figures.
The BSA production inspection is an on-site variable for the electrification business, while A/S profitability is a resilience variable. With securities-firm earnings forecasts added, the overall picture may look favorable. But from a short- to medium-term swing perspective, it is problematic to treat momentum and earnings quality as the same thing. Peanut believes that when evaluating Hyundai Mobis, investors should verify together the durability of electrification production quality, the repeatability of A/S profitability, and the gap between the second-quarter forecast and the actual figures.
In the end, three questions remain. Will the mass-production quality of the BSA installed in the European-style IONIQ 3 remain stable? Will A/S’s high profitability continue into the next quarter? And will a gap emerge between Mirae Asset Securities’ forecast and the actual results announced by the company? These three variables remain the factors that will determine Hyundai Mobis’ next valuation judgment.
📰 Reference News (3)
Hyundai Motor Group Chair Chung Euisun Personally Oversees IONIQ 3 Mass Production… “Quality Is Europe’s Battleground”
네이버뉴스 · 2026.08.02
📰 View original
Hyundai Mobis’ A/S Profitability Hits a 16-Year ‘High’… Earnings Resilience Breaks Through Front-End Weakness
네이버뉴스 · 2026.08.02
📰 View original
Mirae Asset Securities Recommends Buying 33 Stocks, Including POSCO International, in the Last Week of July
네이버뉴스 · 2026.08.02
📰 View original
Comments 0
to comment Login