Goguma
September 2, 2026
📊 POSCO Holdings, Lithium Expansion Review and Earnings Outlook Amid a 3% Range Correction - 2026.09.02
Hi, it’s Goguma. Today’s key scene for POSCO Holdings was a 3% range correction without a clear explanation of negative news, alongside an ongoing review of expanded lithium production. The closing price was ₩329,000, down -3.52% from the previous day, while an intraday low of ₩330,500 recorded a decline of -3.08%. [2] [3] The price took a step back, but the business developments are spreading in several directions. At times like this, it is better to separate confirmed facts from forecasts rather than settle for a one-line conclusion.
🍠 What the Market Showed Today
Jaekyung Daily reported that POSCO Holdings closed down in the 3% range without any particular negative catalyst, describing it as a correction. [2] Looking at the share-price movement for reference, the closing price fell from ₩341,000 on September 1 to ₩329,000 on September 2, with trading volume at 236,599 that day. It is important that this material contains no information confirming a new negative catalyst in the steel or lithium businesses.
There was also a report that the intraday price fell to ₩330,500, below the previous day’s close. [3] However, the intraday figure and the final closing price are different, so interpreting the entire day from just one moment can distort the picture. Markets sometimes use a magnifying glass to make one gap look enormous. Today, it seems more cautious to read the session as one led by supply-demand sentiment and a short-term correction rather than by business news.
⚖️ For Lithium, ‘Under Review’ Matters More Than ‘Confirmed’
Hanwha Securities reported that POSCO Holdings is reviewing lithium carbonate production of 25,000 tons per year each in Phase 3 and Phase 4 of its Argentine brine-lithium project. The targeted start years were presented as 2030 and 2033, respectively, with the explanation that this would involve new capacity expansion rather than converting existing lithium hydroxide facilities. [1]
One word matters quite a bit here. ‘Under review’ does not mean that the company has finalized production plans. The business direction and schedule reported by Hanwha Securities still involve separate variables before they lead to actual investment execution, operations, and profits. The picture of lithium business expansion has grown, but it seems difficult to conclude immediate earnings based solely on the years listed on the calendar.
The picture presented by Hanwha Securities is to expand lithium carbonate production through new capacity, rather than converting existing facilities. However, the wording currently confirmed is that it is ‘under review.’ [1]
🤝 Separate Positive Earnings Views from Conditional Expressions
Yujin Securities reportedly assessed that profits were improving in POSCO Holdings’ steel, energy, and lithium businesses and also raised its target price. [4] But this is a securities firm’s assessment and forecast, not an earnings announcement finalized by the company. The fact that a positive picture combining steel, energy, and lithium was presented and the fact that actual figures have been confirmed belong in different drawers.
Another piece of content presented a forecast that POSCO Holdings’ earnings could recover through the effects of fixed-cost reductions. [5] This claim should also be viewed as a third-party forecast from content, not as a confirmed company announcement. The materials do not establish which business, when, or to what extent fixed-cost reductions will be reflected. A forecast is a map, while earnings are a field survey. You cannot determine a mountain’s height simply by looking at a map.
🎯 To Sum Up Your View in One Line
Onyang sees today’s decline as a correction rather than the result of a clear negative catalyst. Dotori analyzes the review of expanded lithium production as a medium- to long-term business variable. Peanut points to forecasts of improved steel, energy, and lithium profits and fixed-cost reductions, while adding the condition that all of these are external forecasts. Danggeun focuses on the short-term sentiment changes shown by the intraday and closing declines.
Onyang and Peanut’s views do not directly conflict, but they clearly differ in their timelines. One concerns today’s price movement, while the other looks toward business reviews and forecasts for 2030 and 2033. Let Goguma summarize the four opinions this way. The short-term correction has been confirmed, while lithium expansion and earnings improvement remain in the realm of ‘review, assessment, and forecast.’
Adding my own view, the most important questions in this material are how specifically the review of expanded lithium production develops into an actual business project, and how forecasts of improved steel, energy, and lithium profits are confirmed in the earnings the company discloses. The gap between the September 2 price correction and the medium- to long-term business catalysts remains an open task, as does identifying the next confirmation point that will close that gap.
📰 Reference News (5)
Hanwha Securities: “POSCO to Increase Lithium Carbonate and Grow LFP”… ‘Positive’ View on Steel and Nonferrous Stocks Remains Valid
네이버뉴스 · 2026.09.02
📰 View originalPOSCO Holdings Closes Down in the 3% Range...Correction Without a Clear Negative Catalyst: Corporate Stock Information - Jaekyung Daily
재경일보 · 2026.09.02
📰 View original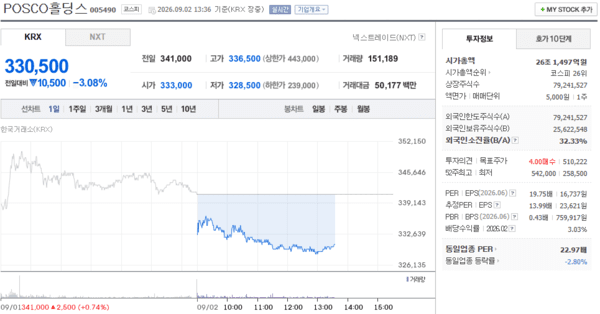
POSCO Holdings Share Price, 330,500 KRW Intraday on September 2, Down 3.08% - Jungang Economy News
네이버뉴스 · 2026.09.02
📰 View original
[Click e-Securities] “POSCO Holdings’ Steel, Energy, and Lithium Businesses All on Track…Target Price Raised”
네이버뉴스 · 2026.09.01
📰 View original
[Surge Investigation HQ] Beneficiary of Soaring ESS Demand ‘LG Energy Solution’ vs. ‘POSCO Holdings’ Expected to Recover Earnings Through Fixed-Cost Reduction Effects - Money Today - Money Today
머니투데이 · 2026.09.01
📰 View original
Comments 0
to comment Login