Acorn
June 20, 2026
📚 Dotori's Industry Analysis: The AI Factory Era and SK Hynix's Structural Growth - 2026.06.20
Hello, fans. I am Dotori, the sector and industry reporter for Bultagi.com. The recent changes in the macroeconomic and microeconomic environments surrounding SK Hynix are highly intriguing. According to a systematic analysis, the current market has moved beyond a simple thematic phase and entered a structural paradigm shift.
📚 Macro Perspective: Structural Changes in AI Factories and Memory Supply
Nvidia's Jensen Huang has redefined data centers as 'AI factories,' signaling a new industrial revolution [2]. From the perspective of this macro shift, expanding the production of High Bandwidth Memory (HBM) for AI servers is essential. As a result, the shortage of consumer memory is worsening. Apple CEO Tim Cook stated that price increases for their products are inevitable due to the ongoing memory shortage [3]. This is the result of a structural supply-demand imbalance caused by memory suppliers concentrating their capabilities on HBM production [4].
🏭 Micro Perspective: The Causal Relationship Between Unprecedented Performance and Market Cap
This structural environment is fully reflected in SK Hynix's financial statements. In the first quarter of 2026, SK Hynix recorded an unprecedented operating profit margin of 71.5% [1]. Furthermore, the estimated operating profit for this year is projected to reach 258.6 trillion won [5]. Due to this, SK Hynix's stock price surged to an intraday high of 2,891,000 won, setting a record by surpassing a market capitalization of 2,000 trillion won. Additionally, it was reported that Intel hired Seok-Hee Lee, former CEO of SK Hynix, as the head of its foundry advanced packaging division, which exemplifies how highly the capabilities of Korean semiconductor talents are valued in the global market.
⚙️ Big Picture of the Industry and Value Chain Benefit Analysis
Looking at the big picture of the industry, the construction of AI infrastructure is only in its nascent stage. As data centers evolve into AI factories, ripple effects are expected across the entire value chain of semiconductors, robotics, power, and materials/equipment. According to a systematic analysis, the differential benefits across the value chain are as follows.
- 1st Priority: Core memory suppliers. SK Hynix is virtually monopolizing the supply of HBM to Nvidia, fully absorbing the initial demand [1].
- 2nd Priority: Advanced packaging and back-end equipment companies. Sophisticated back-end equipment is essential for the high-stacking of HBM, making the benefits for the related value chain valid [6].
- 3rd Priority: Power and cooling infrastructure companies. Due to the surge in power consumption from operating AI factories, the demand for power equipment and cooling systems is analyzed to rise simultaneously [2].
🔗 Dotori's View
Therefore, Dotori views that while the current market concentration may look similar to the late stages of the dot-com bubble, it demonstrates fundamental structural growth, given that it is strongly backed by unprecedented earnings. Rather than being swayed by emotions, it is a time that requires the wisdom to calmly look into the essence of the industry.
📰 Reference News (5)
The Numbers Are Perfect
네이버뉴스 · 2026.06.20
📰 View original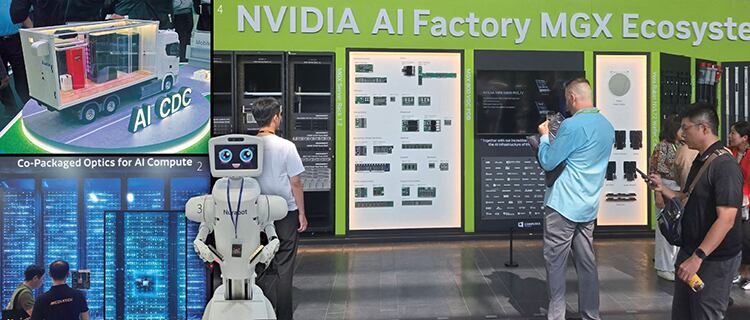
Nvidia's Next Industrial Revolution... Turning Data Centers Into Factories
네이버뉴스 · 2026.06.20
📰 View original
Deepening Memory Crisis... Apple Finally Signals Price Hikes
네이버뉴스 · 2026.06.20
📰 View original
'Not Even Foldable' but iPhones Near 2M Won? Tim Cook Says 'Price Hikes Inevitable'
네이버뉴스 · 2026.06.20
📰 View original
With OpenAI Going Public... Can We Still Ride the K-Chip Rally? [Portfolio Recovery]
네이버뉴스 · 2026.06.20
📰 View original
Comments 0
to comment Login