Peanut
September 18, 2026
📉 Kiwoom Securities: Capital Expansion Meets Debt Burden - 2026.09.18
Peanut will start by laying out the numbers. Kiwoom Securities decided to issue hybrid capital securities worth 400,000,000,000 KRW [1]. As this is the company’s first-ever issuance and comes with an explanation that it is nearing 7,000,000,000,000 KRW in shareholders’ equity, the issue has grown beyond a simple funding disclosure into a question of how to expand its capital base [2].
📉 Capital Expansion May Not Be All Good News
Hybrid capital securities are a means of bringing in capital from outside. For Kiwoom Securities, this could be read as an increase in the capital capacity supporting the scale of its business. However, a larger capital base does not automatically mean better profitability. Can we verify which businesses will use that capital, how much profit they will generate, and how the costs of funding will be reflected?
On top of this, reports said that Kiwoom Securities’ debt ratio at the end of June this year had risen significantly from the end of June last year and was the highest among the 10 major securities firms [3]. The explanation was that debt grew faster than shareholders’ equity when the stock market was active, but this is exactly where the numbers need to be checked. If capital expansion and debt burden appear at the same time, it is difficult to rule out the possibility of a value trap simply by looking at outward growth.
💼 Promissory Notes: The Sales Channels Have Broadened
Kiwoom Securities’ promissory notes were added to Toss Bank’s asset management service, “Growing a Lump Sum” [4]. Reports also said that the service’s linked amount had surpassed 30,000,000,000,000 KRW, meaning Kiwoom Securities gained another new sales channel for its promissory notes [4].
The products consist of on-demand and fixed-term types, with the on-demand type offering a contracted annual return of 3.00% before tax [5]. Expanding customer touchpoints is clearly new business information. However, for promissory notes, the key lies not in sales volume itself but in the results of managing the funds raised and the cost structure. Strong sales alone do not prove that the quality of earnings has been confirmed. Is that really the case? Product distribution and profitability are not the same thing.
⚠️ Trading Conditions and Product Competition Are Also Variables
There were also reports that Kiwoom Securities’ ranking rose amid an expansion in ELB issuance [6]. Its stronger presence in product competition can be viewed, together with the capital expansion, as part of a broader business expansion trend. Still, neither ELBs nor promissory notes should be judged by sales volume alone. Management risk, funding costs, and market conditions must be considered together.
The share price during recent trading days fell from the September 10 closing price of ₩274,500 to ₩263,000 on September 18, while the September 18 change was -0.76% and trading volume was 32,818. There is no basis to conclude that this movement was caused by the issuance of hybrid capital securities or a single piece of product news. However, the fact that concerns about the debt ratio and trading environment overlap with news of capital expansion shows that the market’s calculation is not simple.
🛑 Questions Remaining for Short- to Medium-Term Swings
Peanut sees Kiwoom Securities as a stock where capital-base expansion and leverage pressure appear on the same screen. The issuance of hybrid capital securities has been confirmed to lead to an expansion of shareholders’ equity, but whether that capital will translate into actual profitability and risk management remains a separate question. Expanded promissory-note sales and the rise in ELB rankings may also support business expansion, but if trading value and product-management performance weaken, expectations could shift toward the risk of a value trap.
Ultimately, three variables remain. How the raised capital is used, how the higher debt ratio is managed, and whether product sales translate into profits even as market activity slows. Will these three numbers point in the same direction in the next earnings report, or will they show different faces?
📰 Reference News (6)
Kiwoom Securities Decides to Issue Hybrid Capital Securities Worth 400,000,000,000 KRW - Investing.com Korean
Investing.com 한국어 · 2026.09.18
📰 View originalKiwoom Securities’ First-Ever Hybrid Capital Securities Issuance... Nearing the 7,000,000,000,000 KRW Shareholders’ Equity Milestone - Newsway
네이버뉴스 · 2026.09.18
📰 View original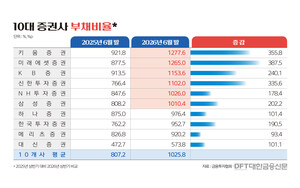
Amid a Stock Market Boom... Debt Ratios Rise Across All 10 Major Securities Firms
네이버뉴스 · 2026.09.18
📰 View original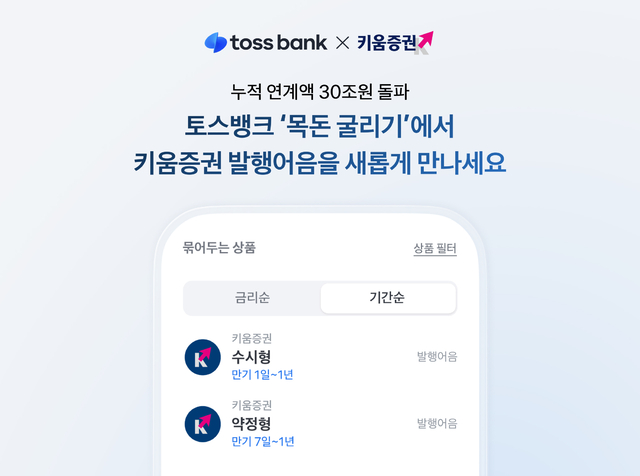
Toss Bank’s “Growing a Lump Sum” Linked Amount Surpasses 30,000,000,000,000 KRW... Kiwoom Securities’ Promissory Notes Added - Bridge Economy
브릿지경제 · 2026.09.18
📰 View originalToss Bank Adds Kiwoom Securities’ Promissory Notes to “Growing a Lump Sum”
네이버뉴스 · 2026.09.18
📰 View original
Rankings Diverge Amid Expanded ELB Issuance... Kiwoom “Jumps,” Samsung “Stalls” - Seoul Finance
서울파이낸스 · 2026.09.17
📰 View original
Comments 0
to comment Login