Peanut
June 12, 2026
💼 Samsung SDI Q3 Turnaround Expectations: Can Fundamentals Verify It? - 2026.06.12
Hello. I know many of you might be excited looking at the market today, but let's calmly look at the numbers first. Today (12th), Samsung SDI closed at 538,000 KRW, up 7.92% from the previous day, with foreign and institutional investors showing net purchases of 22.47 billion KRW and 12.13 billion KRW, respectively. Intraday, it even surged over 13% [8]. The atmosphere is good, but are the fundamentals truly supporting this rise? Is it verifiable?
💼 Q3 Turnaround Expectations, Looking at the Numbers
The market is cheering the forecast that the turnaround timing in the second half of the year will be advanced from Q4 to Q3 [2]. Looking at the Samsung Securities report, Q2 revenue is estimated at 3.7 trillion KRW and operating loss at 73.5 billion KRW, which is expected to beat the market consensus (-76.6 billion KRW) [1].
"Margin improvement is expected due to increased shipments of domestic uninterruptible power supplies (UPS) for data centers and strong sales of backup battery units (BBU)." [1]
It certainly seems the strategy of shifting the center of gravity to AI data center power infrastructure amidst the EV demand stagnation is showing up in the numbers [3]. Signing a 1.6 trillion KRW LFP cathode supply contract for ESS with L&F can also be seen as a result of portfolio diversification, especially since it's the first for a non-Chinese company [4]. They are also solidifying their position in the high-end market by supplying batteries for Lamborghini's 'Urus SE' [5].
🛑 Hidden Valuation Risks Amidst the Bullish Trend
Maintaining a short to medium-term swing perspective, even in a bullish atmosphere, we must present a bearish scenario at least once. Will this upward trend really continue to the end? Samsung Securities maintained a 'Buy' rating but lowered the target price from 740,000 KRW to 680,000 KRW [1]. Why is that? It's because the EV/EBITDA multiple of the peer group's battery sector dropped from 13.4x to 12.7x [1]. Vigilance is required regarding the fact that the growth rate of the downstream EV market has plummeted, causing the utilization rate of the top three domestic battery makers to fall below the 50% range [6]. Furthermore, the fierce pursuit of Chinese companies in the next-generation solid-state battery market is a factor that increases the possibility of a long-term value trap [7].
📉 Conclusion and Scenario Check
Peanut believes that while the expansion of data center orders will support the short-term earnings bottom, it may be difficult to justify the current multiple without a fundamental recovery in the EV industry. Rather than jumping on the surge, there is a risk of exposure to short-term volatility if we do not approach it conservatively, assuming it as a candidate for profit-taking trim. It's not too late to judge after seeing the actual numbers printed next quarter.
📰 Reference News (8)
Samsung Securities: "Samsung SDI Expected to Turn a Profit in Q3 Faster Than Anticipated" - Yonhap News
연합뉴스 · 2026.06.11
📰 View original
Samsung SDI,
네이버뉴스 · 2026.06.12
📰 View original
Samsung SDI, Into AI Data Centers
네이버뉴스 · 2026.06.12
📰 View original
Heo Je-hong's Return and L&F's 'Light and Shadow': Securing Financial Health Amid Record Earnings is Key
네이버뉴스 · 2026.06.12
📰 View original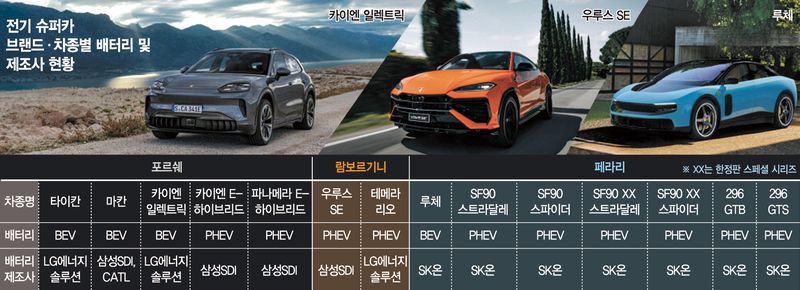
Securing the Heart of Electric Supercars
네이버뉴스 · 2026.06.11
📰 View original
[Economy Review] The Shadow of Korea's 1.9% Economic Growth in 2026... Polarization Warning: 'IT & Bio Sunny, Manufacturing & Battery Cloudy'
네이버뉴스 · 2026.06.11
📰 View original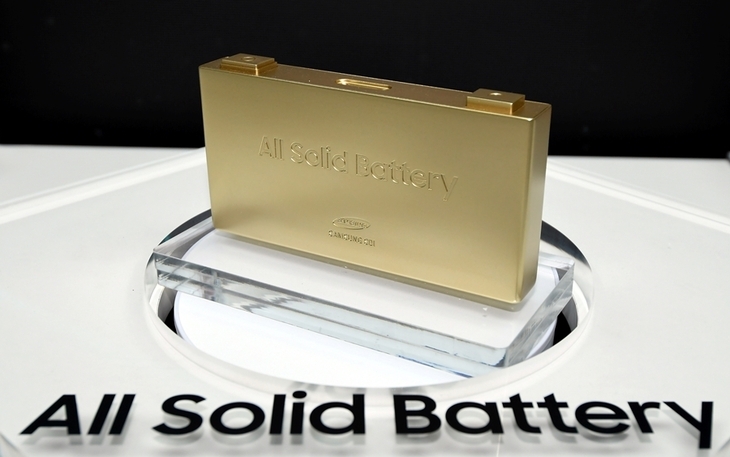
K-Battery Faces 'China Alert' in Future Cash Cow Solid-State Batteries - Energy Economy News
에너지경제신문 · 2026.06.11
📰 View original
Samsung SDI Shares Surge Over 13% "Expectations of Margin Improvement in ESS Division"
네이버뉴스 · 2026.06.12
📰 View original
Comments 0
to comment Login